CTeBockhorst's Blog

The Mortgage and Real Estate Scoop

  • Home
  • About
  • Blog
  • Resources
    • Calculators
    • Download My eGuide Today!
    • First Time Buyer Tips
    • First Time Seller Tips
    • Loan Checklist
    • Loan Process
    • Loan Programs
    • Home Appraisal
    • Home Inspection
    • What to Expect at a Loan Closing: A Step-by-Step Guide
  • Apply
  • Reviews
    • Read My Reviews
    • Zillow Reviews
    • Leave a Review
  • Contact
You are here: Home / Archives for Accessory Dwelling Unit

Can You Finance a Home That Has a Second House on the Property?

October 20, 2026 by Coleen TeBockhorst

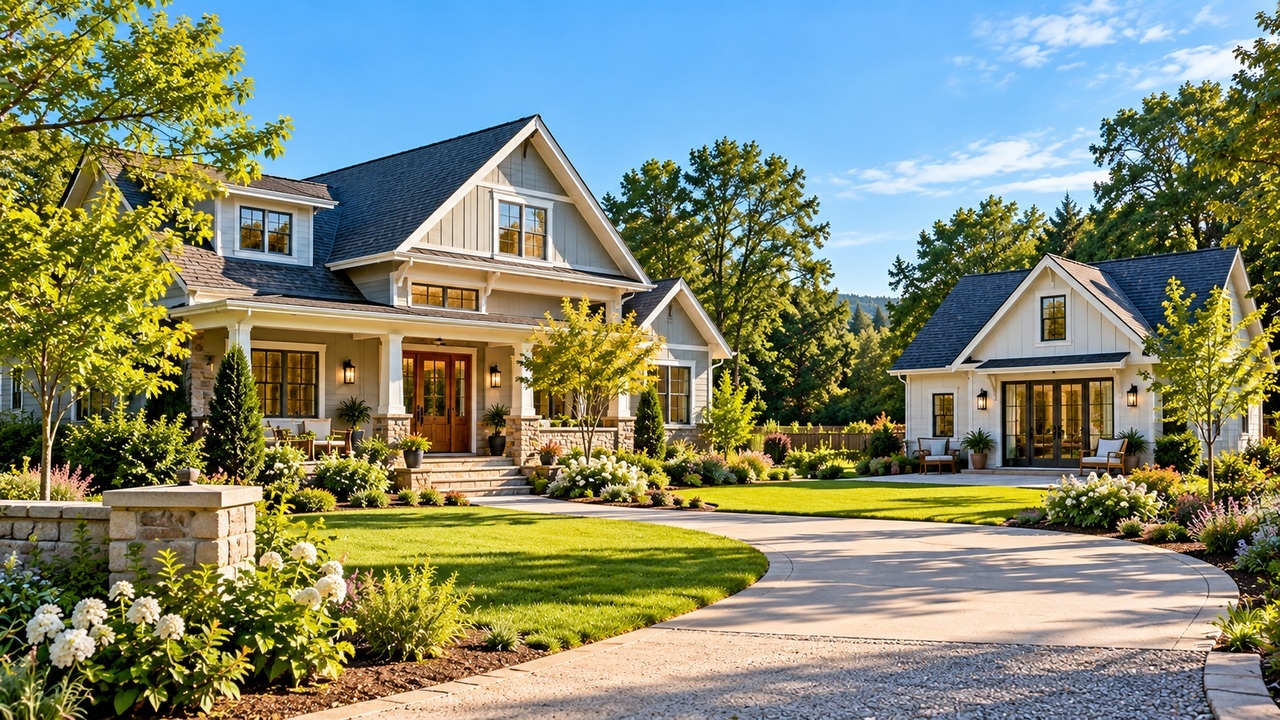
Finding a property with two houses can feel like discovering a bonus. The smaller home might provide space for relatives, visiting friends, or future rental income. Before making plans, however, buyers should understand that financing a property with two residences may be different from financing a typical single-family home.

Start With How the Property Is Classified

A detached second house is not always treated the same way as an accessory dwelling unit, commonly called an ADU. Local zoning rules, permits, separate utility connections, and the property’s legal description can influence how the additional structure is classified.

Some properties have a main residence and a smaller permitted ADU. Others contain two independent houses, perhaps built decades apart. A lender needs to know what is actually being purchased rather than relying on a listing description that calls the second structure a guesthouse.

Mortgage Programs Have Different Rules

Loan programs can have different standards for eligible property types, number of dwelling units, and acceptable accessory structures. A property that qualifies under one program may require a different approach under another.

The lender may review whether the homes are on the same legal parcel, whether both can be occupied independently, and whether the second structure has appropriate permits. If the property is considered a two-unit residence rather than a single-family home with an ADU, financing terms and documentation may change.

Appraisal Questions Matter, Too

The appraiser must evaluate the property in its current condition and determine how the additional residence contributes to market value. Finding comparable sales can be difficult when few nearby properties include two houses.

Buyers should not assume that the second home adds its full construction cost to the appraised value. Its legal status, size, condition, and usefulness to local buyers all matter.

Ask About Income and Future Use

A buyer may hope to rent the second residence to offset monthly expenses. Whether anticipated rental income can be considered for mortgage qualification depends on the loan program, documentation, and the buyer’s circumstances. Income should never be assumed before the lender confirms eligibility.

Before making an offer, ask for permits, floor plans, utility details, and records describing the second structure. Share them with your mortgage professional early. A property with two houses may offer valuable flexibility, but confirming how it will be financed is the best way to keep that opportunity from becoming a closing surprise.

Filed Under: Mortgage Tips Tagged With: Accessory Dwelling Unit, Mortgage Tips, Property Financing

Contact Coleen

Coleen Tebockhorst

Coleen TeBockhorst
coleen.tebockhorst@citywidehm.com

Senior Loan Officer

Call me! (612) 701-8512

NMLS #274205

Download My Mortgage eGuide today

CW Home Mortgage logo_White

Guaranteed Rate, Inc. DBA Citywide Home Mortgage

Categories

Our Location

10591 165th St. West
Lakeville MN, 55044

Connect With Me

This site is not authorized by the New York State Department of Financial Services. No mortgage loan applications for properties located in New York will be accepted through this site. Operating in the state of California as Guaranteed Rate, Inc. D/B/A Citywide Home Mortgage. If you are a California resident, please review our Privacy Policy to learn more about the categories and business purpose of personal information we may collect and your right to opt-out from the sale of personal information.

Applicant subject to credit and underwriting approval. Not all applicants will be approved for financing. Receipt of application does not represent an approval for financing or interest rate guarantee. Refinancing your mortgage may increase costs over the term of your loan. Restrictions may apply. All information provided in this publication is for informational and educational purposes only, and in no way is any of the content contained herein to be construed as financial, investment, or legal advice or instruction. Citywide Home Mortgage does not guarantee the quality, accuracy, completeness or timelines of the information in this publication. While efforts are made to verify the information provided, the information should not be assumed to be error-free. Some information in the publication may have been provided by third parties and has not necessarily been verified by Citywide Home Mortgage. Citywide Home Mortgage, its affiliates and subsidiaries do not assume any liability for the information contained herein, be it direct, indirect, consequential, special, or exemplary, or other damages whatsoever and howsoever caused, arising out of or in connection with the use of this publication or in reliance on the information, including any personal or pecuniary loss, whether the action is in contract, tort (including negligence) or other tortious action.

Coleen TeBockhorst NMLS ID: 274205 Copyright © 1998-2025 Guaranteed Rate, Inc. D/B/A Citywide Home Mortgage. All rights reserved.

For licensing information, go to: www.nmlsconsumeraccess.org.

NMLS License #2611 – 3940 N Ravenswood Chicago, IL 60613. (866) 508-5515. Equal Housing Lender.

Licensing | Privacy | Terms of Use

Copyright © 2026 · Powered by MySMARTblog

Copyright © 2026 · Genesis Sample Theme on Genesis Framework · WordPress · Log in