CTeBockhorst's Blog

The Mortgage and Real Estate Scoop

  • Home
  • About
  • Blog
  • Resources
    • Calculators
    • Download My eGuide Today!
    • First Time Buyer Tips
    • First Time Seller Tips
    • Loan Checklist
    • Loan Process
    • Loan Programs
    • Home Appraisal
    • Home Inspection
    • What to Expect at a Loan Closing: A Step-by-Step Guide
  • Apply
  • Reviews
    • Read My Reviews
    • Zillow Reviews
    • Leave a Review
  • Contact

Can You Get a Mortgage on a Home That Has Been Moved From Another Location?

October 16, 2026 by Coleen TeBockhorst

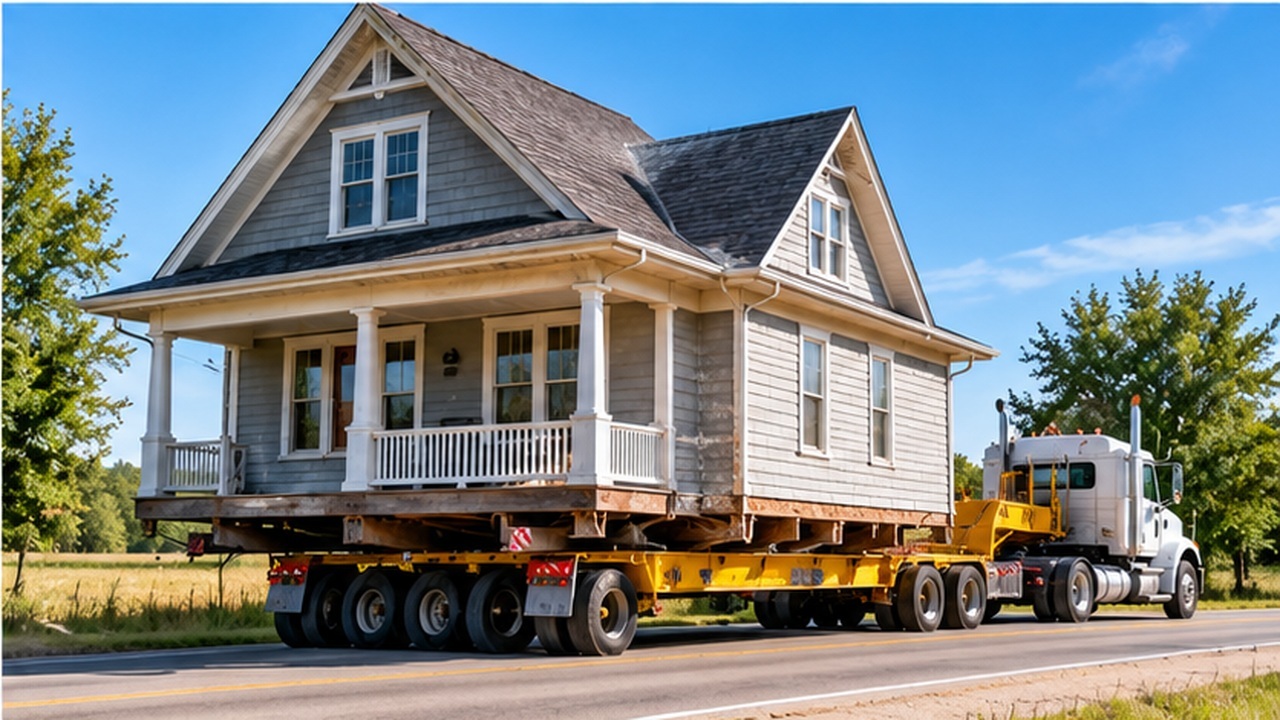
Most buyers assume that the home they are purchasing has always been located on its current property. However, some houses have been physically relocated from one location to another.

Whether a historic home was preserved by moving it or an existing structure was transported to a new lot, the property’s relocation history can create unique questions during the mortgage process.

Why Would Someone Move an Entire House?
Moving an existing home is more common than many people realize, particularly in areas where older houses are preserved or land is being redeveloped.

Instead of demolishing a structure, an owner may hire specialized contractors to lift the house, transport it, and place it on a new foundation.

In other situations, a house may be relocated to make room for construction or to preserve a building with historical significance.

Although the home may look completely normal once the project is finished, its relocation history can still be relevant when applying for financing.

The Foundation Can Be an Important Factor
When a home is moved, it generally must be placed on a suitable foundation at its new location.

Mortgage lenders and appraisers may need to evaluate whether the foundation and structure meet applicable requirements.

Depending on the property and loan program, additional documentation may be requested regarding the foundation, building permits, inspections, and completed relocation work.

Buyers should not assume that a home is automatically eligible for financing simply because it has been occupied since the move.

Property Records May Need Clarification
A relocated house may have a construction history that differs from the records associated with its current lot.

For example, the house may have been originally built decades earlier but moved to its present location much more recently.

The lender or appraiser may need to understand the difference between the original construction date and the date of relocation.

Permit records, certificates of occupancy, and other local documentation may help establish that the relocation was completed appropriately.

Missing or inconsistent information could lead to additional questions before the mortgage is approved.

Appraising a Relocated Home
Determining market value may also require careful consideration.

The appraiser evaluates the property in its current location and condition, rather than relying solely on what the structure may have been worth before it was moved.

Factors such as the foundation, overall condition, neighborhood, available comparable sales, and quality of completed work can influence the valuation.

A relocated house is not automatically worth less, but unusual property characteristics may require additional analysis.

What Buyers Should Do Before Applying
Buyers interested in a relocated home should ask when the move occurred, who performed the work, and what documentation is available.

They should also discuss the home’s history with their mortgage professional before committing to a financing timeline.

For buyers who appreciate unique or historic properties, a relocated home can offer considerable charm. The key is understanding the property’s history and confirming that its current condition and documentation support the intended mortgage financing.
Filed Under: Mortgage Tips Tagged With: Home Buying, Property Appraisal, Unique Homes

Why a Mortgage Lender May Question a Property With More Than One Parcel

October 15, 2026 by Coleen TeBockhorst

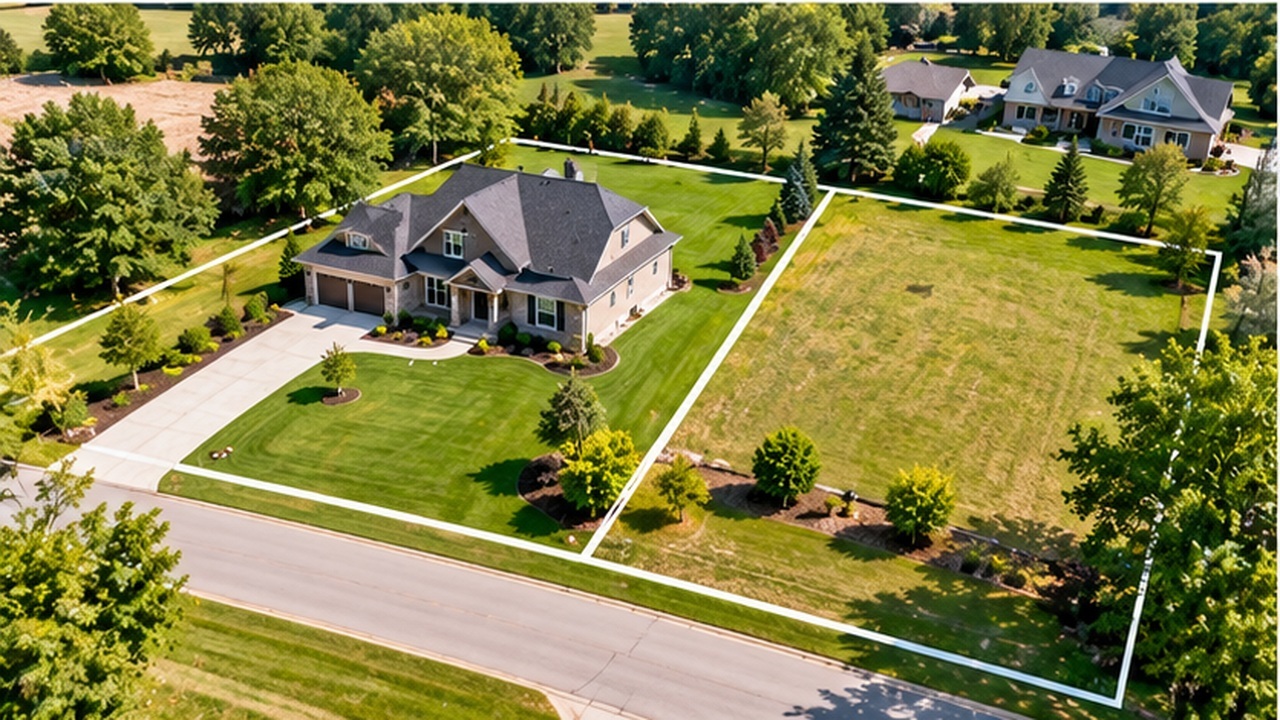
Imagine finding a beautiful home that comes with an extra piece of land next door. Perhaps the additional lot provides more privacy, a larger backyard, or room for future improvements.
While this may sound like an attractive bonus, purchasing a home that includes multiple parcels can introduce mortgage questions that buyers might not expect.

What Does It Mean to Have Multiple Parcels?
A parcel is a legally identified piece of land, typically assigned its own property identification number by the local taxing authority.

Most residential properties consist of one parcel containing the house and surrounding land. However, some homes are marketed with two or more parcels that are being sold together.

For example, a seller might own a house on one parcel and an adjoining vacant lot on another. The two properties may function as one large yard, even though they remain legally separate.

This distinction can matter when a buyer applies for mortgage financing.

Why the Property Configuration Matters
Mortgage lenders need to understand exactly what property will secure the loan.

When multiple parcels are involved, the lender may need to determine whether the parcels can be included in the same mortgage transaction and whether the arrangement meets the loan program’s requirements.

Questions may arise about whether the parcels are contiguous, how they are legally described, and whether the additional land has separate development potential.

The lender may also review whether any parcel contains improvements, structures, or uses that could affect residential financing eligibility.

Simply advertising two parcels together does not automatically mean they can be financed as one property.

The Appraisal May Require Additional Review
An appraisal evaluates the property being offered as collateral for the mortgage.

When a home includes additional land, the appraiser may need to determine how that land contributes to the property’s overall market value.

A separate parcel does not necessarily increase the appraised value by the amount a buyer might expect.

For example, an adjoining lot with limited access or development restrictions may have a different market contribution than a parcel that can support another residence.

Comparable sales and local market conditions help determine how the additional land is valued.

Consider the Long-Term Implications
Buyers should also understand whether the parcels receive separate property tax bills, have different zoning classifications, or carry individual restrictions.

If they eventually want to sell the vacant parcel separately, they may need lender approval or a partial release of the mortgage lien, along with any required local approvals.

Before making an offer, buyers should ask for the parcel identification numbers, legal descriptions, and available property records.

Owning extra land can provide valuable flexibility, but buyers should confirm how that land affects their financing and future plans. Understanding the legal and mortgage implications early can help prevent unexpected complications before closing.

Filed Under: Mortgage Tips Tagged With: Mortgage Education, Mortgage Tips, Property Parcels

What Happens When the Seller Has Not Paid Off a Home Improvement Loan?

October 14, 2026 by Coleen TeBockhorst

A newly installed roof, upgraded windows, or modern heating system can make a home more attractive to buyers. However, what happens when the seller is still making payments on those improvements?
Depending on how the work was financed, an outstanding home improvement loan could affect the sale, the title review, and even the buyer’s mortgage closing.

Not All Home Improvement Loans Work the Same Way
Homeowners finance improvements through several methods, including personal loans, home equity loans, contractor financing, and property-assessed financing programs.

Some financing arrangements are unsecured, meaning the loan is based primarily on the borrower’s credit rather than a claim against the property.

Others may be secured by the home, creating a lien or another obligation that must be addressed during the sale.

This distinction matters because an unpaid personal loan does not necessarily interfere with transferring ownership, while a loan secured by the property may need to be resolved before closing.

Why the Title Search Matters
During the mortgage process, a title search helps identify recorded liens, ownership issues, and other claims affecting the property.

If the seller financed a renovation through a loan secured by the home, the outstanding balance may appear in the title records.

The title company and closing professionals will determine what must be paid or released to provide the title required for the transaction.

In many cases, the seller can use proceeds from the sale to pay off an outstanding secured loan. However, the payoff amount and necessary documentation must be obtained before the transaction is finalized.

Special Considerations for Property-Assessed Financing
Some energy-efficient improvements are financed through Property Assessed Clean Energy, commonly called PACE, programs.

Unlike traditional personal loans, these obligations may be collected through property tax assessments.

Depending on the program and mortgage requirements, an outstanding PACE assessment can create additional questions about lien priority, payoff obligations, and whether the financing arrangement is acceptable.

Buyers should never assume that an obligation can simply remain attached to the property without affecting their mortgage.

What Buyers Should Ask Before Closing
If a seller advertises recently completed improvements, buyers can ask whether the work has been fully paid for.

They should also find out whether any financing arrangements, warranties, or service agreements are connected to the improvements.

The goal is not to discourage buyers from purchasing homes with recent renovations. Instead, it is to make sure that the financial obligations associated with those improvements are clearly understood.

A beautiful renovation can add appeal to a property, but the paperwork behind it matters too. Addressing outstanding financing early helps protect the transaction from unexpected delays and gives buyers greater confidence about what they are purchasing.

Filed Under: Mortgage Tips Tagged With: Home Improvement Loan, Mortgage Education, Mortgage Tips

Why a Home With a Shared Septic System Can Complicate Mortgage Financing

October 13, 2026 by Coleen TeBockhorst

A home can look perfect during a showing, but certain features of the property may create questions when it comes time to secure a mortgage. One situation buyers may not anticipate is purchasing a home that shares a septic system with another property.
While shared systems can function effectively, they may require additional documentation and review before financing can move forward.

Understanding How a Shared Septic System Works
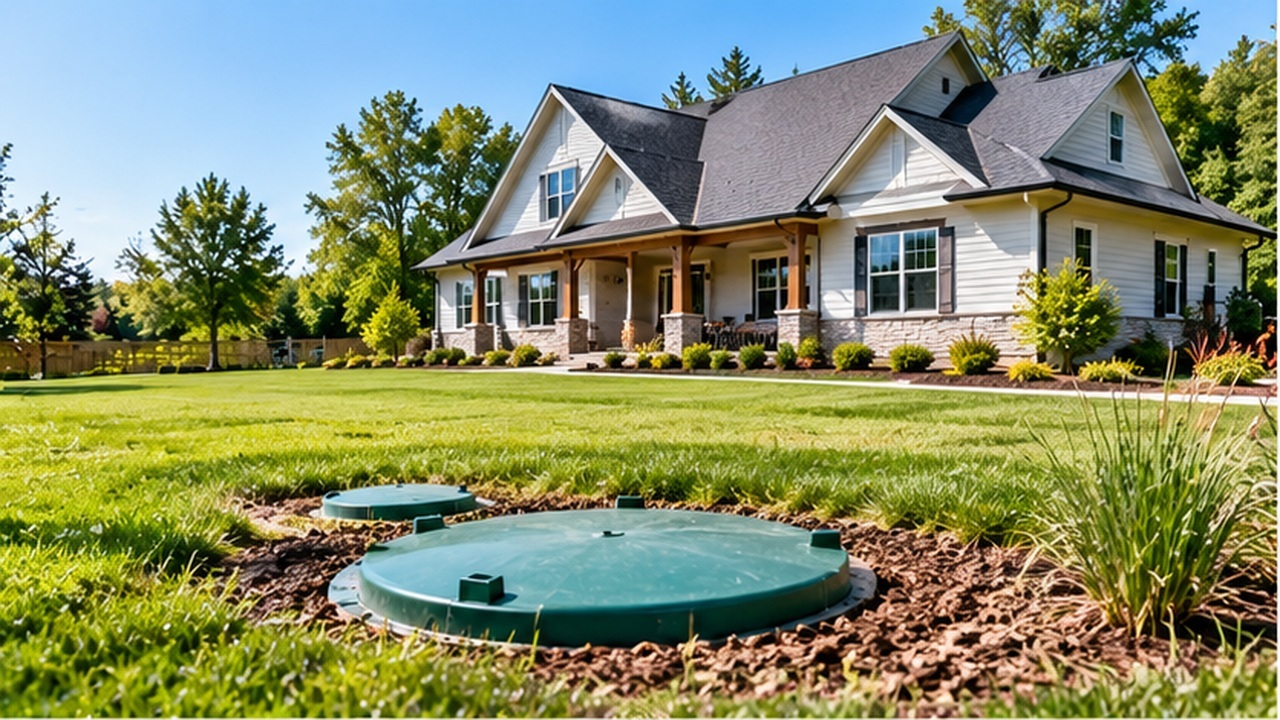
Most buyers are familiar with homes that connect to a public sewer system or have their own private septic tank. However, some properties share a wastewater treatment system with one or more neighboring homes.

This arrangement may have been established when the properties were originally developed or when land was divided into separate parcels. Although each home has its own plumbing, wastewater from multiple properties may flow into a common treatment system.

The important question is not simply whether the system works. Buyers also need to understand who owns it, who maintains it, and how responsibilities are divided.

Why Lenders May Request Additional Information
Mortgage lenders evaluate more than the buyer’s income and credit history. They also review the property to determine whether it meets the requirements of the loan program.

When a septic system is shared, the lender may need documentation establishing the legal right to use the system. Depending on the loan program and circumstances, this could include recorded agreements, easements, maintenance provisions, or other property records.

The lender may also need confirmation that the system meets applicable health and safety requirements.

Requirements vary by mortgage program, so buyers should not assume that every shared system will create the same financing challenges.

Who Pays When Something Goes Wrong?

A shared septic system creates an important financial question: What happens when repairs are needed?

If the tank requires pumping, a drain field fails, or the system needs replacement, the cost may be shared among participating property owners.

A written agreement can help establish how expenses are divided, who arranges maintenance, and what happens if one owner refuses to contribute.

Without clear arrangements, buyers could face unexpected disagreements or expenses after purchasing the property.

Ask Questions Before Making an Offer

Buyers considering a home with a shared septic system should request available agreements, maintenance records, inspection information, and details about participating properties.

They should also discuss the arrangement with their mortgage professional early in the process rather than waiting until underwriting begins.

A shared septic system does not automatically prevent someone from obtaining a mortgage. However, understanding the property’s legal and maintenance arrangements before making a purchase can help buyers avoid surprises, evaluate future responsibilities, and move through the financing process with greater confidence.

Filed Under: Mortgage Tips Tagged With: Home Buyer Tips, Mortgage Financing, Septic Systems

What’s Ahead For Mortgage Rates This Week – October 12th, 2026

October 12, 2026 by Coleen TeBockhorst

The FOMC Minutes and Consumer Sentiment report were the most impactful calendar items last week, further reinforcing the Federal Reserve’s resolve to bring inflation down to its 2% target rate.

While there is considerable speculation about another rate increase, recent analyst expectations suggest that the Fed will hold rates at their current level for some time. The Consumer Sentiment report showed a slight increase, largely driven by moderating gas prices, which have helped provide consumers with some relief.

Consumer Sentiment Report
The University of Michigan Consumer Sentiment index was revised higher to 49.5 in June 2026, up from a preliminary reading of 48.9, although it remained slightly below forecasts of 50. Still, sentiment improved from 44.8 in May, the lowest level on record, supported in part by a moderation in gasoline prices. The expectations gauge was at 50.7, the highest in three months, compared to 49.3 in the initial estimate, as consumers’ worries over long-term consequences of the Iran conflict appear to be easing.

FOMC Minutes
The Fed chief reiterated that the central bank will no longer provide traditional forward guidance on future interest-rate decisions, signaling a shift in its communication approach. Inflation risks have eased in recent weeks, but the US central bank remains committed to restoring inflation to its 2% target, Federal Reserve Chair Kevin Warsh said at the ECB’s Sintra Forum. Warsh stressed that delivering price stability remains the Fed’s primary objective, while underscoring policymakers’ independence in setting monetary policy and rejecting any suggestion that political pressure would influence their decisions.

Primary Mortgage Market Survey Index

  • 15-Year FRM rates saw an increase of 0.13%, bringing the current rate to 6.73%.
  • 30-Year FRM rates saw an increase of 0.12%, bringing the current rate to 7.40%.

MND Rate Index

  • 30-Year FHA rates saw a decrease of -0.05%, with current the rate at 7.15%.
  • 30-Year VA rates saw a decrease of -0.04%, with current the rate at 7.17%.

Jobless Claims
Initial Claims were reported to be 197,000 compared to the expected claims of 200,000. The previous week landed at 199,000.

What’s Ahead
Next week brings a full economic calendar, including the CPI and PPI inflation data releases, retail sales, and the increasingly impactful 5- and 10-year Treasury note auctions.

Filed Under: Financial Reports Tagged With: Financial Report, Jobless Claims, Mortgage Rates

Why Buying a Home From a Family Member Can Make the Mortgage More Complicated

October 9, 2026 by Coleen TeBockhorst

Buying a home from a parent, grandparent, sibling, or another relative may seem easier than purchasing from a stranger. You already know the seller, may know the property’s history, and might even agree on a price without extensive negotiations.
But the family relationship can introduce mortgage considerations that are different from those in a typical purchase between unrelated parties.

The Relationship Matters
A transaction between people with an existing relationship may be considered differently from a traditional arm’s-length sale.

That does not mean family transactions are prohibited. It means the lender may need to understand the relationship between the buyer and seller and review the structure of the transaction accordingly.

Being clear about the relationship from the beginning is important.

A Gift of Equity May Be Possible
One feature sometimes associated with family transactions is a gift of equity.

Instead of giving the buyer cash for a down payment, an eligible family member selling the property may be able to provide a portion of the home’s equity as a gift within applicable mortgage guidelines.

How a gift of equity can be used depends on the mortgage program and transaction, and documentation requirements can apply.

Buyers should discuss the proposed structure before agreeing on final numbers.

The Appraisal Still Matters
A family member may be willing to sell a property for less than they believe it is worth, but the agreed price does not eliminate the appraisal process when an appraisal is required.

The property still needs to be evaluated independently for the mortgage transaction.

That can become particularly important when a gift of equity or below-market sale is involved.

Treat It Like a Financial Transaction
Family relationships can make buyers and sellers more comfortable relying on verbal agreements.

A home purchase is too significant for assumptions.

Make sure the purchase price, credits, responsibilities, timelines, and other terms are properly documented through the appropriate transaction paperwork.

Buying a relative’s home can create an opportunity that would never reach the open market. It can also allow a property with family history to remain within the family.

The key is to remember that familiarity between buyer and seller does not eliminate the mortgage process.

Discuss the family relationship, proposed purchase price, and any planned gift of equity with your mortgage and real estate professionals early so the transaction can be structured correctly from the beginning.

Filed Under: Mortgage Tips Tagged With: Gift Of Equity, Home Buyer Tips, Home Buying

What Happens to Your Mortgage When the Home Has an Unfinished Addition?

October 8, 2026 by Coleen TeBockhorst

You find a home you love, but there is one unusual feature. Maybe the previous owner started adding a bedroom and never finished it. Perhaps a bathroom is partially remodeled, a garage conversion is incomplete, or a new section of the house is still visibly under construction.
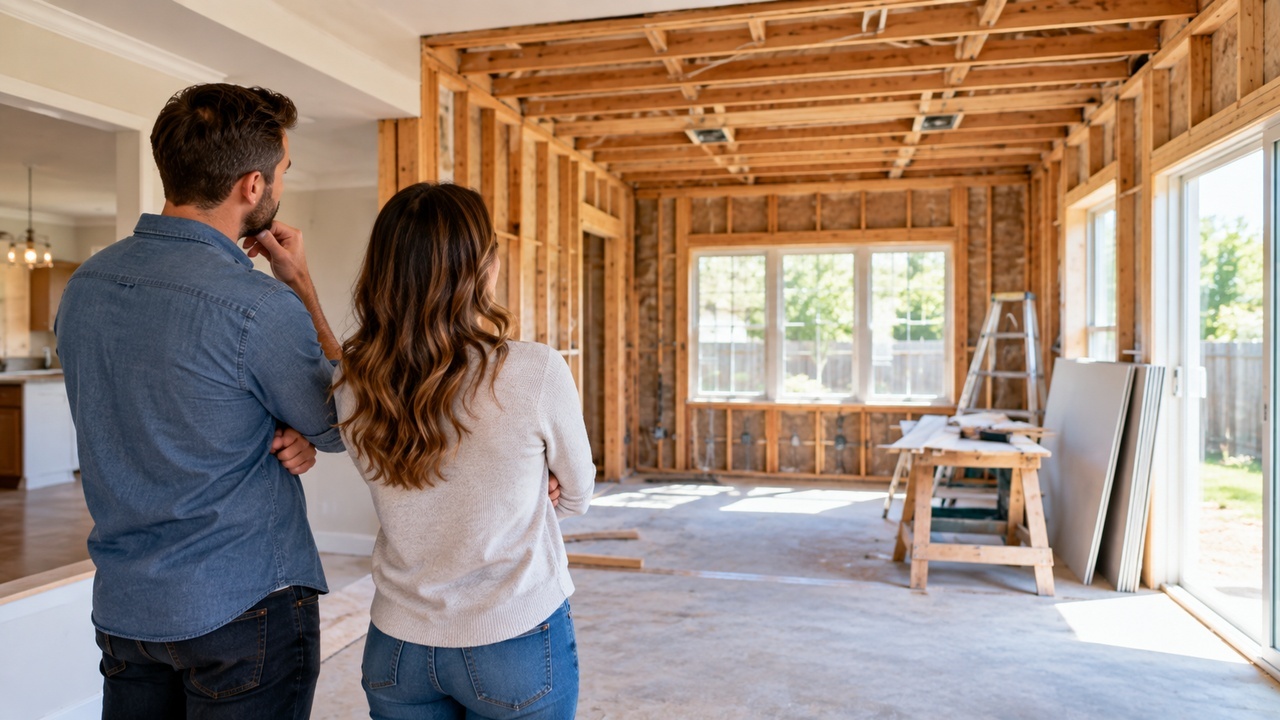
Buyers may see opportunity in unfinished space, but a mortgage lender may need to evaluate the property as it exists today.

Financing Is Based on the Current Property
It is easy to walk through an unfinished addition and imagine what it could become.

The mortgage transaction, however, generally has to consider the property’s current condition rather than simply the buyer’s plans for completing it later.

The appraiser may need to identify unfinished areas and determine how they affect the property being valued.

Not All Unfinished Projects Are Equal
Missing cosmetic finishes are different from major incomplete construction.

A room awaiting paint or updated flooring presents a different situation than an addition with exposed framing, unfinished electrical work, missing plumbing fixtures, or other incomplete components.

The extent and type of unfinished work can influence what questions need to be answered.

Permits Can Become Part of the Conversation
An addition also raises another important question: Was the work properly permitted when required?

Buyers should understand what was added, who performed the work, and what information is available through the seller or applicable local records.

An attractive partially completed space should not automatically be assumed to be recognized living area.

Do Not Assume You Can Finish It After Closing
Buyers sometimes approach an unfinished project with a simple plan: purchase the property now and complete everything later.

That may ultimately be possible, but it should not be assumed before the financing has been reviewed.

Depending on the property condition and mortgage program, incomplete work could require additional evaluation or affect available financing options.

If you are seriously considering a home with an unfinished addition, show the details to your mortgage professional as early as possible. Photos, listing information, disclosures, and information about the work can help start the conversation.

A half-finished room may look like an opportunity to create exactly what you want.

Just remember that before you can finish the project as the homeowner, you first have to successfully purchase the property in its present condition.

Filed Under: Mortgage Tips Tagged With: Home Buying, Mortgage Education, Mortgage Tips

Why the Source of Your Down Payment Can Matter as Much as the Amount

October 7, 2026 by Coleen TeBockhorst

You have calculated your down payment and know exactly how much money you plan to bring to the purchase. That is an important step, but there is another question buyers sometimes overlook: Where is that money actually coming from?
A $40,000 down payment sitting in one savings account can create a different planning process than $40,000 being assembled from several different financial sources.

Your Down Payment May Come From Several Places
Not every buyer saves a down payment in one traditional bank account.

Funds might come from checking or savings, investments, proceeds from selling an asset, an eligible gift, or other permitted sources. Some buyers may also have money connected to a business or another type of account.

Each source can have different considerations, so knowing where the money will come from before you need it can simplify the mortgage process.

Investments May Require Planning
If part of your down payment is invested, consider what must happen before those funds become available for closing.

Selling investments may require time for transactions to settle and funds to transfer. There may also be financial or tax considerations outside the mortgage itself that you want to discuss with the appropriate professional.

The important point is not to wait until the last minute to determine how you will access the money.

Gift Funds Are Not Simply Extra Cash
Eligible gift funds can help some buyers with a home purchase, but mortgage programs can have rules regarding who may provide the gift and how it must be documented.

If someone has offered to help with your purchase, discuss the plan before money changes hands.
Knowing the requirements in advance can prevent unnecessary confusion later.

Build Your Down Payment Plan Early
Before making an offer, identify the accounts and sources you expect to use. Then ask how those funds should be handled and what documentation may be required.

This is especially useful if your down payment will come from several places rather than one established account.

Having enough money is obviously essential, but mortgage planning involves more than reaching a target dollar amount.

Understanding where your down payment will come from, how quickly the funds can become available, and what requirements apply to each source can help make the financial side of closing much more predictable.
Your down payment should not simply be a number. It should be a plan.

Filed Under: Home Buyer Tips Tagged With: Home Buyer Tips, Mortgage Education, Mortgage Tips

Why Your Mortgage Approval Can Change When the Home Has an Accessory Dwelling Unit

October 6, 2026 by Coleen TeBockhorst

An accessory dwelling unit can make a property especially appealing. A detached guest house, converted garage, basement apartment, or backyard unit might provide space for relatives, a home office, or potential rental income.
But when you are financing the purchase, that additional living space can introduce questions that would not necessarily exist with a more traditional single-family home.

The Property Has to Be Evaluated Too
Mortgage approval is not based solely on the borrower’s income, credit, assets, and debts. The property securing the mortgage also has to meet applicable requirements.

When an ADU is present, the lender and appraiser may need to understand exactly what it is and how it relates to the primary residence.

Is it a separate structure? Does it have its own kitchen? Was an existing part of the property converted? These details can help determine how the property is evaluated.

Permits and Property Records May Matter
One important question is whether the additional living space was legally created and how it is reflected in available property records.

Buyers should not assume that a finished structure is automatically recognized as permitted living space simply because it looks professionally completed.

If something about the ADU is unclear, additional documentation or investigation may be needed.

Rental Income Is a Separate Question
Buyers sometimes see an ADU and immediately calculate how much rental income it could generate.

That potential income may be useful to your personal budget, but do not automatically assume it can be counted toward mortgage qualification.

Whether rental income from an ADU can be considered, and how much can be used, depends on the mortgage program, documentation, appraisal, occupancy plans, and other requirements.

Ask Before Building Your Budget Around It
If an ADU is an important reason you are considering a property, discuss it with your mortgage professional early. Explain how you intend to use the space and whether you are relying on anticipated rental income as part of your financial plan.

You may also want to ask your real estate professional about permits and available property information. An ADU can be an excellent feature, but it makes the property more than simply a house with an extra room.

Before assuming the additional space will strengthen your mortgage application or generate income immediately, understand how it will be treated in the transaction. That can help you evaluate the property based on what is actually possible rather than what you hope the extra space will provide.

Filed Under: Home Buyer Tips Tagged With: Home Buyer Tips, Mortgage Education, Mortgage Tips

What’s Ahead For Mortgage Rates This Week – October 5th, 2026

October 5, 2026 by Coleen TeBockhorst

While the Core PCE Index came in at 3.0%, below the expected 3.3%, overall inflation remains well above the Federal Reserve’s 2% target.

With inflation still running above the Federal Reserve’s target, there remains room for rates to stay elevated or potentially increase over the next several rate decisions if the Fed remains focused on restraining inflation.

The JOLTS job openings report has also revealed a larger-than-expected gap. Job growth across the board has been slowing, with growth concentrated in only a handful of sectors.

The nonfarm payroll figures have also come in well below expectations, while the unemployment rate remains elevated on a year-over-year basis when compared with historical levels over the past decade.

PCE Index
PCE increased 3.4% from a year earlier, while core PCE—which excludes food and energy—increased 3.0%. Both were still above the Fed’s 2% target. 

JOLTs Job Openings
Job openings fell to 7.08 million in August, down from a revised 7.34 million in July and below economists’ expectations of 7.23 million. The job openings rate declined to 4.3%, signaling continued cooling in labor demand.

Non-farm Payroll
Average hourly earnings increased 0.1% in September to $37.81, bringing annual wage growth to 3.0%. Wage growth slowed from 3.1% in August, providing a more favorable signal for inflation and interest rates.

Primary Mortgage Market Survey Index

  • 15-Year FRM rates saw an increase of 0.18%, bringing the current rate to 6.60%.
  • 30-Year FRM rates saw an increase of 0.25%, bringing the current rate to 7.28%.

MND Rate Index

  • 30-Year FHA rates saw an increase of 0.05%, with current rate at 7.20%.
  • 30-Year VA rates saw an increase of 0.04%, with current rate at 7.21%.

Jobless Claims
Initial Claims were reported to be 197,000 compared to the expected claims of 200,000. The previous week landed at 202,000.

What’s Ahead
The following week will be relatively light, with the Consumer Sentiment Report being the largest release, alongside major bill and bond auctions. There are also a couple of key speeches from Federal Reserve members that could provide forward guidance on future rate decisions.

Filed Under: Financial Reports Tagged With: Financial Report, Jobless Claims, Mortgage Rates

Next Page »

Contact Coleen

Coleen Tebockhorst

Coleen TeBockhorst
coleen.tebockhorst@citywidehm.com

Senior Loan Officer

Call me! (612) 701-8512

NMLS #274205

Download My Mortgage eGuide today

CW Home Mortgage logo_White

Guaranteed Rate, Inc. DBA Citywide Home Mortgage

Categories

Our Location

10591 165th St. West
Lakeville MN, 55044

Connect With Me

This site is not authorized by the New York State Department of Financial Services. No mortgage loan applications for properties located in New York will be accepted through this site. Operating in the state of California as Guaranteed Rate, Inc. D/B/A Citywide Home Mortgage. If you are a California resident, please review our Privacy Policy to learn more about the categories and business purpose of personal information we may collect and your right to opt-out from the sale of personal information.

Applicant subject to credit and underwriting approval. Not all applicants will be approved for financing. Receipt of application does not represent an approval for financing or interest rate guarantee. Refinancing your mortgage may increase costs over the term of your loan. Restrictions may apply. All information provided in this publication is for informational and educational purposes only, and in no way is any of the content contained herein to be construed as financial, investment, or legal advice or instruction. Citywide Home Mortgage does not guarantee the quality, accuracy, completeness or timelines of the information in this publication. While efforts are made to verify the information provided, the information should not be assumed to be error-free. Some information in the publication may have been provided by third parties and has not necessarily been verified by Citywide Home Mortgage. Citywide Home Mortgage, its affiliates and subsidiaries do not assume any liability for the information contained herein, be it direct, indirect, consequential, special, or exemplary, or other damages whatsoever and howsoever caused, arising out of or in connection with the use of this publication or in reliance on the information, including any personal or pecuniary loss, whether the action is in contract, tort (including negligence) or other tortious action.

Coleen TeBockhorst NMLS ID: 274205 Copyright © 1998-2025 Guaranteed Rate, Inc. D/B/A Citywide Home Mortgage. All rights reserved.

For licensing information, go to: www.nmlsconsumeraccess.org.

NMLS License #2611 – 3940 N Ravenswood Chicago, IL 60613. (866) 508-5515. Equal Housing Lender.

Licensing | Privacy | Terms of Use

Copyright © 2026 · Powered by MySMARTblog

Copyright © 2026 · Genesis Sample Theme on Genesis Framework · WordPress · Log in