CTeBockhorst's Blog

The Mortgage and Real Estate Scoop

  • Home
  • About
  • Blog
  • Resources
    • Calculators
    • Download My eGuide Today!
    • First Time Buyer Tips
    • First Time Seller Tips
    • Loan Checklist
    • Loan Process
    • Loan Programs
    • Home Appraisal
    • Home Inspection
    • What to Expect at a Loan Closing: A Step-by-Step Guide
  • Apply
  • Reviews
    • Read My Reviews
    • Zillow Reviews
    • Leave a Review
  • Contact

Why Cash Reserves Can Matter As Much As Your Down Payment

June 10, 2026 by Coleen TeBockhorst

Many buyers focus heavily on saving for the down payment. That is important, but it is not the only money that matters when buying a home. Cash reserves can be just as important because they help protect you after closing. A strong home purchase plan should include both the money needed to buy the home and the money needed to feel secure once you own it.

What Reserves Mean
Cash reserves are funds left over after your down payment and closing costs are paid. They may be in savings, checking, or other eligible accounts depending on the loan program. These funds show that you have a cushion beyond the transaction itself. They can also help you handle the first months of homeownership with more confidence.

Homeownership Comes With Surprises
Even a well-inspected home can come with unexpected costs. Appliances break, utilities may be higher than expected, furniture may be needed, and small repairs can add up quickly. Moving itself can also cost more than buyers expect. Having reserves can make those expenses less stressful.

A Bigger Down Payment Is Not Always Better
Some buyers want to put every available dollar into the down payment. That may lower the loan amount or monthly payment, but it can leave them with little cash afterward. In some cases, keeping more money in reserve may create a healthier financial position than using all available funds upfront.

Loan Programs May View Reserves Differently
Some mortgage programs require reserves, while others may not. Even when reserves are not required, they can still strengthen your overall comfort level. Your mortgage originator can help you compare scenarios with different down payment amounts and remaining cash after closing.

Confidence After Closing Matters
Buying a home should not leave you feeling financially empty. The goal is to get approved and close. The goal is to move in with enough stability to handle normal life. A good mortgage plan should account for your payment, your savings, and your ability to manage the unexpected.

Your down payment helps you buy the home. Your reserves help you keep breathing after you get the keys. Both deserve attention before you make an offer.
Filed Under: Mortgage Tips Tagged With: Down Payment, Home Buyer Education, Mortgage Tips

What Buyers Should Know About Rate Quotes Before Comparing Lenders

June 9, 2026 by Coleen TeBockhorst

Comparing mortgage rates can feel simple at first. A buyer asks a few lenders for a rate, looks for the lowest number, and assumes that is the best option. But rate quotes can be more complicated than they appear. To compare lenders fairly, you need to know what is behind the quote.
Timing Matters
Mortgage rates can change daily, and sometimes more than once in a day. A quote from Monday morning may not compare fairly to a quote from Wednesday afternoon. Market conditions, timing, and lock status can all affect the number. When comparing options, try to gather quotes around the same time.

Ask About Points and Fees
A lower rate may come with discount points or additional costs. Points are fees paid upfront to lower the interest rate. That may make sense for some buyers, but it is not automatically the right choice for everyone. A rate quote should be reviewed along with lender fees, points, credits, and total estimated closing costs.

Know the Loan Assumptions
A rate quote depends on details such as loan amount, credit score, down payment, property type, occupancy, loan program, and lock period. If 2 lenders are using different assumptions, the quotes may not be equal. Make sure each quote is based on the same scenario so you are comparing the same loan structure.

Look at the Annual Percentage Rate Carefully
The annual percentage rate can help show the broader cost of borrowing because it includes certain loan costs, but it is not the same as the interest rate. It can be useful, but buyers should still review the full estimate and ask questions about what is included.

Service Has Value Too
The lowest quoted rate may not matter if the process is disorganized, communication is poor, or the loan is not ready on time. A mortgage is more than a number. You also want clear communication, realistic guidance, and a lender who helps you understand your options.

Before choosing a lender, compare the full picture. Look at rate, costs, loan terms, timing, service, and confidence in execution. The best mortgage quote is not always the lowest number on a screen. It is the one you understand clearly and trust to get you to closing.

Filed Under: Mortgage Tips Tagged With: Home Buyer Education, Mortgage Rates, Mortgage Tips

What’s Ahead For Mortgage Rates This Week – June 8th, 2026

June 8, 2026 by Coleen TeBockhorst

Unemployment data has been released, revealing an interesting trend: different demographic groups are facing varying, and in some cases significantly higher, levels of unemployment.

While the overall unemployment rate has remained steady at 4.3%, some demographics are experiencing substantially higher unemployment within their respective fields. This comes alongside hourly wage reports which have met the expected growth level for this month.

Historically, however, wage growth has been offset by inflation rising at a much faster pace. As a result, many Americans have found the cost of living increasingly difficult to manage as they attempt to economize and cope with rising fuel, energy, and consumer goods costs.

Unemployment Reports
Unemployment rates for every major group: The lowest is 3.2%, the highest 14.7% The U.S. unemployment rate stayed at 4.3% in May for the third month in a row, but different groups face different challenges finding a job or keeping one. 

U.S. Hourly Wages
Inflation surged throughout the U.S. economy in late April and May, forcing Americans to try to quickly adjust to a new phase of reduced spending power, according to the Federal Reserve’s latest report on economic conditions around the country, known as the “beige book.” Affordability pressures due to higher energy prices from the war with Iran led to a widening gap between spending across income groups.

Primary Mortgage Market Survey Index

  • 15-Year FRM rates saw a decrease of -0.02%, bringing the current rate to 5.79%.
  • 30-Year FRM rates saw a decrease of -0.05%, bringing the current rate to 6.48%.

MND Rate Index

  • 30-Year FHA rates saw a 0.08% increase, with current rate at 6.18%.
  • 30-Year VA rates saw a 0.07% increase, with current rate at 6.19%.

Jobless Claims
Initial Claims were reported to be 225,000 compared to the expected claims of 215,000. The previous week landed at 215,000.

What’s Ahead
Attention now turns to the upcoming CPI and PPI reports, which will offer fresh insight into inflation trends.

Filed Under: Financial Reports Tagged With: Financial Report, Jobless Claims, Mortgage Rates

Why Your Credit Score Is Only One Piece Of The Mortgage Picture

June 5, 2026 by Coleen TeBockhorst

Many buyers worry about their credit score before applying for a mortgage. That makes sense because credit can affect loan options, interest rate, and overall approval strength. But your credit score is only 1 piece of the mortgage picture. A strong loan file includes several parts working together.
Credit Matters, But It Is Not Everything
Your credit score helps lenders understand how you have managed debt in the past. It can influence pricing and program options, but it does not tell the full story. A buyer with a strong score may still need to document income, manage debt levels, and show enough funds for closing. A buyer with a lower score may still have options depending on the rest of the file.

Income and Stability Count
Lenders also look at your ability to repay the loan. That means income, employment history, documentation, and consistency matter. If your income changes month to month, includes bonuses, commissions, self-employment earnings, or multiple sources, the review may take more detail. Your mortgage originator can help you understand what documentation may be needed.

Debt Plays a Role
Your monthly debt obligations are important too. Credit cards, car loans, student loans, personal loans, and other payments can affect how much home fits your budget and approval. Sometimes paying attention to debt strategy before applying can make a meaningful difference.

Savings Can Strengthen the File
Cash reserves, down payment funds, and closing cost funds also matter. Having money left after closing can help show stability. It can also help you feel more prepared for moving costs, repairs, furniture, and the normal surprises that come with homeownership.

Build the Full Picture
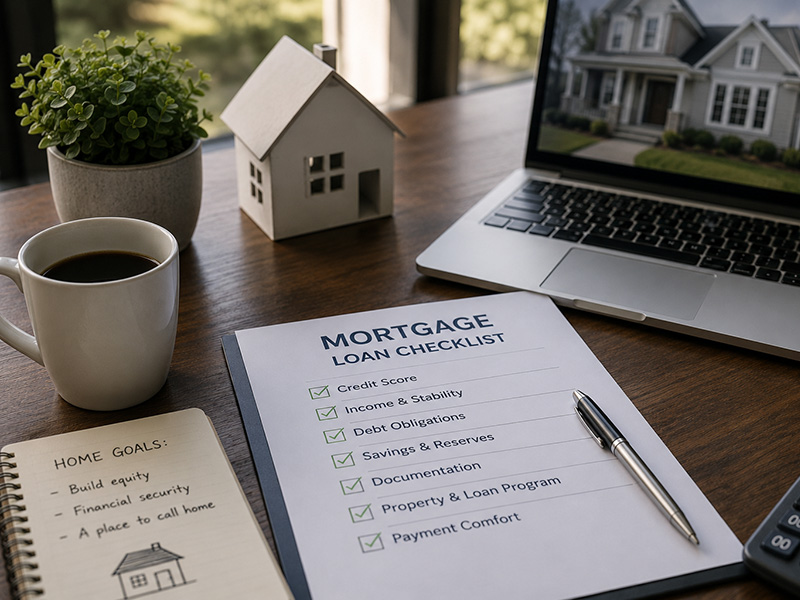
The goal is not to focus on 1 number and ignore everything else. A mortgage approval looks at the full financial profile. Credit is important, but income, debt, savings, documentation, property type, loan program, and payment comfort all work together.

If you are thinking about buying a home, do not assume your credit score alone tells you what is possible. A conversation with a mortgage originator can help you understand your full picture and what steps may make the biggest difference.

Filed Under: Mortgage Tips Tagged With: Home Buyer Tips, Loan Approval, Mortgage Education

Why Your Monthly Payment Matters More Than Your Purchase Price

June 4, 2026 by Coleen TeBockhorst

Buyers often focus on the purchase price first. It is easy to compare homes by listing price and assume that a lower price automatically means a better fit. But when you are financing a home, the amount that affects your everyday life most is the monthly payment. That payment is what shows up in your budget month after month.
Look at the Full Payment
Your mortgage payment is more than principal and interest. It may also include property taxes, homeowners  insurance, mortgage insurance, homeowners association dues, and escrow changes over time. 2 homes with the same purchase price can have very different monthly payments depending on taxes, insurance, loan type, and location.

Think About Monthly Comfort
A home should fit your life, not just your approval amount. The monthly payment should leave room for groceries, utilities, savings, repairs, travel, childcare, transportation, and unexpected expenses. A purchase price may look manageable on paper, but the payment is what determines whether the home feels comfortable after closing.

Compare More Than Price Tags
Sometimes a higher-priced home may have lower taxes or fewer monthly costs. Sometimes a lower-priced home may need repairs, higher insurance, or extra dues that change the real cost. That is why looking only at the purchase price can be misleading. The better question is what the home will cost you each month.

Plan for the Future
Your payment should also support your long-term goals. If the payment leaves no room to save, handle repairs, or enjoy life, the home may create stress even if you were approved for it. A slightly lower payment can provide breathing room and help you feel more stable as a homeowner.

Buy With the Right Number in Mind
Before you fall in love with a price, understand the payment. Ask your mortgage originator to walk through different scenarios so you can see how taxes, insurance, down payment, rate, and loan structure affect the monthly number.

The best home is not always the one with the lowest purchase price or the highest approval amount. It is the one with a payment that fits your real life, supports your goals, and lets you enjoy homeownership with confidence.

Filed Under: Mortgage Tips Tagged With: Home Buyer Education, Mortgage Tips, Smart Home Buying

The Mortgage Questions Buyers Are Afraid to Ask

June 3, 2026 by Coleen TeBockhorst

Buying a home can make even confident people feel unsure. There are new terms, large numbers, legal documents, deadlines, and decisions that seem to carry long-term consequences. Many buyers have questions, but they hesitate to ask because they do not want to sound inexperienced. The truth is that mortgage questions are not embarrassing. They are necessary.
Ask for Plain Language

One question buyers often avoid is, “Can you explain this again in plain language?”

Mortgage terms can be technical. Words like escrow, amortization, points, prepaid items, reserves, underwriting, and debt-to-income ratio may be used casually by professionals, but they are not everyday language for most consumers. A good mortgage professional should be willing to explain the same concept more than once and in a way that makes sense.

Understand Payment Changes

Another common question is, “Why did my payment change?”

Payments can shift during the process because of taxes, insurance estimates, rate changes, loan program details, homeowners association dues, or updated information. Asking about the change is not rude. It is responsible. You should understand what you are agreeing to before closing.

Talk About Cash to Close Early

Buyers may also be afraid to ask, “What happens if I do not have enough cash to close?”

This is exactly the kind of question that should be discussed early. There may be options, such as adjusting the loan structure, asking for seller credits, reviewing gift funds, or changing the timeline. Waiting until the last minute creates more stress.

Readiness Is More Than Approval

Some buyers hesitate to ask whether they are truly ready. They may have an approval but still wonder if buying is the right move. That is a valid conversation. Mortgage readiness is not just about qualifying. It is also about budget comfort, job stability, savings, future plans, and confidence.

Know What Could Go Wrong

Another important question is, “What could go wrong from here?”

This does not mean expecting failure. It means understanding the rules. New debt, job changes, undocumented deposits, missed payments, or major financial moves can affect a mortgage file. Knowing what to avoid helps protect the approval.

Ask About Tradeoffs

Buyers should also feel free to ask about tradeoffs. What is the benefit of putting more down? What is the downside of using discount points? How does mortgage insurance work? Is this loan program still the best fit if my plans change?

These questions help turn the mortgage from a mystery into a strategy.

Confidence Comes From Clarity

No one should feel pressured to nod along during one of the biggest financial decisions of their life. Questions are not a sign that you are unprepared. They are a sign that you are paying attention. The more you understand, the more confident you can feel when you sign the closing documents.

The buyers who ask questions are often the ones who make the strongest decisions. Curiosity can save money, reduce stress, and prevent surprises. In the mortgage process, silence is rarely the smartest strategy.

Filed Under: Mortgage Tips Tagged With: Home Buyer Education, Monthly Payment, Mortgage Tips

What Your Bank Statements Quietly Say About You

June 2, 2026 by Coleen TeBockhorst

When you apply for a mortgage, your bank statements are more than a record of deposits and withdrawals. They tell a story about how money moves through your life. Lenders review them to verify funds, identify large deposits, confirm reserves, and understand whether the money used for closing is properly documented. But for buyers, bank statements can also be a useful mirror.
Your Money Patterns Matter 
Your statements may reveal patterns that are easy to ignore day to day. Frequent transfers, overdrafts, large unexplained deposits, subscription charges, cash app activity, and irregular spending can all make the mortgage process more complicated if they are not understood ahead of time. This does not mean you need perfect finances to buy a home. It means clarity matters.

Large Deposits Need a Story 
One of the most common issues is large deposits. If money appears in your account that is not clearly from payroll, a tax refund, investment account, gift, or documented sale of an asset, the lender may need an explanation and supporting paperwork. Buyers are sometimes surprised by this, especially when the money is legitimate. The issue is not whether the money belongs to you. The issue is whether the lender can document where it came from under mortgage guidelines.

Closing Cash Goes Beyond the Down Payment 
Bank statements can also show whether you have enough funds beyond the down payment. Closing costs, prepaid taxes, insurance, and reserves may all need to be considered. Some buyers save for the down payment and forget that they may need additional cash to close. Reviewing statements early helps prevent that surprise.

Organization Creates Confidence 
Another quiet signal is consistency. Lenders like to see stable, traceable financial activity. If your money is spread across several accounts, moving constantly, or coming from multiple sources, the process may still work, but it may require more documentation. Keeping funds organized before applying can make the experience smoother.

Self-Employed Buyers Need Clarity 
For self-employed buyers, bank statements can be especially important. Business and personal funds should be easy to distinguish. If income, expenses, transfers, and deposits are mixed together without a clear system, it can create confusion. Good organization does not just help with taxes. It can also support a cleaner mortgage file.

Prepare 
Before applying, take 60 to 90 days to look at your accounts through a mortgage lens. Avoid unnecessary large cash deposits. Keep records for any gift funds or asset sales. Reduce avoidable overdrafts. Know where your closing funds will come from. Save statements for accounts involved in the transaction.

Your bank statements do not need to tell a perfect story. They need to tell a clear one. The more organized your financial paper trail is, the easier it is for your lender to connect the dots. That can mean fewer surprises, fewer last-minute requests, and a more confident path to closing.

Filed Under: Home Buyer Tips Tagged With: Home Buyer Prep, Home Loan Tips, Mortgage Ready

What’s Ahead For Mortgage Rates This Week – June 1st, 2026

June 1, 2026 by Coleen TeBockhorst

The PCE Index inflation data has been released on schedule, and it paints a rather grim outlook for the future. Inflation has reached a three-year high, and given that it is the Federal Reserve’s preferred measure of inflation, it does not bode well for any impending rate cuts and may even raise the possibility of future rate increases.

This is somewhat offset by consumer spending having exceeded expectations, but this appears to be entirely related to high fuel prices, whether consumers want to spend that much or not.

PCE Index
The main inflation barometer preferred by the Federal Reserve rose to a three-year high in April and could rise even higher, posing a stiff challenge for households, businesses and the broader U.S. economy. The personal-consumption price index rose by 0.4% last month, the fifth large increase in a row.

Consumer Spending
Consumer spending rose in April at a seemingly robust rate, but only because of inflation. Americans aren’t getting much bang for their buck these days with gas prices so high. Personal spending increased 0.5% in April, the government said, but inflation also rose 0.4%. Household spending barely rose if inflation is taken into account.

Primary Mortgage Market Survey Index

  • 15-Year FRM rates saw an increase of 0.02%, bringing the current rate to 5.87%.
  • 30-Year FRM rates saw an increase of 0.02%, bringing the current rate to 6.53%.

MND Rate Index

  • 30-Year FHA rates saw a -0.08% decrease, with current rate at 6.10%.
  • 30-Year VA rates saw a -0.08% decrease, with current rate at 6.12%.

Jobless Claims
Initial Claims were reported to be 215,000 compared to the expected claims of 213,000. The previous week landed at 210,000.

What’s Ahead
U.S. wage and employment reports are due next week, along with consumer credit data and several manufacturing-related releases. The following week will bring the latest CPI and PPI data releases.

Filed Under: Financial Reports Tagged With: Financial Report, Jobless Claims, Mortgage Rates

The Hidden Psychology of Interest Rates in a Mortgage

May 29, 2026 by Coleen TeBockhorst

Interest rates are financial numbers, but they also have a strong emotional effect on homebuyers. A small change in rate can make buyers feel excited, nervous, rushed, discouraged, or suddenly motivated. That emotional reaction is understandable, but it can also lead to decisions that are based more on fear than strategy.
The Rate Is Only One Piece 
Many buyers attach too much meaning to a rate by itself. They hear that rates were lower a few years ago and feel like they missed their chance. They see rates move up and assume buying is impossible. They see rates move down and feel pressure to jump before they miss out again. In reality, the rate is only one part of the mortgage picture. The home price, loan amount, down payment, taxes, insurance, loan program, credit profile, and long-term goals all matter.

Avoid the Comparison Trap 
The psychology of rates often creates a comparison problem. Buyers compare today s rate to a past market they cannot access. That can make a current opportunity seem worse than it really is. But past rates also came with different home prices, different competition, and different inventory. A lower rate does not automatically mean a better buying environment if prices were higher, bidding wars were stronger, or buyers had less negotiating power.

Urgency Can Cloud Judgment 
Rates can also create urgency. When buyers believe rates may rise, they may feel pressure to buy any home quickly. That can lead to overlooking red flags, skipping budget conversations, or making offers on homes that do not truly fit. On the other hand, waiting only for a better rate can also be risky. If home prices rise, inventory changes, or personal circumstances shift, the perfect rate may not create the perfect outcome.

Focus on Payment Strategy 
A healthier approach is to focus on payment strategy. Instead of asking whether the rate is good or bad in isolation, ask whether the total payment works for your budget and whether the home supports your goals. Ask what options exist if rates change later. Ask how different down payment amounts, loan programs, or seller credits could affect your monthly cost.

Remember What Can Change 
It is also important to understand that mortgage decisions are not permanent in the same way the home purchase is. You cannot go back and change the house you bought without selling it, but you may have options to refinance in the future if market conditions and your financial profile make sense. Refinancing is never guaranteed, but it is one reason buyers should avoid making today s decision based only on rate anxiety.

Interest rates matter, but they should not control the entire conversation. The best buyers respect the rate without letting it run the show. They look at the full picture, choose a payment they can manage, and decide based on facts instead of market noise.

Filed Under: Home Buyer Tips Tagged With: Home Buyer Tips, Interest Rates, Mortgage Education

Why Your Future Self Should Help Choose Your Mortgage

May 28, 2026 by Coleen TeBockhorst

When people choose a mortgage, they often focus on the life they have right now. They look at today’s income, today’s debts, today’s rent, and today’s goals. That makes sense because a mortgage approval is based heavily on current information. But the smartest buyers also invite their future self into the conversation.

Planning Past Today 
Your future self is the person who will actually live with the mortgage payment 2, 5, or 10 years from now. That version of you may have different priorities. You might want to start a family, change careers, build a business, go back to school, travel more, care for relatives, or save aggressively for retirement. A mortgage that looks perfect today may feel tight later if it does not leave room for change.

Match the Loan to Your Life 
This is why mortgage planning is more than finding a rate and a payment. It is about choosing a structure that fits your bigger life picture. For example, a buyer who expects income to rise may feel comfortable entering the market sooner with a manageable starter home. A buyer who plans to leave a job and become self-employed may want extra savings and a more conservative payment. A buyer hoping to renovate may need to think about future cash flow, not just the cost of buying the home.

Think About Daily Living 
Your future self should also weigh in on location and lifestyle. A longer commute may seem acceptable when the house is beautiful, but will it still feel worth it after 6 months of traffic? A smaller home may work now, but will it still fit if your household changes? A property with a large yard may look charming, but will the time and cost of maintenance match the life you want?

Protect Your Flexibility 
Mortgage choices can also affect future flexibility. Some buyers want to pay the loan off faster, while others value keeping more cash available for investments, emergencies, or life changes. Neither approach is automatically right or wrong. The best choice depends on your goals, risk tolerance, and timeline.

Ask Future Focused Questions 
Before choosing a mortgage, ask yourself a few future focused questions. What could change in my income over the next few years? What major expenses might be coming? How long do I realistically plan to stay in this home? Would this payment still feel okay if my priorities were shifted? What would future me thank current me for doing?

A mortgage should help you move forward, not trap you in a version of life that only works today. Your future self deserves a vote because they are the one who will be making the payments long after closing day. When you plan with that person in mind, you are not just buying a house. You are building a financial decision that can grow with you.

Filed Under: Home Buying Tips Tagged With: Future Homeowner, Home Buying Tips, Mortgage Planning

« Previous Page
Next Page »

Contact Coleen

Coleen Tebockhorst

Coleen TeBockhorst
coleen.tebockhorst@citywidehm.com

Senior Loan Officer

Call me! (612) 701-8512

NMLS #274205

Download My Mortgage eGuide today

CW Home Mortgage logo_White

Guaranteed Rate, Inc. DBA Citywide Home Mortgage

Categories

Our Location

10591 165th St. West
Lakeville MN, 55044

Connect With Me

This site is not authorized by the New York State Department of Financial Services. No mortgage loan applications for properties located in New York will be accepted through this site. Operating in the state of California as Guaranteed Rate, Inc. D/B/A Citywide Home Mortgage. If you are a California resident, please review our Privacy Policy to learn more about the categories and business purpose of personal information we may collect and your right to opt-out from the sale of personal information.

Applicant subject to credit and underwriting approval. Not all applicants will be approved for financing. Receipt of application does not represent an approval for financing or interest rate guarantee. Refinancing your mortgage may increase costs over the term of your loan. Restrictions may apply. All information provided in this publication is for informational and educational purposes only, and in no way is any of the content contained herein to be construed as financial, investment, or legal advice or instruction. Citywide Home Mortgage does not guarantee the quality, accuracy, completeness or timelines of the information in this publication. While efforts are made to verify the information provided, the information should not be assumed to be error-free. Some information in the publication may have been provided by third parties and has not necessarily been verified by Citywide Home Mortgage. Citywide Home Mortgage, its affiliates and subsidiaries do not assume any liability for the information contained herein, be it direct, indirect, consequential, special, or exemplary, or other damages whatsoever and howsoever caused, arising out of or in connection with the use of this publication or in reliance on the information, including any personal or pecuniary loss, whether the action is in contract, tort (including negligence) or other tortious action.

Coleen TeBockhorst NMLS ID: 274205 Copyright © 1998-2025 Guaranteed Rate, Inc. D/B/A Citywide Home Mortgage. All rights reserved.

For licensing information, go to: www.nmlsconsumeraccess.org.

NMLS License #2611 – 3940 N Ravenswood Chicago, IL 60613. (866) 508-5515. Equal Housing Lender.

Licensing | Privacy | Terms of Use

Copyright © 2026 · Powered by MySMARTblog

Copyright © 2026 · Genesis Sample Theme on Genesis Framework · WordPress · Log in