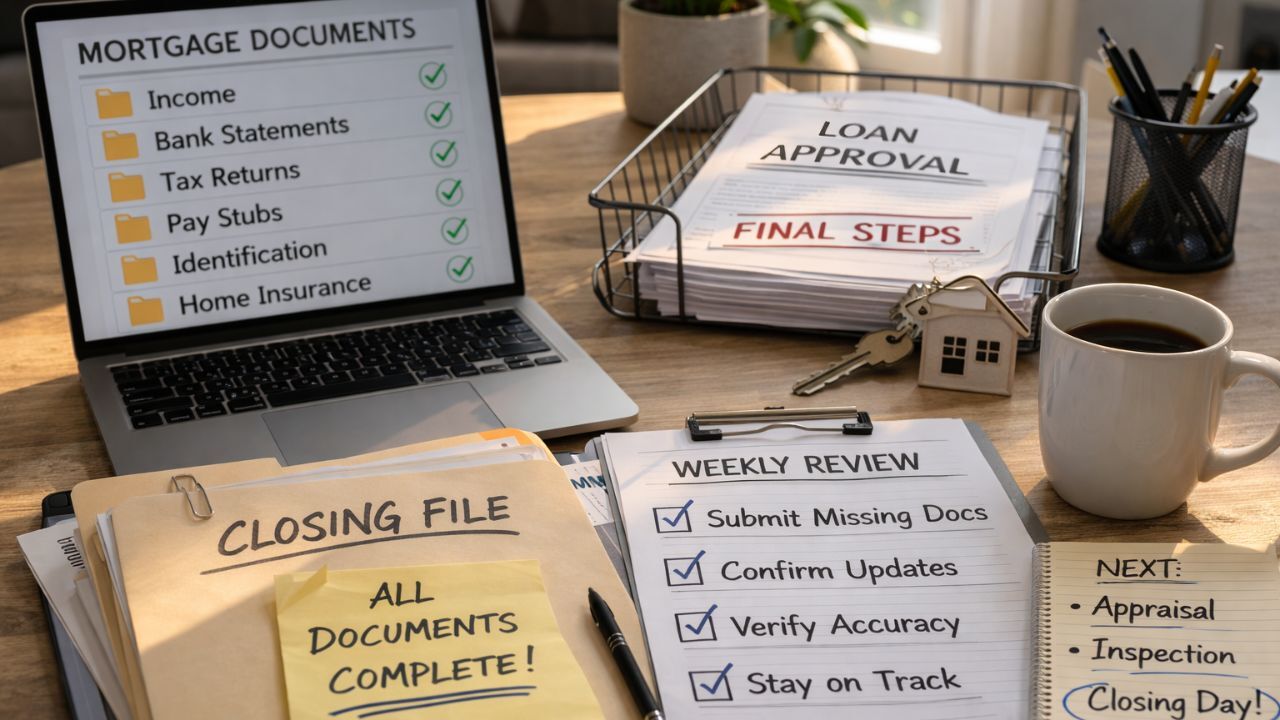
 The mortgage process requires documentation, and organization often determines whether closing feels chaotic or controlled. Many buyers experience stress not because the process itself is overwhelming, but because paperwork is scattered, emails are buried, and requests feel never ending. When documents are difficult to locate or submitted late, small delays can create larger frustrations. The good news is that a simple, intentional system can completely transform the experience.
Create One Secure Document Hub
Start by storing all financial documents in one secure, centralized location. This may be a clearly labeled folder on your computer, a secure cloud drive, or a protected document portal provided by your lender. The key is consistency. Avoid saving some items in email, others on your desktop, and others on your phone.
Label files clearly with both dates and descriptions, such as “2025 W2” or “January 2026 Bank Statement.” Organized naming reduces confusion when updated documents are requested. When everything is centralized and easy to identify, response times improve and stress decreases.
Schedule Weekly Document Reviews
Instead of reacting to every notification immediately, set structured times each week to review outstanding requests and submit required items. This approach creates a rhythm and prevents the mortgage process from feeling constant and intrusive.
During your review, confirm which items have already been submitted and which documents may need updating. Lenders frequently require the most recent pay stubs or bank statements, and planning ahead keeps you prepared. A predictable routine builds confidence and reduces last minute pressure.
Verify Accuracy Before Submission
Before sending documents, take a few moments to verify that everything is complete. Confirm that all pages are included, names are legible, and dates are visible. Even small oversights can trigger additional follow up requests and extend timelines unnecessarily.
Accuracy protects momentum. A careful review today can prevent days of delay later. Closing should feel like progress, not panic. With organization, consistency, and clear communication, buyers can move toward homeownership with clarity and control.
If you are preparing to purchase or refinance and want guidance on navigating the process smoothly, give us a call today.
 Pre-approval is often treated as the green light to shop at the top of a budget. However, the most successful buyers begin with a deeper conversation about comfort, lifestyle, and risk tolerance. A lender can determine what is possible, but only the buyer can determine what feels sustainable. Aligning personal comfort with financial approval creates long term stability.
 Private mortgage insurance allows borrowers to purchase a home with less than twenty percent down. While it increases accessibility, it also increases monthly housing costs. Many borrowers accept mortgage insurance without fully understanding how it affects total loan expense or how it can eventually be removed. Clarity around cost and timeline creates stronger financial positioning.
 Financial stress does not come only from high payments. It often comes from poor planning, unrealistic expectations, and lack of reserves. A well-chosen home should strengthen financial stability, not weaken it. Designing your approach before you purchase can make ownership feel secure instead of overwhelming. Mortgage decisions should prioritize sustainability over maximum borrowing power.
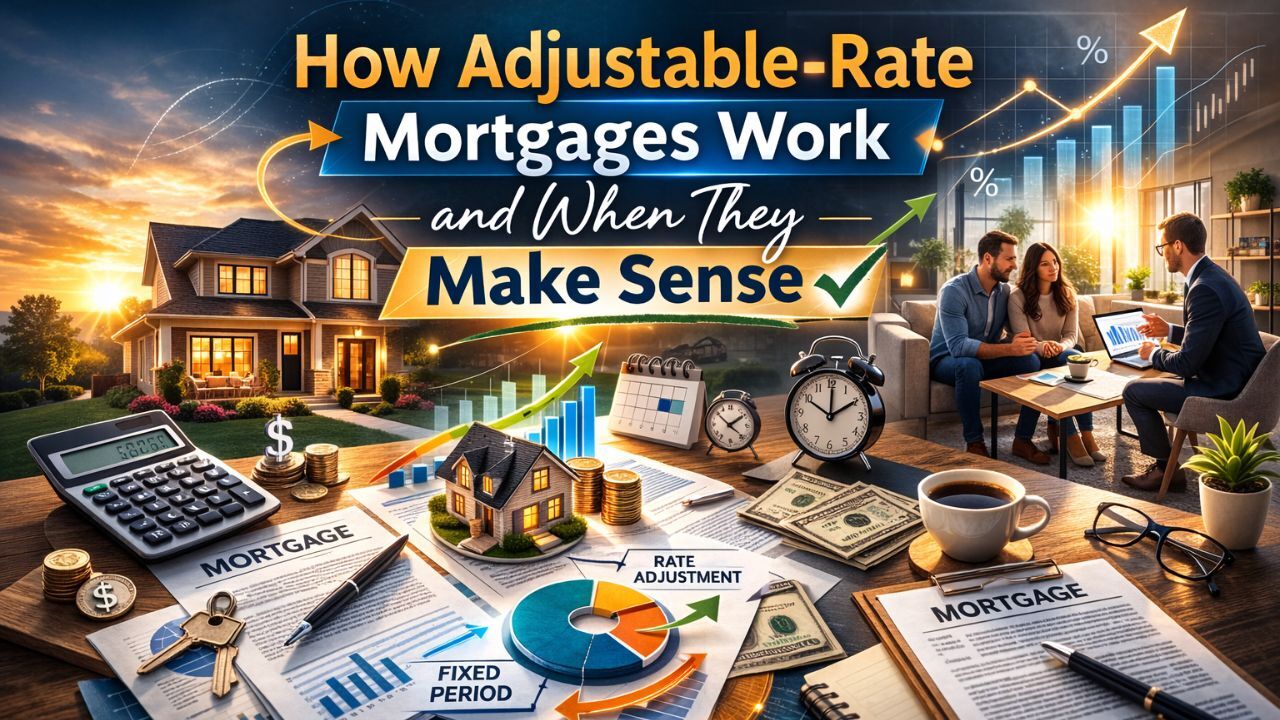 Adjustable-rate mortgages often create hesitation because borrowers focus on the word adjustable. However, these loans can serve a strategic purpose when aligned with specific financial timelines.
 Interest rates get headlines. Payment amounts get attention. Yet neither one determines whether your mortgage will feel sustainable five years from now. What truly determines long-term satisfaction is how your financing decision supports your daily routine.
 Most borrowers believe mortgage qualification is determined primarily by long term financial history. Credit scores, employment consistency, and income trends absolutely matter. However, there is a shorter window that often carries disproportionate influence. The 60 days before you apply can either strengthen your file or introduce unnecessary friction into the underwriting process.
 Most people view a mortgage as a liability. While it is technically debt, it can also function as a structured financial discipline system that builds long term equity. When approached intentionally, a mortgage becomes more than a payment. It becomes a framework for consistent wealth accumulation.
