 Traditional mortgages are not the only way to finance a home. For buyers who want more flexibility or who face unique financial circumstances, creative mortgage options can provide alternative pathways to homeownership. These products are not always as well-known as standard fixed-rate loans, but they can be powerful tools when used wisely.
Shared Appreciation Mortgages Explained
A shared appreciation mortgage allows a lender or investor to provide a loan in exchange for a percentage of the future appreciation of the property. This often means lower monthly payments or reduced upfront costs for the borrower. When the home is sold, refinanced, or after a set period, the investor receives their share of the increase in value.
Benefits of Shared Appreciation
This option can make homeownership more affordable, especially in high-cost areas. It may be appealing to first-time buyers who want to reduce their monthly expenses or to homeowners who want to tap equity without taking on additional debt. By sharing future appreciation, the homeowner gets help today in exchange for giving up a portion of tomorrowís potential gains.
Risks to Consider
While shared appreciation reduces costs in the short term, it comes with trade-offs. If your home value increases significantly, you could end up giving away a large portion of your profit. This structure also adds complexity when it comes to selling or refinancing the property. Borrowers must carefully read the terms and fully understand how appreciation will be calculated.
Other Creative Mortgage Alternatives
In addition to shared appreciation, there are other options worth exploring. Community land trusts help lower purchase prices by separating the cost of the land from the home itself. Lease-to-own arrangements allow renters to build equity while preparing for traditional financing later. Seller financing is another alternative where the seller provides the loan directly, often with more flexible terms than a bank.
Creative mortgage options can be powerful tools, but they are not a one-size-fits-all solution. Before pursuing these paths, consider your financial goals, long-term plans, and how much control you want to retain over future profits.
 When shopping for a mortgage, you may come across an option that allows you to pay only the interest for the first several years of the loan. These are called interest-only mortgages, and while they may sound appealing at first glance, they are not the right fit for everyone. Understanding how they work and who benefits from them is key to making a smart decision.
 First responders and military families play vital roles in our communities, and there are mortgage programs designed to recognize their service. These programs often provide favorable terms, lower down payments, and unique benefits that make homeownership more accessible. Understanding these options can help heroes and their families achieve their dream of owning a home while taking advantage of benefits tailored to their service.
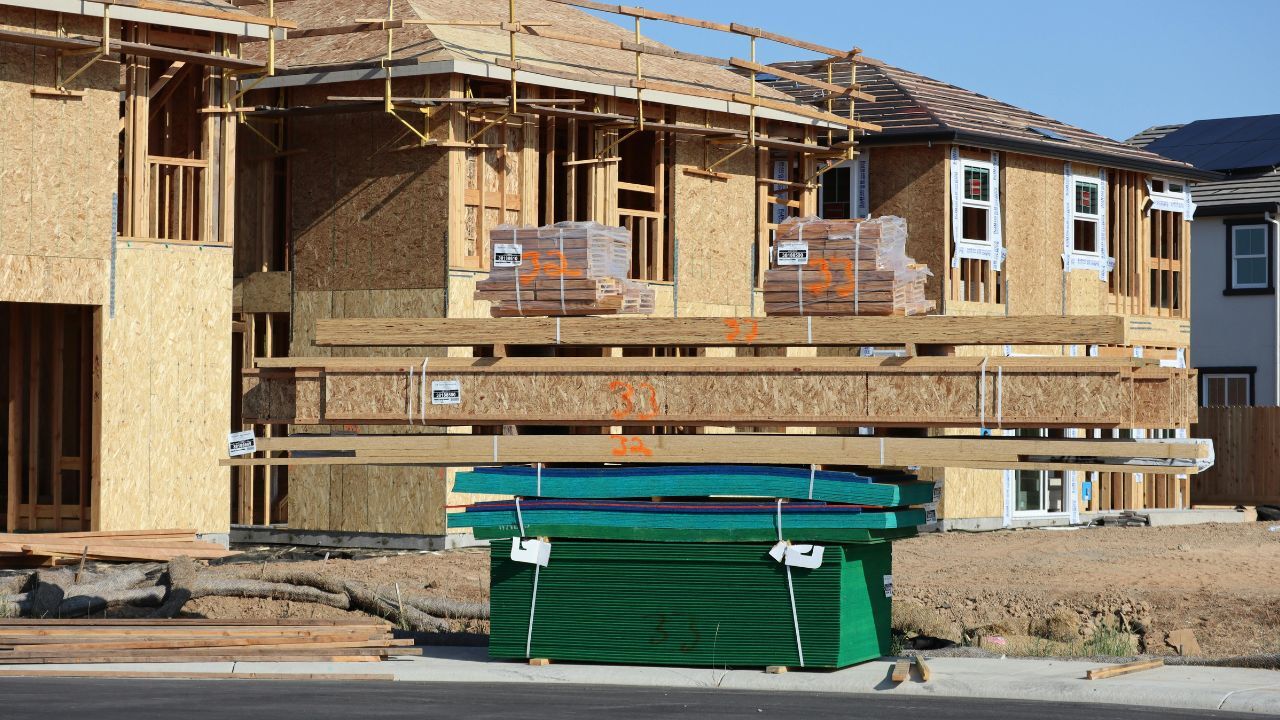 Buying land or constructing a new home offers exciting opportunities for customization and investment, but the mortgage process differs from traditional home loans. Lenders often have stricter requirements for land and new construction financing, so understanding your options, planning ahead, and working closely with a mortgage professional is essential. By knowing what to expect, you can navigate this process smoothly and secure the financing needed to bring your vision to life.
 Your mortgage is more than just a monthly bill; it can be a powerful tool for building long-term wealth. By understanding how to leverage home equity strategically, homeowners can create opportunities for investments, financial growth, and increased net worth. Using your mortgage wisely requires planning, patience, and a clear understanding of how equity works.
 Losing a job can be stressful, and the thought of keeping up with your mortgage payments may feel overwhelming. The good news is that there are steps homeowners can take to protect their home and maintain financial stability during periods of unemployment. Understanding your options, communicating with your lender, and planning ahead can help you navigate this challenging time without risking your home.
 Owning multiple properties can be a smart investment strategy, but managing separate loans for each property can be complex and expensive. A blanket mortgage offers a solution by allowing homeowners or investors to finance two or more properties under a single loan. This type of mortgage can simplify payments, streamline management, and often provide better rates than holding multiple individual mortgages. Understanding how a blanket mortgage works and when it makes sense can help you maximize your real estate investments efficiently.
 A cash-out refinance can be a powerful tool for homeowners who want to leverage the equity in their home, but it is important to approach it strategically. This type of refinance replaces your existing mortgage with a new, larger loan, giving you the difference in cash. Whether you are planning home improvements, consolidating high-interest debt, or investing, using a cash-out refinance wisely can help you reach your financial goals without creating unnecessary risk.
