CTeBockhorst's Blog

The Mortgage and Real Estate Scoop

  • Home
  • About
  • Blog
  • Resources
    • Calculators
    • Download My eGuide Today!
    • First Time Buyer Tips
    • First Time Seller Tips
    • Loan Checklist
    • Loan Process
    • Loan Programs
    • Home Appraisal
    • Home Inspection
    • What to Expect at a Loan Closing: A Step-by-Step Guide
  • Apply
  • Reviews
    • Read My Reviews
    • Zillow Reviews
    • Leave a Review
  • Contact

What’s Ahead For Mortgage Rates This Week – July 8th, 2024

July 8, 2024 by Coleen TeBockhorst

With the FOMC Minutes coming precisely within expectations, there is once again a lot of optimism that the Federal Reserve may cut rates this year. Much of the Q2 data reports show favorable amounts of reduction in inflation as well as a more stable economic outlook for the rest of the year. With the larger reports in PMI Manufacturing numbers and Non-farm Payroll figures, the overall outlook seems to align with the rest of the data points, justifying the more recent optimism about potential rate cuts. This week should give the final results on Q2 inflation results with the new releases of CPI and PPI data reports.

Global US Manufacturing PMI

A key barometer of U.S. factories fell in June for the third month in a row, signaling that an ongoing slump in the industrial side of the economy shows no sign of ending. The Institute for Supply Management’s manufacturing index slipped to 48.5% in June from 48.7% in the prior month. Numbers below 50% signal that the manufacturing sector is shrinking.

U.S. Hourly Wages

Wage growth for the last 12 months ending in June slowed to 3.9% from 4.1%, marking the smallest increase seen since August 2021. At one point, yearly wages were rising as fast as 5.9%. A shortage of labor prompted millions to change jobs in pursuit of better pay, particularly to cope with significant inflation.

Primary Mortgage Market Survey Index

  • 15-Yr FRM rates are seeing an increase by 0.09% with the current rate at 6.25%
  • 30-Yr FRM rates are seeing an increase by 0.09% with the current rate at 6.95%

MND Rate Index

  • 30-Yr FHA rates are seeing a decrease by -0.01% for this week. Current rates at 6.50%
  • 30-Yr VA rates are seeing no change for this week. Current rates at 6.52%

Jobless Claims

Initial Claims were reported to be 238,000 compared to the expected claims of 233,000. The prior week landed at 234,000.

What’s Ahead

CPI and PPI are the most relevant reports coming up, with the rest of the week having an extremely light release schedule. 
Filed Under: Financial Reports Tagged With: Financial Report, Jobless Claims, Mortgage Rates

Prequalification vs. Preapproval: Key Differences Every First-Time Home Buyer Should Know

July 7, 2024 by Coleen TeBockhorst

What’s the Difference Between Prequalification and Preapproval?

Introduction

When buying a home, understanding mortgage terms is crucial. Two key terms you’ll encounter are “prequalification” and “preapproval.” While they sound similar, they serve different purposes. This post explains the differences to help you make informed decisions.

What is Prequalification?

Definition:
Prequalification is an initial step where you provide basic financial information to a lender, including income, assets, debts, and credit score.

Process:

  • Submit financial details online, by phone, or in person.
  • Lender reviews information to estimate the mortgage amount you might qualify for.
  • Quick and informal, usually taking a few minutes.

Benefits:

  • Provides an early estimate of your borrowing capacity.
  • No impact on your credit score.
  • Useful for initial exploration of mortgage options.

Limitations:

  • Based on unverified information, making it less reliable.
  • Not a guarantee of loan approval or terms.

What is Preapproval?

Definition:
Preapproval is a detailed process where a lender verifies your financial information to determine your creditworthiness and loan eligibility.

Process:

  • Provide documentation such as proof of income, bank statements, and tax returns.
  • Lender conducts a thorough financial evaluation, including a credit check.
  • If approved, you receive a preapproval letter with loan amount, interest rate, and terms.

Benefits:

  • More accurate and reliable estimate of your borrowing capacity.
  • Strengthens your position as a serious buyer.
  • Some lenders offer rate lock options.

Limitations:

  • More time-consuming, requiring detailed documentation.
  • Involves a hard credit check, which can temporarily affect your credit score.

Key Differences Between Prequalification and Preapproval

1. Depth of Information:

  • Prequalification: Based on self-reported information.
  • Preapproval: Based on verified financial information and a credit check.

2. Reliability:

  • Prequalification: Provides an estimate, not a guarantee.
  • Preapproval: Offers a conditional commitment from the lender.

3. Time and Effort:

  • Prequalification: Quick and easy.
  • Preapproval: Detailed and time-consuming.

4. Impact on Buying Process:

  • Prequalification: Helps set a budget.
  • Preapproval: Positions you as a serious buyer.

Which One Should You Get?

Prequalification:

  • Early stages of home buying.
  • Exploring different lenders and options.

Preapproval:

  • Ready to start house hunting.
  • Making strong offers in competitive markets.

Conclusion

Understanding prequalification and preapproval can enhance your home buying experience. Prequalification gives an initial idea of your borrowing capacity, while preapproval provides a reliable assessment, positioning you as a qualified buyer. For personalized advice, contact Coleen TeBockhorst at Bay Equity Home Loans.

Contact Information:

  • Phone: 612-701-8512
  • Email: Coleen@ColeenTeBockhorst.com
  • Website: Bay Equity Home Loans
  • Facebook: Coleen TeBockhorst

Call to Action

Stay informed and make the best investment decisions by following our blog and social media channels. Share this post with anyone who might benefit from understanding the differences between prequalification and preapproval!


Filed Under: Home Buyer Tips, Home Mortgage Tips Tagged With: #PrequalificationVsPreapproval #FirstTimeHomeBuyer #MortgageTips #HomeBuyingAdvice

Top 4 Essential Questions to Ask a Loan Officer as a First-Time Home Buyer

July 6, 2024 by Coleen TeBockhorst


Introduction

Buying your first home can be an exciting but overwhelming experience. One of the most crucial steps is speaking with a loan officer who can guide you through the mortgage process. Asking the right questions can help you understand your options and ensure you’re making informed decisions. In this post, we’ll focus on the top four questions that first-time home buyers frequently ask loan officers.

1. What Types of Loans Are Available to Me?

Understanding the different loan options available can help you choose the best one for your financial situation. Common loan types include:

  • Conventional Loans: Not insured by the government, usually requiring higher credit scores and larger down payments.
  • FHA Loans: Insured by the Federal Housing Administration, these loans are ideal for first-time buyers with lower credit scores and smaller down payments.
  • VA Loans: Available to veterans and active-duty military personnel, offering competitive rates and often requiring no down payment.
  • USDA Loans: Designed for rural home buyers, these loans offer low interest rates and no down payment requirements.

Follow-Up Questions:

  • Which loan type best fits my financial situation?
  • What are the specific eligibility requirements for each loan type?
  • Are there any special programs or incentives for first-time home buyers?

2. What Will My Interest Rate Be?

Your interest rate will significantly impact your monthly mortgage payments and the total cost of your loan. It’s essential to understand how your rate is determined and whether it can change over time.

Follow-Up Questions:

  • How is my interest rate determined?
  • Are there ways to lower my interest rate?
  • Can I lock in my interest rate, and if so, for how long?

3. What Are the Closing Costs?

Closing costs are fees associated with finalizing your mortgage and can range from 2% to 5% of the loan amount. Knowing what to expect can help you budget accordingly.

Follow-Up Questions:

  • What specific closing costs will I be responsible for?
  • Can any of these costs be negotiated or waived?
  • Are there any lender credits available to help cover closing costs?

4. How Much Down Payment Is Required?

The down payment is a crucial part of the home buying process, affecting your loan-to-value ratio and mortgage terms. Understanding your down payment requirements can help you plan your finances better.

Follow-Up Questions:

  • What is the minimum down payment required for this loan?
  • Are there any down payment assistance programs available?
  • How will my down payment amount affect my mortgage terms?

Conclusion

Asking these top four questions can provide you with a solid understanding of your mortgage options and help you make informed decisions. A good loan officer will be happy to answer your questions and guide you through the process. For personalized advice and to explore your mortgage options, contact Coleen TeBockhorst at Bay Equity Home Loans. Our team is here to help you achieve your homeownership dreams in Minneapolis.

Contact Information:

  • Phone: 612-701-8512
  • Email: Coleen@ColeenTeBockhorst.com
  • Website: Bay Equity Home Loans
  • Facebook: Coleen TeBockhorst

Call to Action

Stay informed and make the best investment decisions by following our blog and social media channels. Don’t forget to share this post with friends and family who might benefit from these essential questions to ask a loan officer as a first-time home buyer!


Filed Under: Home Buyer Tips, Mortgage Tagged With: #FirstTimeHomeBuyer #MortgageAdvice #HomeBuyingTips #LoanOfficerQuestions

What NOT to Do After Applying for a Mortgage Loan: Top 5 Mistakes to Avoid

July 5, 2024 by Coleen TeBockhorst

https://tebockhorstmortgage.com/wp-content/blogs.dir/620/files/sites/64/2024/07/Things-to-Avoid-after-applying-for-a-mortgage.mp4

Learn the top 5 mistakes to avoid after applying for a mortgage loan to ensure a smooth approval process. From avoiding large purchases to maintaining financial stability, these essential tips will help you secure your dream home. Watch now for expert advice on homebuying and mortgage approval.

Filed Under: Home Buyer Tips, Home Mortgage Tips, Mortgage Tips Tagged With: Home Buyer Tips, Mortgage Tips, Mortgages and Credit

The Pros and Cons of Mortgage Life Insurance

July 5, 2024 by Coleen TeBockhorst

Mortgage life insurance is a type of policy designed to pay off your mortgage in the event of your death. As with any financial product, it has its pros and cons. Understanding these can help you determine whether it makes sense for your situation.
What is Mortgage Life Insurance?

Mortgage life insurance, sometimes called mortgage protection insurance, is a policy that pays the remaining balance of your mortgage if you pass away before it is fully paid off. The benefit is directly linked to the amount you owe on your home loan and decreases as your mortgage balance decreases.

Advantages of Mortgage Life Insurance

  1. Peace of Mind: Knowing that your mortgage will be paid off if you pass away can provide significant peace of mind for you and your loved ones.
  2. Financial Security for Loved Ones: This type of insurance ensures that your family can stay in the home without the burden of mortgage payments.
  3. Simplified Underwriting: Unlike some other types of life insurance, mortgage life insurance often has simplified underwriting processes, which means fewer medical exams and quicker approval times.

Drawbacks of Mortgage Life Insurance

  1. Decreasing Benefit: The payout decreases as your mortgage balance decreases, meaning the value of the policy diminishes over time.
  2. Lack of Flexibility: The benefit goes directly to the mortgage lender, not to your beneficiaries, limiting how the funds can be used.
  3. Potentially Higher Costs: Mortgage life insurance can be more expensive compared to term life insurance for the same amount of coverage.
  4. No Coverage for Other Expenses: It only covers the mortgage, so other financial needs of your family, such as living expenses, education, or other debts.

When Does Mortgage Life Insurance Make Sense?

  1. Health Issues: If you have health conditions that make it difficult or expensive to qualify for traditional life insurance, mortgage life insurance might be a more accessible option.
  2. Simplified Needs: If your primary concern is ensuring that your mortgage is paid off and you are not as worried about leaving additional financial support for your family, this type of policy could be suitable.
  3. Elderly Homeowners: Older homeowners who may face higher premiums for traditional life insurance might find mortgage life insurance a more affordable way to protect their mortgage.

When Should You Avoid Mortgage Life Insurance?

  1. Better Alternatives: If you can qualify for a term life insurance policy, it often provides more flexibility and can be more cost-effective. Term life insurance can cover more than just your mortgage, providing your beneficiaries with funds to use as they see fit.
  2. Stable Financial Situation: If you have significant savings or other forms of life insurance that can cover your mortgage, additional mortgage life insurance may be unnecessary.
  3. High Premiums: If the premiums for mortgage life insurance are significantly higher than other options available to you, it may not be worth the cost.

Mortgage life insurance can be a valuable tool for some homeowners, providing peace of mind and ensuring that their family can remain in the home. However, it is not the best choice for everyone. Evaluating your overall financial situation, the costs, and the benefits compared to other insurance options will help you make an informed decision.

By considering your unique circumstances, you can determine whether mortgage life insurance makes sense for you and your family.

Filed Under: Mortgage Tagged With: Insurance Coverage, Mortgage, Mortgage Life Insurance

Celebrating Independence Day: More Than Just Fireworks and BBQs

July 4, 2024 by Coleen TeBockhorst

While fireworks, barbecues, and parades are fundamental to our 4th of July celebrations, the spirit of Independence Day runs much deeper. It’s a time to honor our history, recognize our freedoms, and celebrate the unity that defines us as a nation.

A History Worth Remembering

On July 4, 1776, the Continental Congress adopted the Declaration of Independence, marking the birth of the United States of America. This historic document, crafted by Thomas Jefferson and signed by representatives of the thirteen colonies, asserted our nation’s right to self-governance and freedom from British rule. It was a bold declaration of the values we hold dear—liberty, equality, and the pursuit of happiness.

Honoring Our Freedoms

Independence Day is a celebration of the freedoms that are foundational to our nation. The freedoms of speech, religion, and assembly, among others, are enshrined in our Constitution and Bill of Rights. These freedoms have shaped our society and continue to be the cornerstone of American democracy. By celebrating the 4th of July, we pay tribute to the vision of our Founding Fathers and the sacrifices of countless individuals who have fought to preserve these rights.

A Time for Gratitude

It is important to express gratitude for the privileges we enjoy as Americans. The freedoms and opportunities we often take for granted are the result of the hard-fought battles and unwavering determination of those who came before us. Taking a moment to appreciate this legacy fosters a sense of responsibility to protect and nurture these values for future generations.

As we light up the sky with fireworks and gather with loved ones this 4th of July, let’s remember that Independence Day is more than just a summer holiday. It’s a celebration of our history, our freedoms, and our unity. By reflecting on the significance of this day, we can truly appreciate the privileges we enjoy and commit ourselves to upholding the values that define our great nation.

Happy Independence Day! Let’s celebrate with pride and purpose. What are your favorite 4th of July traditions? Share them with us in the comments below!

 Stay safe and enjoy your 4th of July!

Filed Under: Holidays Tagged With: Freedom, Gratitude, IndependenceDay

How to Read Your Mortgage Statement: What to Look For and How to Ensure Its Accuracy

July 3, 2024 by Coleen TeBockhorst

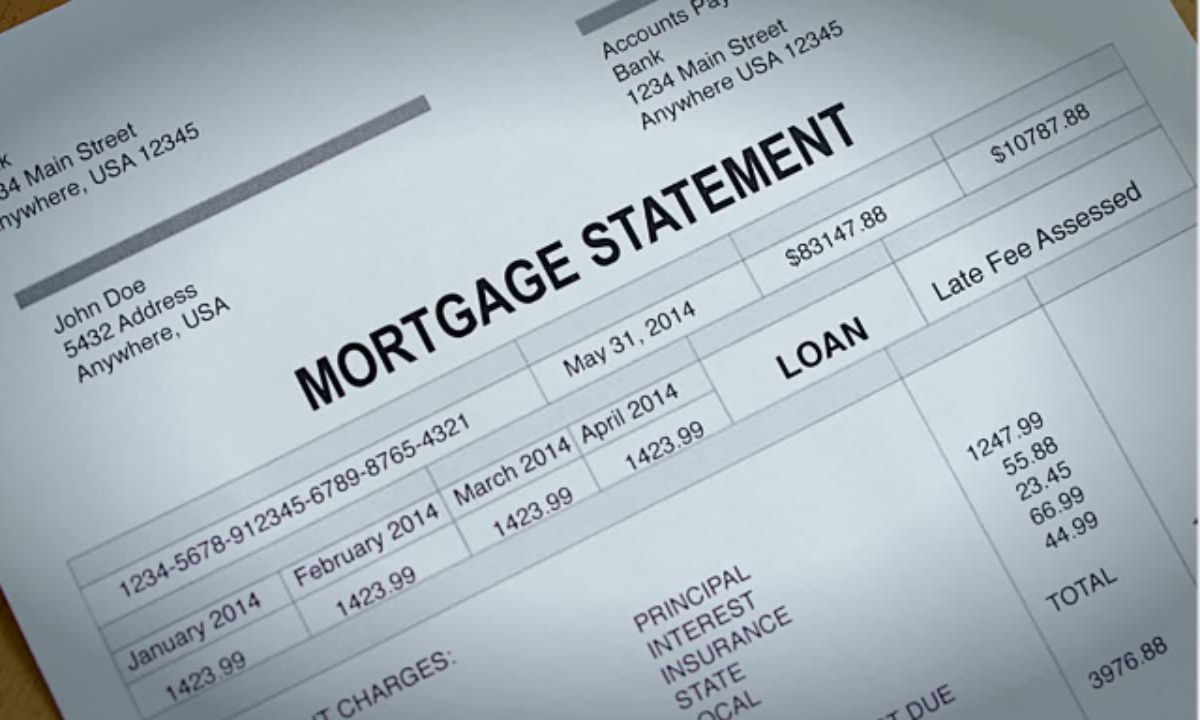
Your mortgage statement is an important document that provides detailed information about your home loan. Understanding it can help you manage your mortgage more effectively, identify potential issues early, and ensure you’re on track with your payments. Here is a list to help guide you when reading your mortgage statement, what to look for, and how to verify its accuracy.
Key Components of a Mortgage Statement

  1. Account Information
    • Loan Number: A unique identifier for your mortgage.
    • Property Address: The address of the property financed by the mortgage.
  2. Payment Information
    • Current Payment Due: The amount you need to pay by the due date.
    • Due Date: The date by which the payment must be made to avoid late fees.
    • Previous Balance: The amount you owe from the previous statement.
    • Payments Received: Payments made since the last statement.
  3. Escrow Account
    • Escrow Balance: The amount held in escrow for property taxes and insurance.
    • Escrow Payments: The portion of your monthly payment that goes into the escrow account.
  4. Transaction Activity
    • Payments: Detailed list of payments made, including principal, interest, and escrow.
    • Charges: Any additional fees or charges applied to your account.
  5. Loan Information
    • Principal Balance: The remaining balance on your loan.
    • Interest Rate: The current interest rate on your mortgage.
    • Loan Term: The length of your loan in years.
  6. Contact Information
    • Contact details for customer service, in case you have questions or concerns about your statement.

How to Read and Understand Your Mortgage Statement

  1. Verify Personal and Loan Information
    • Ensure that your loan number, property address, and personal details are correct. Any discrepancies should be reported immediately to your mortgage servicer.
  2. Check Payment Details
    • Compare the “Current Payment Due” with what you expect to pay. Ensure that the due date is noted and plan your payment accordingly to avoid late fees.
    • Review the “Previous Balance” and “Payments Received” sections to ensure that all your payments have been accurately credited.
  3. Review Escrow Account Activity
    • Look at the escrow balance and payments to ensure that your taxes and insurance are being correctly funded. If there are significant changes, contact your servicer to understand why.
  4. Analyze Transaction Activity
    • Ensure that all payments, fees, and charges listed are accurate. If you see any unfamiliar fees or charges, contact your mortgage servicer for clarification.
  5. Understand Your Loan Details
    • Keep track of your principal balance to see how much you owe over time. Knowing your interest rate and loan term is also essential for planning and managing your finances.

Ensuring the Accuracy of Your Mortgage Statement

  1. Keep Records
    • Maintain a record of all your mortgage payments, including bank statements, payment receipts, and previous mortgage statements. This helps in cross-referencing and verifying the accuracy of your current statement.
  2. Compare Statements
    • Regularly compare your current mortgage statement with previous ones to identify any discrepancies or unusual changes.
  3. Monitor Escrow Account
    • Keep an eye on your escrow account to ensure that payments for property taxes and insurance are correctly allocated. Request an annual escrow analysis from your mortgage servicer.
  4. Contact Your Servicer
    • If you notice any errors or discrepancies, contact your mortgage servicer immediately. Keep a record of all communications, including dates, names of representatives you spoke with, and the nature of the discussions.
  5. Seek Professional Help
    • If you are unsure about any aspect of your mortgage statement or encounter issues with your servicer, consider consulting with a financial advisor or a housing counselor.

Reading and understanding your mortgage statement is essential for effective mortgage management. Regularly reviewing your mortgage statement and maintaining accurate records will help you stay on top of your mortgage and achieve your homeownership goals smoothly. Feel free to leave any questions or comments below and we will be happy to assist you!

Filed Under: Mortgage Tagged With: Finance's, Mortgage, Mortgage Statement

Understanding Graduated Payment Mortgages

July 2, 2024 by Coleen TeBockhorst

When it comes to buying a home, you will find many mortgage options available. One of the lesser-known but potentially advantageous choices is the Graduated Payment Mortgage (GPM). Let’s discuss what GPMs are, how they work, and how they differ from other mortgage options.
What is a Graduated Payment Mortgage?

A Graduated Payment Mortgage is a type of home loan where the payments start low and gradually increase over time. This structure can be particularly appealing to those who expect their income to rise steadily in the future. The idea is to match your mortgage payments with your anticipated financial growth, easing the initial burden when you might have less income.

How Does a Graduated Payment Mortgage Work?

  1. Initial Low Payments: In the beginning, your monthly mortgage payments are relatively low. This can make homeownership more accessible if you’re just starting out in your career or have limited income initially.
  2. Scheduled Increases: Over a predetermined period (usually 5 to 10 years), your payments increase annually. These increases are predefined and detailed in your mortgage agreement.
  3. Leveling Off: After the initial period of increasing payments, your payments will level off and remain constant for the remainder of the loan term.
  4. Interest Accrual: During the initial years, when payments are lower, they may not cover the full interest on the loan. The unpaid interest is added to the principal balance, a process known as negative amortization. This means your loan balance might actually increase in the early years.

Key Differences from Other Mortgage Types

  1. Fixed-Rate Mortgages (FRM):
    • Stability vs. Flexibility: Fixed-rate mortgages offer stable payments throughout the life of the loan. In contrast, GPMs provide lower initial payments with scheduled increases, offering more flexibility early on but less predictability in the long term.
    • Interest Rates: Fixed-rate mortgages have a constant interest rate, whereas GPMs can have varying effective interest rates due to negative amortization in the early years.
  2. Adjustable-Rate Mortgages (ARM):
    • Interest Rate Changes: ARMs have interest rates that change periodically based on market conditions, while GPMs have fixed scheduled payment increases.
    • Payment Stability: GPMs have predetermined payment increases, providing more predictability compared to ARMs, which can fluctuate significantly.
  3. Interest-Only Mortgages:
    • Payment Structure: Interest-only mortgages allow you to pay only the interest for a certain period, after which you must start paying principal and interest. GPMs, on the other hand, start with low payments that gradually increase, always including principal and interest components.
    • Principal Reduction: With a GPM, you start reducing your principal balance earlier compared to an Interest-only mortgage, where principal reduction starts after the interest-only period.

Is a Graduated Payment Mortgage Right for You?

A GPM can be a good fit if:

  • You expect a significant increase in your income over the next few years.
  • You need lower initial payments to manage your budget early on.
  • You are comfortable with the prospect of rising payments in the future.

However, it’s crucial to carefully consider your financial stability and future earning potential. The scheduled increases in payments are fixed, and if your income doesn’t grow as expected, you might find yourself struggling to keep up.

Graduated Payment Mortgages offer a unique approach to home financing, providing lower initial payments that grow over time. Understanding the complexities of various mortgage types is essential for making the best financial decision for your future. If you have any questions or need personalized advice, feel free to reach out to us.

Filed Under: Mortgage Tagged With: Graduated Payment Mortgage, Mortgage, Mortgage Tips

What’s Ahead For Mortgage Rates This Week – July 1st, 2024

July 1, 2024 by Coleen TeBockhorst

Following the release of key data such as the FOMC rate decision and CPI and PPI inflation reports, only the PCE Index reports remained to set the course, which are coming in well within expectations. The Consumer Confidence Report is also a significant concern since it influences broader economic decisions when consumers hesitate to spend, usually due to rising living costs.

Consumer Confidence Report

Consumers were slightly more optimistic about the economy at the end of June, but the effects of high inflation in the past few years still weighed on their minds. The final reading of the consumer sentiment index rose to 68.2 in June from a preliminary 65.6 earlier in the month, but it’s still the lowest level in seven months. The index also stands well below a prepandemic peak of 101. Although Americans think inflation will ease, they say high inflation and slower income growth have worried them more about their finances, according to the University of Michigan survey.

PCE Index

The Federal Reserve’s preferred PCE index was unchanged last month, the government said Friday. Economists polled by The Wall Street Journal had forecast a flat reading. If inflation continues to recede in the next few months, the Fed could lay the groundwork to cut U.S. interest rates in the fall. The increase in inflation in the past 12 months slipped to 2.6% from 2.7%. The Fed is aiming to bring inflation down to 2% a year.

Primary Mortgage Market Survey Index

  • 15-Yr FRM rates are seeing an increase by 0.03% with the current rate at 6.16%
  • 30-Yr FRM rates are seeing a decrease by -0.01% with the current rate at 6.86%

MND Rate Index

  • 30-Yr FHA rates are seeing an increase by 0.02% for this week. Current rates at 6.51%
  • 30-Yr VA rates are seeing an increase by 0.02% for this week. Current rates at 6.52%

Jobless Claims

Initial Claims were reported to be 233,000 compared to the expected claims of 235,000. The prior week was landed at 239,000.

What’s Ahead

Next week, we anticipate ISM Manufacturing data, U.S. trade deficits, and overall U.S. unemployment figures to provide further insights into the direction of the economy. Despite being less comprehensive reports, they often serve as early indicators of inflation trends which are a crucial focus for all stakeholders.

Filed Under: Financial Reports Tagged With: Financial Report, Jobless Claims, Mortgage Rates

Should You Get a Mortgage from a Bank or Lender? | Bay Equity Home Loans Explains

June 30, 2024 by Coleen TeBockhorst

Is it Better to Get a Mortgage from a Bank or Lender?

Introduction

When you’re ready to buy a home, one of the most important decisions you’ll make is choosing where to get your mortgage. Should you go with a traditional bank or opt for a specialized mortgage lender? Both options have their own advantages and disadvantages. In this post, we’ll explore the key differences between banks and mortgage lenders, helping you decide which option is best for your financial situation and home buying needs.

Understanding the Difference

Banks:

  • Traditional Financial Institutions: Banks provide a wide range of financial services, including savings and checking accounts, personal loans, and mortgages.
  • Regulated Entities: Banks are heavily regulated and tend to have stricter lending criteria.
  • Customer Relationship: Having an established relationship with a bank can sometimes make it easier to get a mortgage.

Mortgage Lenders:

  • Specialized Institutions: Mortgage lenders focus exclusively on home loans and related services.
  • Flexibility: They often have more flexible lending criteria and a variety of loan products.
  • Speed: Mortgage lenders can sometimes process loans faster than traditional banks.

Advantages of Getting a Mortgage from a Bank

1. Stability and Security:

  • Banks are well-established and regulated institutions, providing a sense of security and stability.
  • They often have more stringent lending criteria, which can ensure that borrowers are financially prepared.

2. Established Relationships:

  • If you already have accounts with a bank, you may benefit from loyalty discounts or preferential treatment.
  • The existing relationship can make the mortgage process smoother.

3. One-Stop Shop:

  • Banks offer a wide range of financial products and services, allowing you to manage all your finances in one place.

Disadvantages of Getting a Mortgage from a Bank

1. Stricter Requirements:

  • Banks often have stricter credit score and income requirements, which can make it harder to qualify for a mortgage.
  • The approval process can be slower due to more rigorous checks and balances.

2. Less Flexibility:

  • Banks may offer fewer loan products compared to specialized mortgage lenders.
  • Their rates and terms may not be as competitive as those offered by mortgage lenders.

Advantages of Getting a Mortgage from a Lender

1. Flexibility:

  • Mortgage lenders often have more flexible lending criteria, making it easier for borrowers with lower credit scores or unconventional income sources to qualify.
  • They offer a variety of loan products tailored to different financial situations.

2. Competitive Rates:

  • Specialized mortgage lenders can often provide more competitive interest rates and terms compared to traditional banks.
  • They are more likely to negotiate rates and fees.

3. Speed:

  • Mortgage lenders can typically process loans faster due to a more streamlined approval process.
  • They often have dedicated teams focused solely on mortgages, leading to quicker turnaround times.

Disadvantages of Getting a Mortgage from a Lender

1. Lack of Relationship:

  • If you don’t have an existing relationship with the lender, the process may feel less personal.
  • Lenders may not offer the same range of financial products and services as banks.

2. Stability Concerns:

  • Mortgage lenders, especially smaller or newer ones, may not have the same level of stability as traditional banks.
  • It’s important to research the lender’s reputation and financial health.

Minneapolis Market Insight

In the competitive Minneapolis real estate market, both banks and mortgage lenders play crucial roles. The choice between the two depends on your specific financial situation and home buying needs. Minneapolis offers a variety of housing options, and securing the best mortgage can make a significant difference in your home buying experience.

Conclusion

Deciding whether to get a mortgage from a bank or a lender depends on your personal circumstances and preferences. Banks offer stability and a range of financial services, while mortgage lenders provide flexibility and potentially better rates. It’s essential to compare offers from both types of institutions to find the best deal for your situation.

For personalized advice and to explore your mortgage options, contact Coleen TeBockhorst at Bay Equity Home Loans. Our team is here to guide you through the process and help you achieve your homeownership dreams in Minneapolis.

Contact Information:

  • Phone: 612-701-8512
  • Email: Coleen@ColeenTeBockhorst.com
  • Website: Bay Equity Home Loans
  • Facebook: Coleen TeBockhorst

Call to Action

Stay informed and make the best investment decisions by following our blog and social media channels. Don’t forget to share this post with friends and family who might benefit from learning about the pros and cons of getting a mortgage from a bank versus a lender!


Filed Under: Home Buyer Tips, Home Mortgage Tips, Mortgage Tips Tagged With: #MortgageAdvice #HomeBuyingTips #RealEstateLoans #MinneapolisHomeLoans

« Previous Page
Next Page »

Contact Coleen

Coleen Tebockhorst

Coleen TeBockhorst
coleen.tebockhorst@citywidehm.com

Senior Loan Officer

Call me! (612) 701-8512

NMLS #274205

Download My Mortgage eGuide today

CW Home Mortgage logo_White

Guaranteed Rate, Inc. DBA Citywide Home Mortgage

Categories

Our Location

10591 165th St. West
Lakeville MN, 55044

Connect With Me

This site is not authorized by the New York State Department of Financial Services. No mortgage loan applications for properties located in New York will be accepted through this site. Operating in the state of California as Guaranteed Rate, Inc. D/B/A Citywide Home Mortgage. If you are a California resident, please review our Privacy Policy to learn more about the categories and business purpose of personal information we may collect and your right to opt-out from the sale of personal information.

Applicant subject to credit and underwriting approval. Not all applicants will be approved for financing. Receipt of application does not represent an approval for financing or interest rate guarantee. Refinancing your mortgage may increase costs over the term of your loan. Restrictions may apply. All information provided in this publication is for informational and educational purposes only, and in no way is any of the content contained herein to be construed as financial, investment, or legal advice or instruction. Citywide Home Mortgage does not guarantee the quality, accuracy, completeness or timelines of the information in this publication. While efforts are made to verify the information provided, the information should not be assumed to be error-free. Some information in the publication may have been provided by third parties and has not necessarily been verified by Citywide Home Mortgage. Citywide Home Mortgage, its affiliates and subsidiaries do not assume any liability for the information contained herein, be it direct, indirect, consequential, special, or exemplary, or other damages whatsoever and howsoever caused, arising out of or in connection with the use of this publication or in reliance on the information, including any personal or pecuniary loss, whether the action is in contract, tort (including negligence) or other tortious action.

Coleen TeBockhorst NMLS ID: 274205 Copyright © 1998-2025 Guaranteed Rate, Inc. D/B/A Citywide Home Mortgage. All rights reserved.

For licensing information, go to: www.nmlsconsumeraccess.org.

NMLS License #2611 – 3940 N Ravenswood Chicago, IL 60613. (866) 508-5515. Equal Housing Lender.

Licensing | Privacy | Terms of Use

Copyright © 2026 · Powered by MySMARTblog

Copyright © 2026 · Genesis Sample Theme on Genesis Framework · WordPress · Log in