CTeBockhorst's Blog

The Mortgage and Real Estate Scoop

  • Home
  • About
  • Blog
  • Resources
    • Calculators
    • Download My eGuide Today!
    • First Time Buyer Tips
    • First Time Seller Tips
    • Loan Checklist
    • Loan Process
    • Loan Programs
    • Home Appraisal
    • Home Inspection
    • What to Expect at a Loan Closing: A Step-by-Step Guide
  • Apply
  • Reviews
    • Read My Reviews
    • Zillow Reviews
    • Leave a Review
  • Contact

What To Know About Flood Insurance

October 20, 2022 by Coleen TeBockhorst

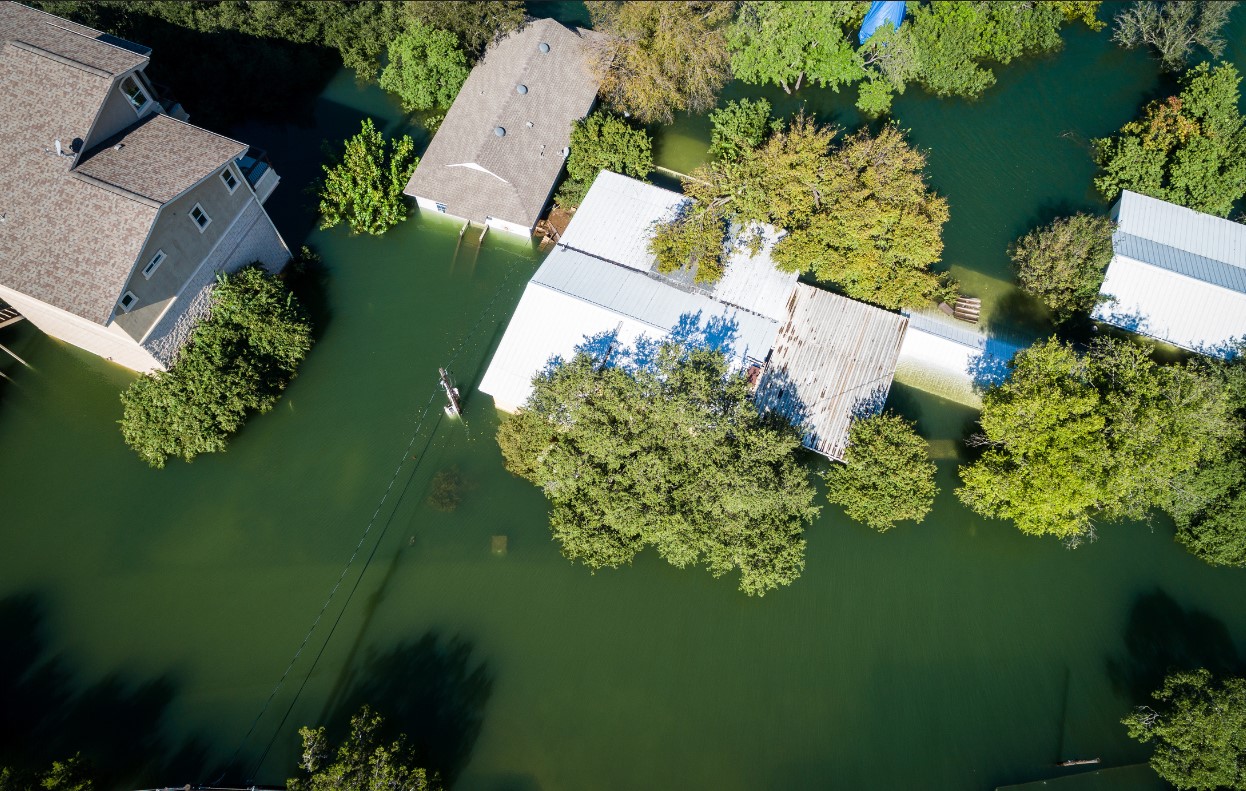
What To Know About Flood InsuranceFlooding can happen in any location at any time. Even though many people associate floods with coastal properties, flooding can take place inland as well. That is why you always need to take a look at the map to figure out whether your property is located in a flood zone. There are some situations where your lender might require you to purchase flood insurance. What do you need to know?

What Is Protected And What Is Not?

When you purchase flood insurance, there are three broad components that you should examine. You need to check and see whether the policy covers the building, the contents of your home, and potential replacement expenses. Flood insurance policies generally insure any physical damage done to your house as well as any belongings you have inside your home. This might include your walls, household appliances, plumbing system, electrical system, clothing, and furniture.

On the other hand, most flood insurance policies do not cover your outdoor structures. For example, they will not protect your patio, swimming pool, fence, or vehicles parked outside the home.

What Is Your Flood Risk Level?

Your flood insurance premium will vary depending on where you are located. For example, if you are in a flood zone, your flood insurance premiums will probably be significantly higher; however, a significant percentage of flood claims occur in areas that are not located in a flood plain. While your premium should be lower, you may want to talk to your real estate agent to see whether it is worth it to purchase flood insurance.

Is Flood Insurance Required?

Flood insurance has its limitations, just like any other insurance policy. Therefore, you might be wondering whether it is required.

If it is required, it would be required by your lender. If your house is located in a flood zone, there is a significant chance that your lender will require you to purchase flood insurance as a requirement for financing. If you refuse to purchase flood insurance, then your lender might refuse to finance your property. You should always compare flood insurance premiums across different companies before you decide which one to go with. Be sure to compare policy coverage options and limitations as well. 
 

Filed Under: Mortgage Tips Tagged With: Flood, Flood Insurance, Insurance

The Top Tips To Get Your Offer Accepted

October 19, 2022 by Coleen TeBockhorst

The Top Tips To Get Your Offer Accepted In A Seller's MarketThe housing market today is very competitive, and you might be wondering how you can get your offer accepted. If the seller has multiple offers on the table, it can be a bit of a challenge. Many people assume that the best way to get an offer accepted is to offer the most money. Even though that is certainly helpful, there are several other tips you should follow to make sure your offer is the one the seller picks.
Get Pre-Approved For A Mortgage

First, you must make sure that you get pre-approved for a mortgage. Unless you are paying cash for the home, you should talk to a local loan officer to get a pre-approval letter. You don’t have to go with that company once the dust settles, but you need to get a pre-approval letter from a lender. That way, the seller will know that you have a high chance of getting approved for the loan.

Offer More Earnest Money

If you are willing to offer more earnest money, that will make the seller more comfortable. The seller is always worried that the buyer might pull out on the offer, meaning that their home will go back on the market. If you increase the amount of earnest money you put down, the seller will feel more confident that you are serious about buying the home.

Give The Seller The Option To Rent Back

If the seller accepts your offer, you will have between four and six weeks before your first mortgage payment is due. Therefore, you won’t have any payments after closing for a while. If the seller is not ready to move yet, or if the seller has not found a new home, offer the seller an opportunity to rent the home back for free. This will give the seller more time to get everything in order before they move. 

Increase The Strength Of Your Offer

In a seller’s market, you need to make your offer stand out. Otherwise, you may have a difficult time finding a house, particularly if you cannot pay cash. If you follow these tips, you can increase your chances of having your offer picked by the seller. 


Filed Under: Mortgage Tips Tagged With: Mortgage Tips, New Home, Purchase Offer

What’s Ahead For Mortgage Rates This Week – October 17, 2022

October 17, 2022 by Coleen TeBockhorst

What's Ahead For Mortgage Rates This WeekLast week’s economic reporting included readings on month-to-month and year-over-year inflation and the minutes of the most recent meeting of the Federal Reserve’s Federal Open Market Committee. The University of Michigan published its preliminary consumer sentiment reading and weekly reports on mortgage rates and jobless claims were also released.
September Inflation Readings Provide No Relief

Inflation rose by a month-to-month pace of  0.40 percent in September as costs for staples including rent, food, and medical care increased. The Fed raised its target interest rate by 0.75 percent. Year-over-year inflation rose by 7.20 percent; this was the highest growth reading since 1982. The Federal Reserve considered a year-over-year rate of two percent inflation to be normal before the pandemic. September grocery prices were 13 percent higher year-over-year and reached their highest growth pace since 1979. Rents rose by 0.80 percent in September and the increase concerned economists who predicted no immediate end to high inflation. Rising rents are particularly significant as rent represents the largest component of most tenants’ budgets.

Core inflation, which excludes volatile food and fuel sectors, reached a 40-year high in September after increasing by 0.60 percent in August. Analysts expected a month-to-month increase of 0.40 percent based on August’s core inflation reading of 0.60 percent.

Year-over-year core inflation dipped to 8.20 percent in September. Analysts expected a reading of 8.10 percent; the year-over-year inflation reading for August 2022 was 8.30 percent. By comparison, the year-over-year core inflation readings for September 2021 were 6.60 percent with an expected reading of 6.50 percent and an August 2021 reading of 6.30 percent.

Mortgage Rates, Jobless Claims Rise

Freddie Mac reported higher average mortgage rates last week as the rate for 30-year fixed-rate mortgages rose by 26 basis points to 6.92 percent. Rates for 15-year fixed-rate mortgages averaged 6.09 percent and were 19 basis points higher. The average rate for 5/1 adjustable rate mortgages rose by 45 basis points to 5.81 percent. Discount points averaged 0.80 percent for 30-year fixed-rate mortgages and 1.10 percent for 15-year fixed-rate mortgages. Discount points for 5/1 adjustable rate mortgages averaged 0.80 percent.

Initial jobless claims rose to 228,000 first-time claims filed as compared to the previous week’s reading of 219,000 initial claim filings. The University of Michigan released its October consumer sentiment index with an index reading of 59.8; analysts expected a reading of 59.0 and September’s index reading was 58.6. Readings over 50 indicate that most index participants surveyed had a positive outlook on current economic conditions.

What’s Ahead

This week’s scheduled economic news includes readings on U.S. housing markets, building permits issued, and housing starts. Sales of previously-owned homes will be reported along with weekly readings on mortgage rates and jobless claims.

Filed Under: Financial Reports Tagged With: Case Shiller, Financial Report, Jobless Claims

A Non-QM Mortgage: What Does This Mean?

October 14, 2022 by Coleen TeBockhorst

A Non-QM Mortgage: What Does This Mean?If you are interested in purchasing a house, you need to review all of the offers available. The vast majority of loan officers are going to talk about something called qualifying mortgages, which is usually shortened to QM. You may be asking, what is a non-qualifying mortgage? This is usually shortened to Non-QM, and it simply means that the loan does not conform with the rules and regulations put in place by the Consumer Financial Protection Bureau, usually shortened to CFPB. What are the differences between a QM and Non-QM mortgage, and which one is right for your needs?
A Qualified Mortgage Generally Provides More Protection

In general, a qualified mortgage (QM) typically provides you with a greater degree of protection. The loan has to conform to certain standards. This means that the loan cannot last longer than 30 years, there cannot be any prepayment penalties, it cannot be a balloon loan, and it should not have any negative amortization features. At the same time, qualifying for a QM mortgage can be more difficult, as lenders have to follow all of the rules and regulations set forth by the government. This includes verifying bank statements, income, W2s, and numerous other examples of documentation.

A Non-QM Mortgage May Provide More Flexibility

You may want to take a look at Non-QM mortgages because they might offer more flexibility. These are very useful for gig workers that do not qualify for QM loans. Another reason is, you might want to lengthen the loan term to 40 years. Or, you might be interested in a loan that only requires you to pay interest, particularly if you are a real estate investor. This is also an option available to foreign nationals who would like to buy property in the United States. On the other hand, you should talk to a professional who can review the risks of a Non-QM mortgage as well.

Find The Best Loan Option For Your Needs

Ultimately, it is critical to review the benefits and drawbacks of each option before you make a decision. The right loan for one person might not necessarily be the right loan for you. If you talk to an expert, you can review all of the options available and put yourself in the best position possible to qualify for a home loan. 


Filed Under: Mortgage Tagged With: Mortgage, Non-QM, Self Employed

Finding The Best Mortgage Deal: What To Do

October 13, 2022 by Coleen TeBockhorst

Finding The Best Mortgage Deal: What To DoYou have worked hard for your money, and you probably want to save as much of it as you possibly can. That means you need to find the best possible mortgage deal you can. What are a few steps you should take if you want to get the best loan terms possible?
1. Get Plenty Of Estimates

You need to get a lot of estimates from different types of lenders. Examples include private mortgage companies, commercial banks, and credit unions. If you have a real estate agent, you may want to see if they can refer you to a loan officer. Many of these institutions have forms you can fill out online. Then, they will give you a custom rate estimate. When you compare rates across institutions, you must make sure you use the same loan terms. For example, you might want to get a 30-year fixed-rate estimate from all of these institutions. 

2. Understand Closing Costs

When you get an estimate back from the lender, they will probably give you the total loan amount, the term (or length) of the loan, and the interest rate; however, you cannot overlook closing expenses. For example, some lenders will charge you a fee just for printing your loan documents. Pay attention to the closing costs and try to remove as many of them as possible.

3. Select A Lender

After reviewing the documents carefully, you should select a lender. Be sure to ask about the rate lock period, which guarantees your interest rate for a certain amount of time. You need to make sure your interest rate will not change before you get to the closing table. You should also ask about prepayment penalties, which refers to penalties you might have to pay for paying off your mortgage early. If you plan on making extra payments toward the principal, try to remove the prepayment penalty.

4. Finalize The Document

Once you are done with the negotiating process, go ahead and finalize the document. You cannot necessarily negotiate appraisal fees or government recording fees, but you can negotiate your closing expenses, interest rate, and points. Once you are done, work with your agent to get to the closing table and start the moving process. 


Filed Under: Mortgage Tagged With: Mortgage, Mortgage Fees, Mortgage Rates

How to Use a Mortgage to Buy a Home After Going Through a Bankruptcy

October 12, 2022 by Coleen TeBockhorst

How to Use a Mortgage to Buy a Home After Going Through a BankruptcyWhile it is sometimes the best option to get your finances repaired, the bankruptcy and following discharge period can be tough. However, while it may delay things for a couple of years, the good news is that even a bankruptcy won’t stop you from borrowing a mortgage to buy a home. In today’s article, we will share some insight into how you can get a mortgage loan after going through bankruptcy.
Step 1: Get A Professional Credit Assessment

Once your Chapter 7 or Chapter 13 bankruptcy has been discharged, you will be required to wait for at least two years before you’re able to take out a mortgage. During this time, it is a good idea to sit down with a credit professional and get an assessment. Individuals and families with a bankruptcy on their credit file are going to go through a bit of extra scrutiny when taking out future loans. So spend a bit of time working on cleaning up your credit.

Step 2: Figure Out Your Monthly Budget

As you move closer to buying a home, you will want to start living off of a monthly budget. This will help to ensure that you are always prepared for your monthly mortgage payments and aren’t left short of cash when payment time comes. A budget can be as simple as a spreadsheet listing your monthly sources of income and expenses. Alternatively, you can use iPhone or Android apps which help to make budget tracking easier.

Step 3: Get Your Down Payment Saved Up

You will also need to start saving for the down payment that you’ll place on your home. The amount that you will need depends on a variety of factors including the city you’re buying in, the size of the home and much more. If you’re unsure about this, contact us and we’ll share some insight.

Step 4: Maintain Your Spending Discipline Until It’s Buying Time

Finally, it’s worth noting that you will need to be very disciplined in the period between your bankruptcy discharge and your mortgage application. Your credit report has to stay clean so that your mortgage lender does not doubt your ability to pay.

Don’t get discouraged if you have some work ahead of you to get your credit repaired. With a little time and effort, you can put your bankruptcy behind you and move on as a happy homeowner. To learn more about the financing process and to discuss your options, contact our team of mortgage professionals today. We’re here to help.

Filed Under: Home Mortgage Tips Tagged With: Home Mortgage Tips, Mortgage, Mortgage Applications

3 Reasons to Hit the Accelerator on Your Mortgage Payments – If You Can Afford It

October 11, 2022 by Coleen TeBockhorst

3 Reasons to Hit the Accelerator on Your Mortgage Payments If You Can Afford ItDoes the thought of repaying your mortgage for the next twenty-plus years leave you feeling a little down? Whether you’ve had your mortgage for weeks or years, accelerating your payments is an excellent option that can help get your mortgage fully paid off in a shorter time frame. Let’s explore three great reasons to accelerate your payments so that your mortgage debt is paid down faster.
You’ll Be Debt-Free That Much Faster

It may seem obvious, but it’s worth stating that you’ll be debt-free that much quicker if you accelerate your repayment schedule. Every extra payment you make against your mortgage debt builds the amount of equity you own in your home. So not only are you becoming more debt-free with each payment, but you’re also building your net worth. And while it’s true that you might only shave a year or two off of your 25-year mortgage period, being debt-free faster is still worth the effort.

You’ll Pay Less Interest

With most mortgages, any extra payments that you make will go straight towards your ‘principal’ balance. Getting the principal paid down faster means that you’ll end up paying less in interest than if you hadn’t. If you consider that every year you shave off of a 20-year amortization period is a full year of interest that you won’t have to pay, it adds up. Note that if you have an existing mortgage agreement, you’ll need to check the terms to determine the rules around extra principal payments.

You’ll Have More Financial Freedom

Finally, the faster you get your mortgage paid off, the more financial freedom you’ll have. The equity and credit you’ve built over time will also provide you with some options. You can invest in buying an investment property, or in taking out a line of credit to renovate and upgrade your current home. If the numbers make sense, you can also borrow against your home equity to invest in the financial markets. This will diversify your investment portfolio and expand your net worth.

As you can see, it’s well worth the financial investment to accelerate your mortgage repayment. If you can afford it and it won’t significantly lower your quality of life. If you have questions about a mortgage new or existing, contact our team of mortgage professionals. We’re happy to help.

Filed Under: Home Mortgage Tips Tagged With: Home Mortgage Tips, Mortgage, Mortgage Payments

What’s Ahead For Mortgage Rates This Week – October 10, 2022

October 10, 2022 by Coleen TeBockhorst

What's Ahead For Mortgage Rates This Week - October 10, 2022Last week’s economic reporting included readings on construction spending, public and private sector job growth, and the national unemployment rate. Weekly readings on mortgage rates and jobless claims were also released.
Construction Spending Falls in August

The Commerce Department reported less construction spending in August as spending fell by -0.70 percent to $1.78 trillion as compared to July’s reading of $1.79 trillion. August construction spending was lower than the expected reading of -0.20 percent and July’s revised construction spending reading of -0.60 percent. Year-over-year construction spending rose by 8.50 percent.

Mortgage Rates Mixed, Jobless Claims Rise

Freddie Mac reported lower fixed mortgage rates last week as the average rate for 30-year fixed-rate mortgages dropped by four basis points to 6.66 percent. The average rate for 15-year fixed-rate mortgages fell by six basis points to 5.90 percent and the average rate for 5/1 adjustable rate mortgages rose by six basis points to 5.36 percent.

Discount points averaged 0.80 percent for 30-year fixed-rate mortgages and 1.00 percent for 15-year fixed-rate mortgages. Discount points for 5/1 adjustable rate mortgages averaged 0.30 percent.

 Higher-than-expected jobless claims were reported last week with 219,000 initial claims filed. Analysts expected  203,000 new claims to be filed and the previous week’s reading was 190,000 first-time jobless claims filed. Continuing jobless claims were also higher with 1.36 million jobless claims filed as compared to 1.35 million ongoing claims filed during the previous week. Rising jobless claims suggest that layoffs are increasing.

The federal government also released month-to-month readings for public and private sector job growth and the national unemployment rate. Non-farm payrolls rose by 263,000 jobs in September, which fell short of the expected reading of 275,000 jobs added and the previous month’s reading of 315,000 jobs added. The national unemployment rate fell to 3.50 percent in September as compared to August’s reading of 3.70 percent and the expected reading of 3.70 percent.

ADP reported that 208,000 private-sector jobs were added in September as compared to August’s reading of 185,000 jobs added; Analysts expected 200,000 jobs added, which was revised from initial expectations of 132,000 jobs added. Nela Richardson, the chief economist at ADP, said that reopened schools and childcare providers supported parents’ ability to return to work after pandemic shutdowns.

What’s Ahead

This week’s scheduled economic reporting includes readings from the Fed’s Federal Open Market Committee, readings on retail sales, and the University of Michigan’s initial monthly report on consumer sentiment. 

Filed Under: Financial Reports Tagged With: Financial Report, Jobless Claims, Mortgage Rates

Current Servicemember or Veteran? 4 Reasons Why a VA Home Loan Is an Excellent Choice

October 7, 2022 by Coleen TeBockhorst

Current Servicemember or Veteran? 4 Reasons Why a VA Home Loan Is an Excellent ChoiceAre you current or former member of the US military service who is looking to buy a new home? If so, you will be pleased to know that there are some special mortgage programs that are open to you. Let’s take a look at five reasons why a mortgage backed by the Department of Veterans Affairs is an excellent choice when buying your new home.
You Can Borrow Up To 100% Of The Home’s Value

You read that correctly! VA-backed mortgages are available to you even if you choose to put no money towards your down payment. This can be a huge benefit for those individuals and families who are looking to buy a new home but don’t have a large chunk of cash on hand to fund the down payment. Instead, you can work with your VA mortgage advisor to get financing for the entire purchase price of your home.

You Can Qualify For A ‘Jumbo’ Loan

Depending on the real estate market in your city, the size of home you need and how luxurious you want it, you may need a larger mortgage. The great news is that there are ‘jumbo’ options available with VA-backed home loans. In some cases, you may qualify for over $1 million in mortgage financing, which is likely to put most homes in your area within reach.

You Can Avoid Mortgage Insurance Fees

Home buyers using a conventional mortgage with less than 20 percent down are typically required to buy private mortgage insurance or “PMI.” However, this is not a requirement with VA-backed mortgages. If you qualify for a VA home loan, this can save you a significant amount of money over the loan’s term.

You Can Accelerate Your Payments At No Cost

If you decide that you want to pay your VA mortgage off a bit faster by accelerating your payments, you can do so without incurring fees or penalties. For example, if you are gifted a large sum of money or have a significant income tax return, you can contribute that amount directly against your mortgage.

These are just a few of the many great reasons to explore using a VA-backed mortgage to fund your next home purchase. For more information about VA home loans and to see if you qualify, contact your trusted mortgage professionals today.

Filed Under: Home Mortgage Tips Tagged With: Home Mortgage Tips, Mortgage, VA Loans

What Are Conditional Approvals?

October 6, 2022 by Coleen TeBockhorst

What Are Conditional Approvals?As you take a look at potential houses for sale, what does it mean if you see a house with a conditional approval? Does that mean you can swoop in and purchase the house with a better offer? Even though a conditional approval doesn’t mean that the sale is guaranteed to go through, it does mean that an agreement is in place.

An Overview Of A Conditional Approval

A conditional approval is an informal acknowledgement that an agreement is in place between a buyer and the lender; however, the lender typically has to collect additional financial information to show that the house is a solid buy. If this process falls through, the house may go back on the market. 

For example, the lender might require an appraisal before financing the house. If the appraisal comes in too low, then the buyer might have to bring additional cash to the table. Otherwise, the lender might refuse to finance the house, meaning that it will go back on the market. Or, the lender might require the buyer to submit additional financial information to show they can afford the home. If they cannot do so, the financing process might fall through.

Is A Conditional Approval The Same As A Pre-Approval?

Even though the terms are similar, they are not the same. A conditional approval is not the same as a pre-approval. The pre-approval process takes place very early in the mortgage application process. The pre-approval process is important because it gives the seller some confidence that the buyer can afford the house; however, a conditional approval process is more formal and takes place much further along in the application process.

What Is Required For A Lender’s Conditional Approval?

The conditional approval is only granted after the applicant has submitted an offer on a property. Some of the documents that the buyer might have to submit include financial statements, income statements, tax returns, explanations of negative credit report items, and evidence of any debt or liabilities.

Once all this information is collected, the lender will decide whether to grant the buyer conditional approval. This could help the buyer lock in his or her agreement before proceeding with the other steps in the mortgage application process. 


Filed Under: Mortgage Tagged With: Conditional Approval, Mortgage, Mortgage Tips

« Previous Page
Next Page »

Contact Coleen

Coleen Tebockhorst

Coleen TeBockhorst
coleen.tebockhorst@citywidehm.com

Senior Loan Officer

Call me! (612) 701-8512

NMLS #274205

Download My Mortgage eGuide today

CW Home Mortgage logo_White

Guaranteed Rate, Inc. DBA Citywide Home Mortgage

Categories

Our Location

10591 165th St. West
Lakeville MN, 55044

Connect With Me

This site is not authorized by the New York State Department of Financial Services. No mortgage loan applications for properties located in New York will be accepted through this site. Operating in the state of California as Guaranteed Rate, Inc. D/B/A Citywide Home Mortgage. If you are a California resident, please review our Privacy Policy to learn more about the categories and business purpose of personal information we may collect and your right to opt-out from the sale of personal information.

Applicant subject to credit and underwriting approval. Not all applicants will be approved for financing. Receipt of application does not represent an approval for financing or interest rate guarantee. Refinancing your mortgage may increase costs over the term of your loan. Restrictions may apply. All information provided in this publication is for informational and educational purposes only, and in no way is any of the content contained herein to be construed as financial, investment, or legal advice or instruction. Citywide Home Mortgage does not guarantee the quality, accuracy, completeness or timelines of the information in this publication. While efforts are made to verify the information provided, the information should not be assumed to be error-free. Some information in the publication may have been provided by third parties and has not necessarily been verified by Citywide Home Mortgage. Citywide Home Mortgage, its affiliates and subsidiaries do not assume any liability for the information contained herein, be it direct, indirect, consequential, special, or exemplary, or other damages whatsoever and howsoever caused, arising out of or in connection with the use of this publication or in reliance on the information, including any personal or pecuniary loss, whether the action is in contract, tort (including negligence) or other tortious action.

Coleen TeBockhorst NMLS ID: 274205 Copyright © 1998-2025 Guaranteed Rate, Inc. D/B/A Citywide Home Mortgage. All rights reserved.

For licensing information, go to: www.nmlsconsumeraccess.org.

NMLS License #2611 – 3940 N Ravenswood Chicago, IL 60613. (866) 508-5515. Equal Housing Lender.

Licensing | Privacy | Terms of Use

Copyright © 2026 · Powered by MySMARTblog

Copyright © 2026 · Genesis Sample Theme on Genesis Framework · WordPress · Log in