 Buying a home, a car, or any significant investment often involves making a down payment. The down payment is a crucial part of the purchasing process, as it can impact your loan terms, interest rates, and monthly payments. But how much should you save for a down payment, and why is it so important?
Understanding Down Payments
A down payment is a portion of the purchase price that you pay upfront when buying a house, a car, or making a large investment. It’s a way to demonstrate your commitment to the purchase and reduce the risk for the lender or seller. Down payments are commonly associated with:
Homebuying: When purchasing a home, a down payment is typically required by mortgage lenders. The amount can vary but is often around 20% of the home’s purchase price.
Car purchases: Down payments for cars can also range, but they often hover around 10-20% of the vehicle’s price.
Large investments: In other scenarios, such as starting a business or investing in a big-ticket item, a down payment may be necessary to secure financing.
Importance of Down Payments
Lowering Monthly Payments: A larger down payment reduces the amount you need to finance, resulting in lower monthly payments. This can make your financial burden more manageable in the long run.
Qualifying for Loans: A substantial down payment can help you qualify for loans with more favorable terms and lower interest rates. Lenders often see a larger down payment as a sign of financial stability.
Building Equity: With a significant down payment, you’ll start building equity in your asset from day one. Equity is the portion of the property or asset you own, and it can grow over time, giving you more financial security.
How Much Should You Save for a Down Payment?
The ideal down payment amount can vary based on what you’re buying and your financial situation. Here are some general guidelines:
Homes: As mentioned earlier, a down payment of 20% is often recommended for purchasing a home. However, there are mortgage options that allow for lower down payments, such as FHA loans, which require as little as 3.5% down. The key is to balance a lower down payment with the added cost of private mortgage insurance (PMI) and potentially higher interest rates.
Cars: For buying a car, a down payment of 10-20% is a good range to aim for. This will help reduce the overall cost of the car loan and lower your monthly payments.
Large Investments: The down payment for investments can vary widely, so it’s essential to assess your specific financial goals and risks. In this case, consult with a financial advisor to determine the right amount.
How to Save for a Down Payment
Saving for a down payment may seem daunting, but with a clear plan, it’s achievable. Here are some steps to help you get started:
Create a Budget: Review your finances, set a budget, and identify areas where you can cut back on spending to save more.
Open a Dedicated Savings Account: Consider opening a separate savings account exclusively for your down payment fund. This will help you track your progress and keep the money out of sight and out of mind.
Automate Savings: Set up automatic transfers from your checking account to your down payment savings account. This ensures that you save consistently.
Increase Income: Explore opportunities to increase your income, such as taking on a part-time job or freelancing, to boost your savings rate.
Reduce Debt: Pay down high-interest debts like credit cards to free up more money for saving.
The role of down payments in major purchases cannot be overstated. They play a vital role in reducing the financial burden of loans, helping you secure better loan terms, and building equity in your assets. While the ideal down payment amount can vary, it’s essential to set a clear savings goal and follow a strategic plan to achieve it. With discipline and patience, you can save for a down payment and take a significant step toward achieving your financial goals.
 The contemporary trend towards expansive dimensions is palpable in various aspects of modern life. Oversized soft drinks, large fast-food meals, and expansive smartphones have become ubiquitous. However, one unlikely sector experiencing a similar trend is the realm of mortgages.
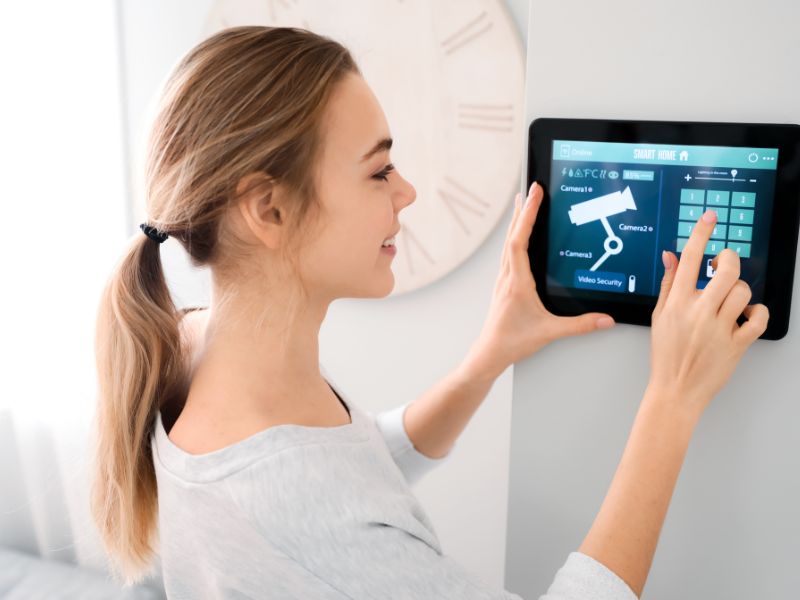 Home is where the heart is, and it’s also where you should feel the safest. Ensuring the security of your home has never been more attainable. Home security systems have evolved from simple locks and alarms to sophisticated, interconnected networks that provide round-the-clock protection. We will explore the latest innovations and timeless strategies to keep your home safe and secure.
 It’s easy to get Private Mortgage Insurance (PMI) confused with homeowners’ insurance, but PMI is an entirely different thing that may or may not be necessary when it comes to your home purchase. If you’re going to be investing in a home in the near future and are wondering what PMI may mean for you, here are some things to consider regarding this type of insurance.
 The trade deficit dropped significantly this month, resulting in the smallest gap in the last 16 years. This has been entirely driven by the ongoing gold rush and, to a much less impactful degree, businesses working their way around high tariffs. The unemployment reports, however, have shed another light, showing a steady trend of unemployment rising and reaching a four-year high as of last week.
 When you are preparing to buy a home, it is natural to want your credit profile to look clean and organized. Many buyers think closing old credit accounts will improve their score, simplify their finances, and make them appear more responsible to lenders. In reality, closing old accounts can have the opposite effect. Those accounts play a much bigger role in your credit profile than most people realize and shutting them down can create sudden changes that impact your mortgage approval.
 Fractional homeownership is becoming more popular as buyers look for creative ways to enjoy a second home or vacation property without taking on the full cost. Instead of owning one home entirely, you purchase a fraction of the property and share ownership with several other people. While the idea sounds simple, fractional ownership comes with unique rules, financing challenges, and long-term commitments that every buyer should understand before moving forward.
 Buying a home when you have young kids brings unique challenges, but it also creates opportunities to build stability for your family. Your priorities might look different from other homebuyers, and your financial decisions may need to reflect the needs of a growing household. By planning ahead and understanding what matters most, you can choose a mortgage that supports your budget, your lifestyle, and your long-term goals as a parent.
 More people are earning money through freelancing, side gigs, digital work, consulting, and online sales. Because of this, it is common for income to flow through platforms like Venmo, Cash App, or PayPal instead of traditional direct deposits. While these tools make it easy to get paid, they can also affect your mortgage application in ways many buyers do not expect. Understanding how lenders view these platforms can help you prepare long before you apply for a home loan.