 Using online mortgage lenders can offer several advantages and disadvantages compared to traditional brick-and-mortar lenders. It’s important to weigh these factors based on your individual preferences, needs, and financial situation. Here’s a breakdown of the pros and cons:
Advantages of Online Mortgage Lenders:
Convenience:
Pros: Online lenders offer the convenience of applying for a mortgage from the comfort of your home at any time. The entire process, from approval application, can be done online, reducing the need for in-person visits.
Faster Approval Process:
Pros: Online lenders often have streamlined processes, leveraging technology to speed up the approval process. This can result in quicker loan approvals and faster closings compared to traditional lenders.
Competitive Interest Rates:
Pros: Online lenders may have lower operating costs, allowing them to offer competitive interest rates. Borrowers can potentially save money over the life of the loan by securing a lower rate.
Wide Range of Loan Options:
Pros: Online lenders often offer a variety of loan products and terms, allowing borrowers to choose the option that best suits their financial situation and goals.
Accessible Information:
Pros: Online lenders typically provide a wealth of information on their websites, making it easy for borrowers to compare rates, terms, and fees. This transparency can empower borrowers to make informed decisions.
Disadvantages of Online Mortgage Lenders:
Limited Personal Interaction:
Cons: Some borrowers may prefer face-to-face interactions with a loan officer or advisor, especially when dealing with a significant financial decision like a mortgage. Online lenders may lack the personal touch of in-person service.
Potential for Miscommunication:
Cons: Online communication may lead to misunderstandings, especially if there is a lack of clarity in the application process. Miscommunication can potentially delay the loan approval or closing process.
Less Flexibility for Special Cases:
Cons: Online lenders may have strict criteria, and their automated processes might not accommodate special cases or unique financial situations as well as a human underwriter might. Borrowers with complex financial profiles may face challenges.
Security Concerns:
Cons: Some borrowers may have concerns about the security of their personal and financial information when dealing with online transactions. It’s crucial to choose reputable online lenders with strong security measures in place.
Limited Local Market Knowledge:
Cons: Online lenders may not have the same level of local market knowledge as traditional lenders. This can be a disadvantage if local market conditions significantly impact the mortgage process.
In summary, the decision to use an online mortgage lender versus a traditional lender depends on individual preferences and priorities. Borrowers should carefully evaluate the pros and cons of each option, considering factors such as convenience, communication preferences, and the complexity of their financial situation.
Additionally, researching and choosing a reputable online lender with a track record of customer satisfaction is crucial to a positive borrowing experience.
 Owning a home is a significant milestone that comes with a multitude of financial considerations. Beyond the pride of homeownership, there are substantial tax benefits and deductions available to those who embark on this journey. We will explore key facts about mortgages and taxes, focusing on the deductions, credits, and benefits that can make homeownership a financially savvy decision.
 Mortgage insurance can make homeownership accessible with a smaller down payment, but many homeowners eventually wonder whether it can be removed. The answer depends on the type of mortgage you have, your loan balance, property value, payment history, and the rules that apply to your specific loan.
 When buying a home, it is natural to assume that putting as much money down as possible is always the best financial decision. A larger down payment can provide meaningful advantages, but it also affects more than the size of your monthly mortgage payment. Understanding the broader impact can help you decide how much cash makes sense to use at closing.
 Getting approved for a mortgage can be exciting, especially when you discover how much financing may be available to you. But the maximum amount you qualify to borrow and the amount you are personally comfortable spending are not necessarily the same. Understanding the difference can help you choose a home that supports your lifestyle as well as your finances.
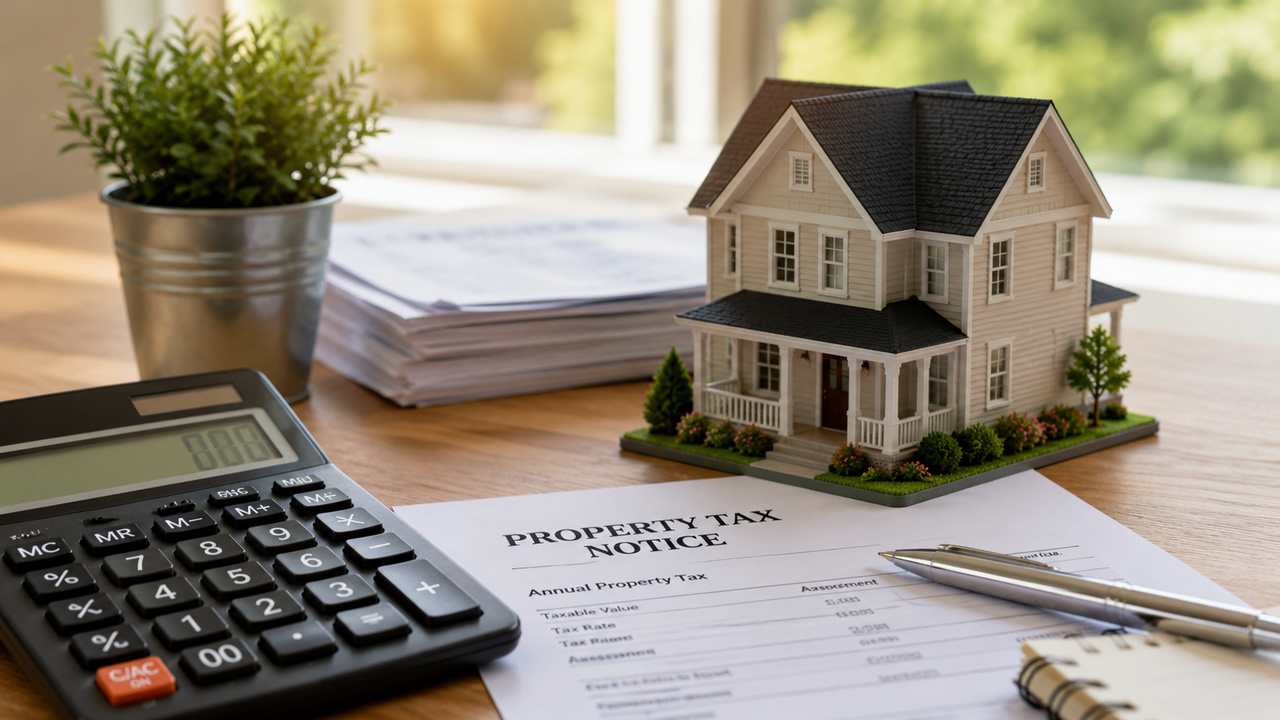 A fixed-rate mortgage provides predictability because your interest rate and principal-and-interest payment remain consistent. However, that does not necessarily mean your total monthly housing payment will stay exactly the same. Property taxes can change over time, and when they do, homeowners who pay taxes through an escrow account may see their monthly mortgage payment change as well.
 Homeownership can be rewarding, but it also introduces expenses and responsibilities that are easy to underestimate. A few consistent financial habits can make those responsibilities feel far more manageable. The goal is not to predict every cost perfectly, but to create enough preparation and flexibility to handle routine bills and unexpected surprises with confidence.
 Home equity is the difference between what your home is worth and what you currently owe on it. It can become one of the most meaningful financial benefits of homeownership, but it usually develops gradually rather than all at once. Understanding how equity grows can help you track your progress and make more informed long-term financial decisions.
