CTeBockhorst's Blog

The Mortgage and Real Estate Scoop

  • Home
  • About
  • Blog
  • Resources
    • Calculators
    • Download My eGuide Today!
    • First Time Buyer Tips
    • First Time Seller Tips
    • Loan Checklist
    • Loan Process
    • Loan Programs
    • Home Appraisal
    • Home Inspection
    • What to Expect at a Loan Closing: A Step-by-Step Guide
  • Apply
  • Reviews
    • Read My Reviews
    • Zillow Reviews
    • Leave a Review
  • Contact

What’s Ahead For Mortgage Rates This Week – October 7th, 2024

October 7, 2024 by Coleen TeBockhorst

Last week was a fairly light week, with the non-farm payroll data being the most significant release. The data showed that payrolls are growing at a faster rate than historical trends suggest, which could indicate that inflation is still above the Federal Reserve’s target. In contrast, the upcoming week has a busy schedule, with many important economic releases lined up back to back.

Non-Farm Payrolls

Hourly pay for American workers rose a sharp 0.4% in September – above expectations – to put the increase over the past 12 months at 4.0%. That’s up from 3.9% in the prior month. Wages are rising faster compared to the last few years before the pandemic. Wage gains rose just slightly over 3% on average in 2018 and 2019 before the coronavirus exploded.

If wages keep growing at a 4% rate, it could call into question the Fed’s view that labor costs will remain non-inflationary.

Primary Mortgage Market Survey Index

  • 15-Yr FRM rates saw an increase of 0.09% with the current rate at 5.25%
  • 30-Yr FRM rates saw a decrease of 0.04% with the current rate at 6.12%

MND Rate Index

  • 30-Yr FHA rates saw a 0.25% increase for this week. Current rates at 6.04%
  • 30-Yr VA rates saw a 0.26% increase for this week. Current rates at 6.06%

Jobless Claims

Initial Claims were reported to be 225,000 compared to the expected claims of 220,000. The prior week landed at 219,000.

What’s Ahead

Next week will be a heavy week, starting with key inflation reports like the CPI and PPI. These will be followed by the FOMC Minutes, Consumer Credit data, and the University of Michigan Consumer Sentiment report.
Filed Under: Financial Reports Tagged With: Financial Report, Jobless Claims, Mortgage Rates

How to Get a Mortgage Without a Credit Score

October 4, 2024 by Coleen TeBockhorst

Getting a mortgage without a credit score may seem like a tough task, but it is possible. Many assume that a credit score is a must, but if you don’t have one, you can still pursue your dream of homeownership. Here’s how.
What is a Credit Score?

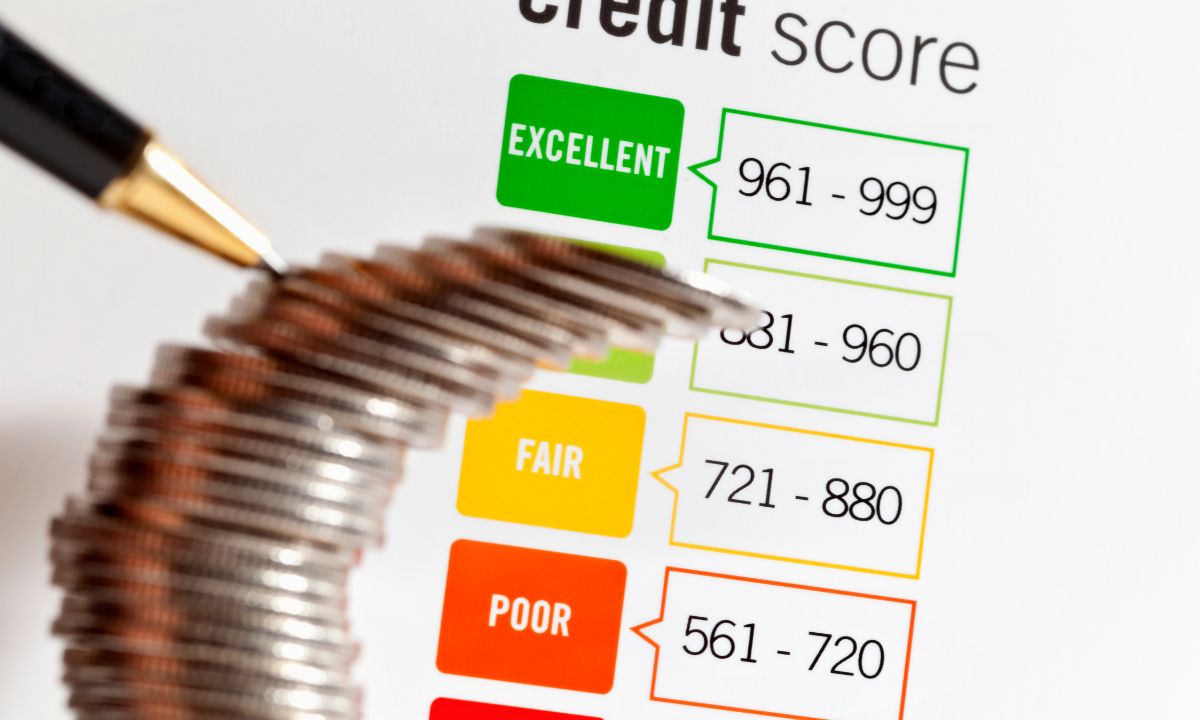
A credit score is a numerical value that shows how well you manage debt. The score is based on factors like your payment history, how long you’ve had credit, and how much credit you’re using. Higher credit scores typically mean better mortgage terms, including lower interest rates.

Loans Without a Credit Score

If you don’t have a credit score, it’s not the end of the road for a mortgage. While many lenders are cautious about lending to people without a credit history, there are still options available. Some government-backed loans, such as FHA, VA, and USDA loans, accept applicants without a credit score. Additionally, certain conventional loans with a large down payment or shorter terms may also be accessible.

The Underwriting Process

Without a traditional credit score, lenders will need to evaluate your creditworthiness using non-traditional credit sources. Lenders typically ask for four forms of alternative credit to show that you can reliably make payments. These could include rent payments, utility bills, phone bills, insurance premiums, and even school tuition.

Once all the documentation is submitted, the underwriting process can take longer than it would for someone with a standard credit history—potentially up to 60 days or more. Since manual evaluation is involved, it’s important not to commit to any home purchase without contingencies for funding approval.

How to Build Credit

If getting a mortgage without a credit score proves challenging, you can start building a credit profile. Opening a credit card and responsibly managing it by paying off balances in full each month is a good start. Keeping your credit usage under 30% of the credit limit can help build a strong credit score over time.

While having no credit score can make the mortgage process more complex, it’s not impossible to secure a home loan. By providing alternative forms of credit or working on building your credit, you can still achieve homeownership.

Filed Under: Credit Scoring Tagged With: FHA Loan, Mortgage Without Credit, No Credit Score

Do VA Entitlements Ever Expire?

October 3, 2024 by Coleen TeBockhorst

The VA home loan program is one of the most valuable benefits offered to those who have served in the U.S. military, providing veterans and active-duty personnel with access to favorable mortgage terms. One common question is whether these VA entitlements ever expire.
What is VA Home Loan Entitlement?

VA home loan entitlement refers to the amount the Department of Veterans Affairs guarantees to a lender if the borrower defaults on the loan. This guarantee significantly reduces the lender’s risk, which allows veterans to access zero down payments and lower interest rates. The VA doesn’t issue the mortgage itself but backs loans made by private lenders.

VA entitlements come in two forms:

  • Basic Entitlement: In 2023, the basic entitlement is typically around $36,000 or 25% of the loan amount, whichever is less. Veterans can use this entitlement multiple times as long as they meet eligibility requirements.
  • Bonus Entitlement (Second-Tier Entitlement): For higher-cost homes, veterans can access additional entitlement beyond the basic amount. This helps veterans secure larger loans in areas where housing prices exceed the standard limit.

Does VA Entitlement Expire?

The short answer is no. Once a veteran is eligible for the VA home loan program, they keep that entitlement for life. There is no expiration date for using it, making it a long-term benefit that veterans can tap into at any time during their lives.

Restoring Loan Entitlement

Veterans who have used their VA entitlement in the past but have paid off their loans or sold their home can have their entitlement restored. This gives them the flexibility to use a VA loan again, although certain conditions apply depending on the situation. Veterans should consult the VA or a lender to understand the specific process for restoring their entitlement.

What About Foreclosure?

In the event of a foreclosure, veterans may lose their entitlement. However, the VA allows for entitlement restoration under certain conditions. If a veteran repays the VA for any losses or sets up a repayment plan, they can regain their eligibility.

VA entitlements are an incredible financial resource for veterans and active-duty service members, providing flexibility and long-term benefits with no expiration. Whether you’re buying a home for the first time or looking to use your entitlement again, this benefit is there when you need it.

Filed Under: Mortgage Tagged With: Mortgage Entitlement , VA Home Loans, Veterans Benefits

Steps to Take Now to Build Your Credit for a Home Purchase Next Year

October 2, 2024 by Coleen TeBockhorst

If you’re thinking about buying a new home next year, there’s one important factor to consider before you start browsing listings—your credit score. A strong credit score can make a huge difference in the interest rates you will qualify for and can also determine your mortgage approval. Starting the process of improving your credit now gives you a head start, putting you in a better position to achieve your homeownership goals when the time comes.
Here are five steps to help you get started:

1. Check Your Credit Report

Before anything else, it’s essential to know where you stand. Request a copy of your credit report from the major credit bureaus. This will allow you to review your current score, see if there are any inaccuracies, and understand what areas need improvement. If you find any errors, dispute them immediately to avoid negative impacts on your score.

2. Pay Down Debt

The amount of debt you carry compared to your total credit limits is one of the most significant factors affecting your credit score. Begin by paying down your highest-interest debts first while making consistent payments on the rest. Reducing your credit utilization rate to below 30% can boost your score significantly over time.

3. Avoid New Credit Lines

Opening new lines of credit right before applying for a mortgage can raise red flags for lenders. Each new account can lower your average account age, which impacts your score. Focus on managing your existing accounts responsibly rather than seeking new credit.

4. Set Up Automatic Payments

Late or missed payments can hurt your credit score and are recorded for up to seven years. Setting up automatic payments ensures you’re never late on bills, which will help build a strong, consistent payment history. This habit can steadily improve your score and show lenders you’re a responsible borrower.

5. Stay Patient and Consistent

Improving your credit score is a gradual process, so the sooner you start, the better. Even small, consistent actions over the next several months will help you make significant progress. The goal is to have your credit in top shape by the time you’re ready to apply for a mortgage.

Why Good Credit Matters for Your Mortgage

A higher credit score can not only help you get approved for a mortgage but also potentially save you thousands of dollars over the life of your loan. Lenders use your score to gauge the risk of lending to you, and a better score usually means lower interest rates and more favorable loan terms.

Conclusion

If a new home is on your radar for next year, preparing your finances now can make a world of difference. Take the time to check and improve your credit score today. Your future self will thank you when you’re settling into your dream home with a manageable mortgage.

Filed Under: Credit Scoring Tagged With: Credit Score, Credit Tips, Mortgage Ready

How Much Equity Can You Borrow Today?

October 1, 2024 by Coleen TeBockhorst

Your home equity represents one of your most valuable assets. When it comes to borrowing against that equity, many homeowners question how much can they borrow. Understanding the amount of equity you can tap into today is essential, especially if you’re considering a home equity loan or line of credit (HELOC) for major expenses like home improvements, debt consolidation, or other financial needs.
What is Home Equity?

Home equity is the difference between your home’s current market value and the outstanding balance on your mortgage. As you pay down your mortgage and your property’s value increases, your equity grows. The more equity you have, the more borrowing power you hold.

Factors That Determine How Much You Can Borrow

When borrowing against your equity, lenders typically allow you to access up to 85% of your home’s value, minus what you owe on your mortgage. This percentage is known as your Loan-to-Value (LTV) ratio. For example, if your home is worth $500,000 and you still owe $250,000, you may be able to borrow up to $175,000 (85% of $500,000 is $425,000, and subtracting the $250,000 mortgage leaves you with $175,000 in available equity).

Lenders will also consider your credit score, income, and current debt levels when deciding how much equity they are willing to lend.

Types of Equity Loans

There are two primary ways to borrow against your home’s equity:

  1. Home Equity Loan: A lump-sum loan with a fixed interest rate, repaid over a set term.
  2. Home Equity Line of Credit (HELOC): A revolving credit line that you can draw from as needed, often with a variable interest rate.

Benefits of Borrowing Against Equity

Borrowing against your home’s equity can offer several advantages, including:

  • Lower Interest Rates: Since these loans are secured by your property, they often have lower interest rates compared to personal loans or credit cards.
  • Tax Benefits: In some cases, the interest you pay on home equity loans may be tax-deductible. Check with a tax professional for details.
  • Flexible Uses: Whether it’s for home renovations, education costs, or debt consolidation, using your home’s equity gives you financial flexibility.

Key Considerations Before Borrowing

Before tapping into your home’s equity, it’s important to weigh the risks:

  • Increased Debt: Borrowing against your home increases your overall debt, which could affect your financial stability if not managed wisely.
  • Risk of Foreclosure: Failing to repay a home equity loan or HELOC could put your home at risk of foreclosure.
  • Market Fluctuations: If home values decline, you could owe more than your home is worth, making it difficult to sell or refinance.

Is Now the Right Time to Borrow?

With interest rates fluctuating, it’s a good idea to consult with a mortgage professional to explore your options. They can help you determine whether borrowing against your equity makes sense for your current financial situation.

If you’re thinking about using your home’s equity, understanding how much you can borrow is the first step. Contact us today to discuss your unique situation and get tailored advice on how to make the most of your home’s value.

Filed Under: Home Mortgage Tagged With: HELOC, Home Equity, Mortgage Tips

What’s Ahead For Mortgage Rates This Week – September 30th, 2024

September 30, 2024 by Coleen TeBockhorst

With the release of the PCE Index data, we are seeing the trend hold as inflation continues to slow down. This gives the Federal Reserve room to continue its rate cuts in the future. Following the positive news for inflation data, the GDP has also seen a larger-than-expected growth of 3% this quarter. The only data running against the tide is the Consumer Confidence reports, which reported to show that consumers are at their most anxious since 2021. We should expect a greater impact on the lending and broader markets ahead of the elections.
PCE Index

The Federal Reserve’s preferred PCE index inched up just 0.1% last month, the government said Friday. This matched the forecast of economists polled by The Wall Street Journal. The increase in inflation in the past 12 months slipped 2.2% from 2.5%, marking the lowest level since early 2021. The Federal Reserve is aiming to bring inflation down to 2% a year.

GDP Estimates (second)

The last of three updates on U.S. growth in the second quarter showed the economy expanded at a solid 3.0% annual pace — and there’s no sign it has taken a big turn for the worse. Gross domestic product, the official scorecard of the economy, was unchanged from the prior 3.0% estimate, the government said Thursday.

Consumer Confidence

Consumer confidence fell in September to a three-month low ahead of a pivotal U.S. election whose outcome could hinge on which presidential candidate voters think will do a better job on the economy. Americans were more worried about the job market in light of a steady rise in unemployment and greater difficulty in finding work. Another source of distress was the high cost of living after several years of severe inflation.

Primary Mortgage Market Survey Index

  • 15-Yr FRM rates saw an increase of 0.01% with the current rate at 5.16%
  • 30-Yr FRM rates saw a decrease of -0.01% with the current rate at 6.08%

MND Rate Index

  • 30-Yr FHA rates saw a 0.09% increase for this week. Current rates at 5.79%
  • 30-Yr VA rates saw a 0.08% increase for this week. Current rates at 5.80%

Jobless Claims

Initial Claims were reported to be 218,000 compared to the expected claims of 223,000. The prior week landed at 222,000.

What’s Ahead

Up next are the non-farm payrolls, a key indicator of the economy that shows whether wages are keeping up with inflation. Additionally, there will be production estimates from the Manufacturing Index and the usual job data releases.

Filed Under: Financial Reports Tagged With: Financial Report, Jobless Claims, Mortgage Rates

VA vs FHA vs USDA What’s the Difference?

September 27, 2024 by Coleen TeBockhorst

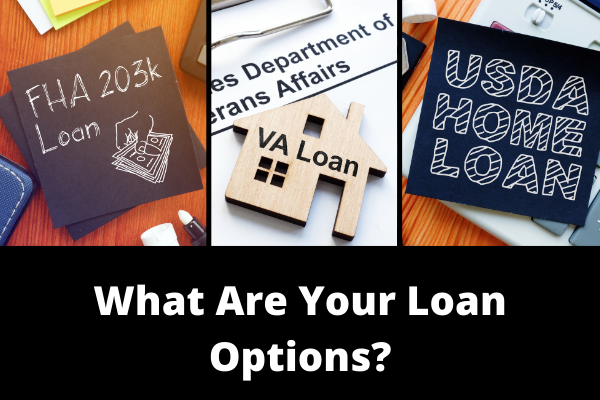
VA vs FHA vs USDA What's the Difference?You may have more options than you think when it comes to securing a mortgage for your new home. While many buyers opt for conventional financing, another option or program might be a better choice for you, depending on your personal and financial situation. Learning more about FHA, USDA, and VA loans ensures you get the best possible deal for your mortgage and that you secure the loan that you need for your new home. Here’s what you need to know about these useful mortgage options.
FHA Loans
These are traditional mortgages that are backed by the FHA: when you take out an FHA loan, this government agency is insuring the loan. This makes your loan more appealing to lenders who might otherwise feel your credit or income history is not strong enough. An FHA loan is available to a wide range of buyers and price points and offers a low-down payment, reasonable interest, and other perks that make it worth exploring for your next mortgage. 

VA Loans
If you are a veteran then this program, which offers loans insured by the VA, is a great option for you as they do not require money down so you can buy immediately, rather than saving for years for a down payment. The VA loan is available to those who have served or are serving in the armed forces and is a good option to help you get the home you want with no money down, unlike a conventional mortgage loan.

USDA Loans
One of the most useful and often overlooked loan programs is from the USDA. While this government office offers direct loans, far more people qualify for their insured loan programs. USDA loans are for rural areas, but a surprising number of suburban communities and locations qualify as well. With a low-down payment and interest, this subsidized loan program is well worth it if you plan to live in a rural or suburban area. 

Not every borrower will qualify for the mortgage options above; the USDA has guidelines on income and the home you are interested in. The FHA does not have income requirements, but you will need to prove your income and this option also has a loan limit.  If you do meet the guidelines of any of the above programs, they can help you access the home you want by dramatically reducing your upfront and deposit costs. 

The right loan for you will depend on your income, credit, and the home you’ve selected. Your agent can help you find the home that suits the program you want and make it easy for you to secure the financing you qualify for. Get in touch today to talk about your home buying options and see which loan option is right for you. 

Filed Under: Mortgage Tagged With: Loan Options, Mortgage, VA Loans

An Overview Of Umbrella Insurance: How It Works

September 26, 2024 by Coleen TeBockhorst

An Overview Of Umbrella Insurance: How It WorksAccidents can happen from time to time, which is why it is important for people to have insurance. While you might be able to fix some accidents on your own, others can lead to a significant amount of financial stress. This is why people must have insurance. Insurance is supposed to help individuals and families pay for catastrophic expenses; however, what happens if the insurance policy is not big enough to cover the expenses? That is where umbrella insurance can be helpful. What is umbrella insurance, and how does it work? Learn more about how umbrella insurance might be able to help you.
Umbrella Insurance: A Definition

Umbrella insurance provides extra liability that goes above and beyond the limits of other existing policies. If the policyholder is at-fault for damages and the existing insurance policies are not enough to cover the damages, the umbrella insurance kicks in. In addition, umbrella insurance provides coverage for other items, such as legal fees, that other policies might not cover. Umbrella insurance can cover a wide range of issues that could provide important financial protection.

What Does Umbrella Insurance Cover?

Umbrella insurance acts as a fail-safe to protect you and your family against lawsuits that are directly related to accidents that could result in a personal injury lawsuit. Furthermore, umbrella insurance can cover landlord liability, defamation, and a number of other tricky financial situations, depending on how your policy is structured. Your umbrella policy will have a liability limit; however, your policy might continue to cover associated legal costs above that specific limit, depending on the wording of your policy. Because details and exclusions can vary between policies, you should ask a professional for help if you have questions.

What Umbrella Insurance Does Not Cover

Unlike some insurance policies, umbrella insurance will not cover the damages and injuries of the policyholder. This means that if you sustain property damage, your umbrella insurance policy might not cover this. In addition, there are limits to umbrella insurance with respect to breach of contract cases. Finally, umbrella insurance also does not cover intentional acts or criminal issues. It is critical to read the policy carefully to understand what is covered and what is not.

Filed Under: Mortgage Tagged With: Mortgage, Protecting Your Assets, Umbrella Insurance

Eco-Friendly Homes for a Sustainable Tomorrow

September 25, 2024 by Coleen TeBockhorst

In recent years, the concept of eco-friendly homes has gained significant traction, and for good reason. As awareness of environmental issues grows, more homeowners are seeking ways to minimize their carbon footprint while also reaping the benefits of sustainable living. We will discuss the world of eco-friendly homes, exploring their sustainable features and the potential cost savings they offer. From solar panels to energy-efficient appliances, there’s a plethora of options available to conscientious homeowners looking to make a positive impact on the planet.
The Positives of Eco-Friendly Homes

Reduced Energy Consumption: One of the primary benefits of eco-friendly homes is their reduced energy consumption. Features such as solar panels, energy-efficient appliances, and LED lighting help homeowners minimize their reliance on traditional energy sources, ultimately lowering utility bills and decreasing their carbon footprint.

Improved Indoor Air Quality: Eco-friendly homes often incorporate materials and systems designed to enhance indoor air quality. From low-VOC paints to natural ventilation systems, these features contribute to a healthier living environment, reducing the risk of respiratory problems and allergies.

Long-Term Cost Savings: While the upfront costs of implementing eco-friendly features in a home may be higher than traditional options, the long-term cost savings can be substantial. Energy-efficient appliances, for example, consume less electricity, leading to lower utility bills over time. Additionally, features like rainwater harvesting systems can reduce water expenses in the long run.

Enhanced Resale Value: As the demand for eco-friendly homes continues to rise, properties with sustainable features often command higher resale values. Potential buyers are increasingly prioritizing sustainability, making eco-friendly upgrades a wise investment for homeowners looking to maximize their property’s value.

The Challenges of Eco-Friendly Homes

Higher Initial Costs: One of the main challenges of eco-friendly homes is the higher initial costs associated with implementing sustainable features. From solar panels to green roofing systems, these upgrades often require a significant upfront investment, which can deter some homeowners, particularly those on a tight budget.

Limited Availability of Materials and Technologies: While eco-friendly building materials and technologies are becoming more widely available, they may still be less accessible or more expensive than their conventional counterparts in some regions. This limited availability can pose a challenge for homeowners looking to incorporate sustainable features into their homes.

Maintenance Requirements: Some eco-friendly features, such as green roofs and rainwater harvesting systems, may require additional maintenance compared to traditional options. Regular upkeep is essential to ensure optimal performance and longevity, which can be a consideration for homeowners with busy lifestyles.

Potential Aesthetic Limitations: In some cases, incorporating eco-friendly features into a home’s design may pose aesthetic challenges. For example, solar panels and rainwater barrels may alter the visual appearance of a property, which could be a concern for homeowners who place a premium on curb appeal.

Eco-friendly homes offer a multitude of benefits, from reduced energy consumption to improved indoor air quality. While there are challenges to overcome, such as higher initial costs and maintenance requirements, the long-term advantages far outweigh the drawbacks. By embracing sustainability in home design and construction, homeowners can not only reduce their environmental impact but also enjoy significant cost savings and enhance the value of their properties. In the quest for a greener future, eco-friendly homes are leading the way towards a more sustainable tomorrow.

Filed Under: Homebuyer Tips Tagged With: Eco-Friendly Homes, Home Buying, Reduced Energy Consumption

Tips and Insights on Home Buying with Bad Credit

September 24, 2024 by Coleen TeBockhorst

When thinking about homeownership, a perfect credit score often seems like the golden ticket. But what if your credit history isn’t picture-perfect? Don’t worry; buying a home with bad credit is still within reach. With careful planning and strategic moves, you can turn your dream of homeownership into a reality. Here are some valuable tips and insights to guide you through the process:

1. Know Your Credit Score Inside Out

Before plunging into the homebuying journey, arm yourself with knowledge about your credit score. Request a copy of your credit report from all three major credit bureaus—Equifax, Experian, and TransUnion. Review these reports thoroughly to identify any errors or discrepancies that could be dragging your score down. Rectifying inaccuracies can give your credit score a significant boost.

2. Understand Your Options

Having bad credit doesn’t necessarily mean you’re out of options. Research various home loan programs tailored for individuals with less-than-perfect credit. FHA (Federal Housing Administration) loans, for instance, are accessible to borrowers with credit scores as low as 500 with a 10% down payment or 580 with a 3.5% down payment. Keep in mind that the FHA sets this limit, but individual lenders may require a higher score. Explore alternative lenders or credit unions that might offer more flexibility in lending criteria.

3. Build Up Your Savings

While a hefty down payment can mitigate the impact of bad credit, it’s not the only financial aspect to consider. Lenders often scrutinize your savings and assets to gauge your financial stability. Prioritize building up your savings to demonstrate your ability to handle homeownership responsibilities. Aim to have a healthy emergency fund in place to cover unexpected expenses post-purchase.

4. Consider a Co-Signer or Joint Application

If your credit score falls below the lender’s threshold, consider enlisting the help of a co-signer with a stronger credit profile. A co-signer essentially guarantees the loan and shares responsibility for repayment. Alternatively, explore joint applications with a spouse, partner, or family member to combine incomes and improve your overall financial standing in the eyes of lenders.

5. Improve Your Credit Score Before Applying

Patience can be a powerful tool in your homeownership journey. Take proactive steps to improve your credit score before applying for a mortgage. Pay down existing debts, make timely payments on all bills, and avoid opening new lines of credit. These actions demonstrate financial responsibility and can lead to a gradual increase in your credit score over time.

While bad credit may present challenges on the path to homeownership, it’s not an impossible obstacle. Armed with knowledge, determination, and strategic planning, you can navigate the homebuying process with confidence. Remember, the journey to owning your dream home may have its twists and turns, but with perseverance and the right approach, you can turn your homeownership dreams into reality. Give us a call today to see how we can help!

Filed Under: Home Buyer Tips Tagged With: Bad Credit, Homebuying Tips, Mortgage

« Previous Page
Next Page »

Contact Coleen

Coleen Tebockhorst

Coleen TeBockhorst
coleen.tebockhorst@citywidehm.com

Senior Loan Officer

Call me! (612) 701-8512

NMLS #274205

Download My Mortgage eGuide today

CW Home Mortgage logo_White

Guaranteed Rate, Inc. DBA Citywide Home Mortgage

Categories

Our Location

10591 165th St. West
Lakeville MN, 55044

Connect With Me

This site is not authorized by the New York State Department of Financial Services. No mortgage loan applications for properties located in New York will be accepted through this site. Operating in the state of California as Guaranteed Rate, Inc. D/B/A Citywide Home Mortgage. If you are a California resident, please review our Privacy Policy to learn more about the categories and business purpose of personal information we may collect and your right to opt-out from the sale of personal information.

Applicant subject to credit and underwriting approval. Not all applicants will be approved for financing. Receipt of application does not represent an approval for financing or interest rate guarantee. Refinancing your mortgage may increase costs over the term of your loan. Restrictions may apply. All information provided in this publication is for informational and educational purposes only, and in no way is any of the content contained herein to be construed as financial, investment, or legal advice or instruction. Citywide Home Mortgage does not guarantee the quality, accuracy, completeness or timelines of the information in this publication. While efforts are made to verify the information provided, the information should not be assumed to be error-free. Some information in the publication may have been provided by third parties and has not necessarily been verified by Citywide Home Mortgage. Citywide Home Mortgage, its affiliates and subsidiaries do not assume any liability for the information contained herein, be it direct, indirect, consequential, special, or exemplary, or other damages whatsoever and howsoever caused, arising out of or in connection with the use of this publication or in reliance on the information, including any personal or pecuniary loss, whether the action is in contract, tort (including negligence) or other tortious action.

Coleen TeBockhorst NMLS ID: 274205 Copyright © 1998-2025 Guaranteed Rate, Inc. D/B/A Citywide Home Mortgage. All rights reserved.

For licensing information, go to: www.nmlsconsumeraccess.org.

NMLS License #2611 – 3940 N Ravenswood Chicago, IL 60613. (866) 508-5515. Equal Housing Lender.

Licensing | Privacy | Terms of Use

Copyright © 2026 · Powered by MySMARTblog

Copyright © 2026 · Genesis Sample Theme on Genesis Framework · WordPress · Log in