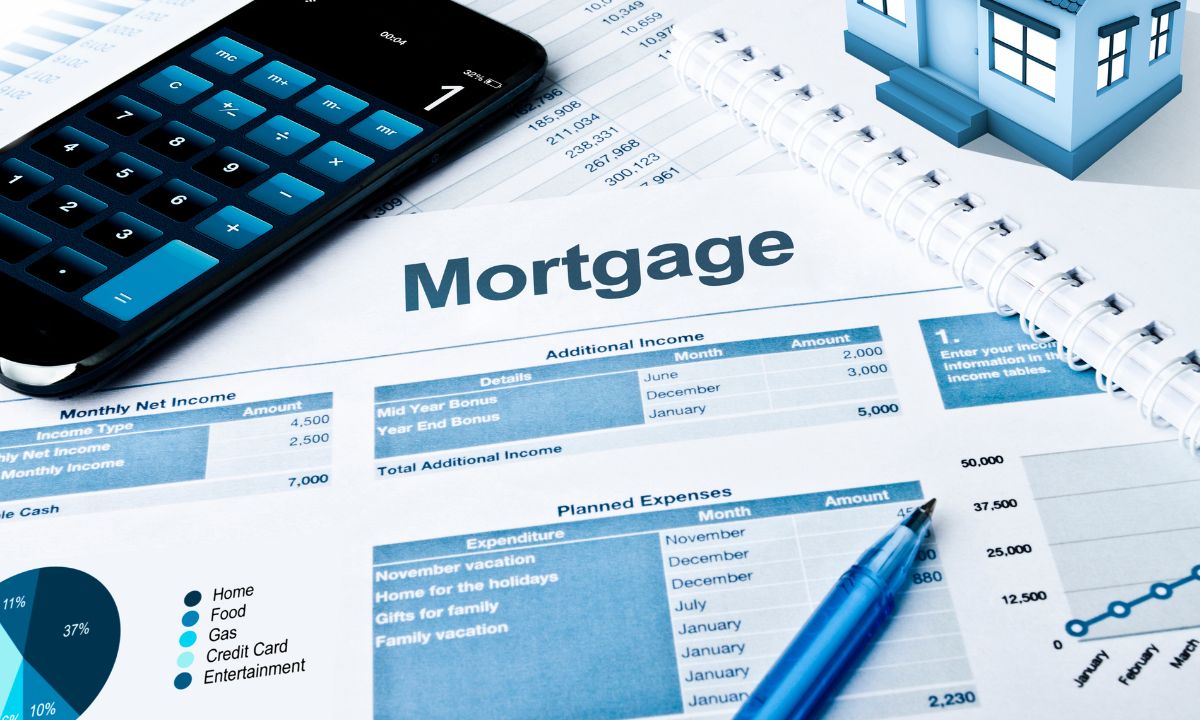
 Construction loans and mortgages are two important tools in the world of real estate financing. They each have specific purposes and come with their own set of rules and requirements. These differences cater to various needs when it comes to buying or building properties.
Construction Loan: A construction loan is specifically designed to finance the construction of a new property or significant renovations to an existing property. These loans typically have short terms and are used to cover the costs of labor, materials, and other expenses associated with building or renovating a property.
Mortgage: A mortgage, on the other hand, is a loan used to purchase a property that is already built. It is a long-term loan secured by the property itself.
Disbursement
Construction Loan: Construction loans are typically disbursed in phases or “draws” as the construction progresses. The lender may inspect the progress of the construction before releasing funds for each phase.
Mortgage: A mortgage is usually disbursed in a lump sum at the time of purchase or refinance of the property.
Interest Rates and Terms
Construction Loan: Construction loans often have higher interest rates than traditional mortgages because they are considered riskier by lenders. They also have shorter terms, typically ranging from six months to three years.
Mortgage: Mortgages generally have lower interest rates compared to construction loans, and they can have terms of 15, 20, or 30 years, depending on the agreement between the borrower and the lender.
Requirements
Construction Loan: Lenders typically require detailed plans and specifications for the construction project, as well as a budget outlining the costs involved. They may also require a larger down payment compared to a traditional mortgage.
Mortgage: Mortgage requirements vary depending on the lender and the type of mortgage being sought, but they generally include factors such as credit score, income, employment history, and debt-to-income ratio.
Application Process
Construction Loan: The application process for a construction loan may be more involved than that of a traditional mortgage because lenders want to ensure that the project is feasible and that the borrower has the means to complete it. Borrowers may need to provide detailed plans and specifications, as well as a budget for the project.
Mortgage: The application process for a mortgage typically involves providing documentation related to income, assets, debts, and credit history. Borrowers may also need to undergo a home appraisal and provide a down payment.
While both construction loans and mortgages are used to finance property, they have different purposes, terms, requirements, and application processes. Construction loans are for building or renovating properties, have shorter terms and higher interest rates, and require detailed plans and budgets. Mortgages are used to purchase existing properties, have longer terms and lower interest rates, and require documentation related to the borrower’s financial situation.
 The options for securing a mortgage have expanded beyond the brick-and-mortar banks to include online lenders. With this diversity comes a crucial decision for homebuyers: should you opt for the convenience of online lenders or stick with the familiarity of traditional banks? Let’s explore the pros and cons of both options to help you make an informed decision.
 Private Mortgage Insurance (PMI) is a sizable expense during the process of buying a home that many overlook until it impacts their financial decisions. Understanding PMI, its purpose, and strategies to manage or eliminate it can save you thousands of dollars over the life of your mortgage.
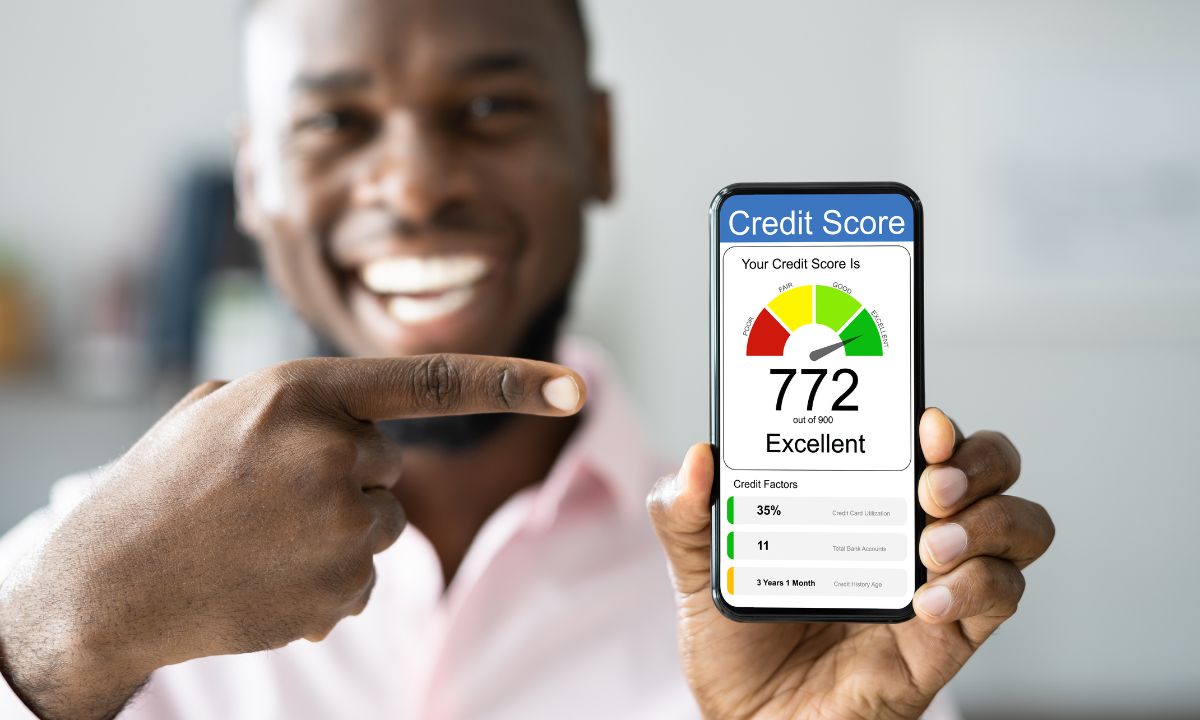 The interest rate you qualify for when securing a mortgage can make a huge difference in your financial journey. The good news is, that by understanding how credit scores impact mortgage rates and implementing strategic steps to boost your score, you can potentially unlock lower rates and save thousands of dollars over the life of your loan.
 Escrow might sound like a fancy term, but it’s not rocket science. Let’s break it down into simple terms. In simple terms, an escrow analysis is a review of your escrow account conducted by your mortgage lender. Think of it as a regular check-up for your escrow account. You might be wondering, what is an escrow account? An escrow account holds funds collected with your monthly mortgage payment to cover expenses like property taxes, homeowners insurance, and sometimes even mortgage insurance.
 Want to upgrade your home but short on cash? Home improvement loans can help! They’re like a financial boost for fixing up your place without draining your savings. But with so many options, how do you pick the right one? Let’s review the options.
 Are you a single individual ready to take the plunge into homeownership? Congratulations! While the journey might seem overwhelming, especially when it comes to securing a mortgage, there is no need to worry. With the right strategies and tips, you can navigate the process with confidence and success. As a mortgage lender with years of experience helping single homebuyers achieve their dreams, I’m here to share some valuable insights to guide you on your path to homeownership.
 Those who are involved in the real estate industry likely know that mortgage rates are at an all-time low. At the same time, nobody wants to pay more for a house than they have to. Some of the most important factors that dictate how much someone is going to pay for a house include points and interest rates.
