
An extremely light week following the FOMC, with the only note-worthy reporting being the Consumer Sentiment reports from the University of Michigan, which gives a long term outlook of the consumer on the economy. The report has come in well under expectations, much more so than any previous release in the last 6 months. This is largely due to the increase in the cost of living for every sector.
Consumer Sentiment
The University of Michigan’s gauge of consumer sentiment fell to 67.4 in a preliminary May reading, down from 77.2 in the prior month.
Primary Mortgage Market Survey Index
- 15-Yr FRM rates are seeing a decrease by -0.09% with the current rate at 6.38%
- 30-Yr FRM rates are seeing a decrease by -0.13% with the current rate at 7.09%
MND Rate Index
- 30-Yr FHA rates are seeing a -0.08% decrease for this week. Current rates at 6.62%
- 30-Yr VA rates are seeing a -0.08% decrease for this week. Current rates at 6.64%
Jobless Claims
Initial Claims were reported to be 231,000 compared to the expected claims of 214,000. The prior week landed at 208,000.
What’s Ahead
Next week we’re expecting new rounds of inflation data from CPI and PPI reports. Given the current data that has been released, the inflation problem is expected to still be a small sticking issue.
 Owning a home is a dream for many, representing a significant milestone and a considerable financial investment. However, along with the excitement of homeownership comes a set of responsibilities and financial commitments. One of the most crucial aspects of safeguarding your investment is securing homeowners insurance.
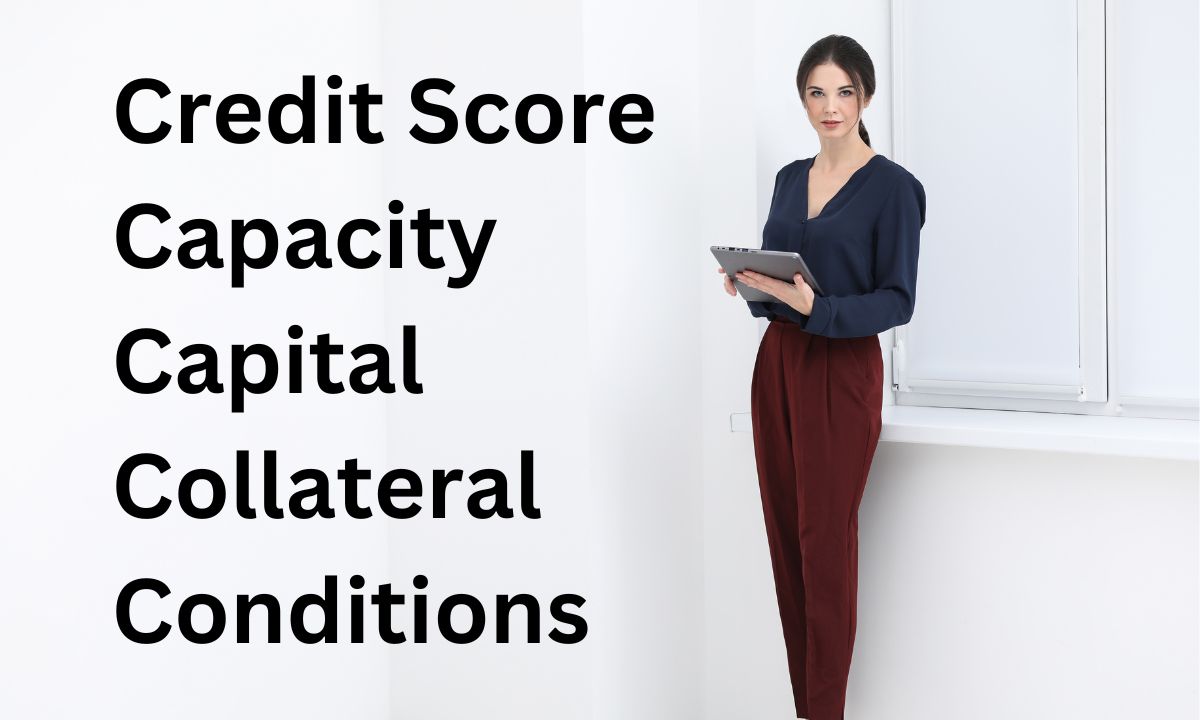 Buying a home is one of the most significant financial decisions most of us will ever make. It’s a journey filled with excitement, anticipation, and sometimes, a touch of anxiety. Among the many steps involved in this process, understanding mortgage underwriting is crucial. To demystify this complex process, let’s delve into the 5 C’s of mortgage underwriting.
 If you’re gearing up to dive into the world of real estate, there are a few key terms you’ll want to wrap your head around before taking the plunge. Today, we’re demystifying APR and interest rate, two crucial concepts that can impact your home-buying journey. Don’t worry, I’ll break it down in simple terms so you can confidently navigate the process like a pro.
 Are you in the market for a new home? One of the most crucial decisions you’ll face is choosing the right mortgage term. With options like 30-year and 20-year mortgages available, it’s essential to weigh the pros and cons to make an informed decision that suits your financial goals. Let’s discuss the debate of 30-year versus 20-year mortgages and explore which option might be better for you.
 With all of the economic uncertainties, many homeowners find themselves facing financial hardships that impact their ability to meet mortgage payments. Whether it’s due to job loss, medical emergencies, or other unexpected circumstances, the fear of losing one’s home can be overwhelming. Fortunately, there’s a lifeline available in the form of mortgage forbearance.
 So you are soon to be an empty nester! With the kids flown from the nest, it’s your time to welcome a new chapter of freedom and flexibility. Whether you’re looking to downsize to a cozier space or relocate to your dream destination, navigating the mortgage landscape can seem overwhelming. There is no need to fear! We’ve got you covered with some invaluable tips tailored to meet the unique needs of empty nesters like you.
 Are you dreaming of owning your own home but facing obstacles in securing a mortgage? You’re not alone. Many aspiring homeowners encounter challenges due to factors like credit history, income, or debt-to-income ratio. There is a potential solution that could help you achieve your homeownership goals: a cosigner.
 As a homeowner, tapping into your home equity can be a strategic financial move. Whether you’re renovating your house, consolidating debt, or covering major expenses, two popular options stand out: home equity loans and home equity lines of credit (HELOCs). Understanding the differences between these two can help you make an informed decision that best suits your needs and financial goals.
