CTeBockhorst's Blog

The Mortgage and Real Estate Scoop

  • Home
  • About
  • Blog
  • Resources
    • Calculators
    • Download My eGuide Today!
    • First Time Buyer Tips
    • First Time Seller Tips
    • Loan Checklist
    • Loan Process
    • Loan Programs
    • Home Appraisal
    • Home Inspection
    • What to Expect at a Loan Closing: A Step-by-Step Guide
  • Apply
  • Reviews
    • Read My Reviews
    • Zillow Reviews
    • Leave a Review
  • Contact

Concerns To Address When Choosing The Right Mortgage Lender

July 7, 2023 by Coleen TeBockhorst

Concerns To Address When Choosing The Right Mortgage LenderChoosing the right mortgage lender is a crucial decision when you’re considering purchasing a home or refinancing your existing mortgage. With numerous lenders available in the market, it’s important to carefully evaluate your options to ensure you select a lender that suits your needs and financial goals.

Interest Rates and Terms:

One of the primary factors to consider is the interest rate offered by the lender. A lower interest rate can significantly impact your monthly mortgage payments and overall affordability. Compare rates and terms from different lenders to determine the most favorable options for your financial situation.

Lender’s Reputation and Credibility:

When dealing with something as important as a mortgage, it’s crucial to work with a reputable and trustworthy lender. Research the lender’s reputation, read customer reviews, and check if they have any disciplinary actions or complaints lodged against them. Choose a lender with a solid track record, excellent customer service, and a history of fulfilling their commitments.

Loan Programs and Options:

Every borrower has unique financial circumstances, so it’s essential to choose a lender that offers a variety of loan programs and options. Whether you’re a first-time homebuyer, self-employed, or have a less-than-perfect credit score, look for a lender who specializes in providing loans tailored to your specific needs.

Costs and Fees:

Apart from the interest rate, it’s important to consider the various costs and fees associated with the mortgage. Lenders may charge origination fees, closing costs, appraisal fees, and other expenses. Request a Loan Estimate (LE) from each lender, which will provide a breakdown of the costs involved.

Customer Service and Support:

The mortgage process can be complex and time-consuming, so it’s essential to choose a lender who provides excellent customer service and support. A lender who is responsive and communicates clearly can help alleviate stress and ensure a smooth experience.

Prequalification and Preapproval Process:

Before you start house hunting, it’s advisable to get prequalified or preapproved for a mortgage. Evaluate the lender’s prequalification or preapproval process and the time it takes to complete it. A streamlined and efficient process can give you an advantage when making an offer on a property, demonstrating your readiness and seriousness as a buyer.

By evaluating interest rates, lender credibility, loan programs, costs, customer service, and the prequalification process, you can make an informed decision that aligns with your financial goals and preferences. Take the time to compare multiple lenders, gather all necessary information, and seek professional advice if needed. With the right mortgage lender, you can embark on your homeownership journey with confidence.
Filed Under: Home Mortgage Tagged With: Lenders, Mortgage

How To Beat High Inflation with a Home Purchase

July 6, 2023 by Coleen TeBockhorst

How To Beat High Inflation with a Home PurchaseInflation can erode the value of your savings over time, and one way to hedge against inflation is by investing in assets that appreciate in value over time. Real estate is often considered a good hedge against inflation, as property values tend to rise in line with inflation.
Here are some ways a home purchase can help beat high inflation:

Lock in a low-interest rate mortgage: High inflation often leads to higher interest rates, but if you lock in a low-interest rate mortgage when inflation is low, you can benefit from lower mortgage payments even if interest rates rise in the future. This can free up more money for other expenses and investments.

Appreciation: Real estate values tend to rise over time, especially in areas with high demand and limited supply. If you purchase a home in an area that is likely to appreciate, you can benefit from the increase in value over time.

Rental income: If you purchase a home as an investment property, you can generate rental income that increases with inflation. Rental income can provide a steady stream of passive income that can keep up with inflation.

Tax benefits: Homeowners can deduct mortgage interest and property taxes from their federal income taxes, which can help offset the costs of homeownership. These deductions can be especially valuable during times of high inflation when other deductions may lose value.

Diversification: Investing in real estate can diversify your investment portfolio, reducing the overall risk of inflation. Real estate has historically performed well during periods of inflation and can provide a valuable hedge against the erosion of purchasing power caused by inflation.

It’s important to note that buying a home should be a long-term investment strategy, and not a short-term solution to beat inflation. Real estate values can fluctuate over short periods of time, and it may take several years to recoup your investment. It’s also important to consider the costs of homeownership, such as maintenance, repairs, and property taxes, when evaluating the potential benefits of purchasing a home.

Filed Under: Mortgage Tagged With: Home Prices, Inflation, Mortgage

What’s Ahead For Mortgage Rates This Week – Juy 3, 2023

July 3, 2023 by Coleen TeBockhorst

What's Ahead For Mortgage Rates This Week - Juy 3, 2023Last week’s scheduled economic news includes readings on inflation, new home sales, pending home sales, and consumer sentiment. Federal Reserve Chair Jerome Powell spoke at a banking conference in Spain. Weekly reports on mortgage rates and jobless claims were also released.
New Home Sales Rise as Pending Home Sales Fall

May readings for new and pending home sales showed mixed results for May. 763,000 new home sales were expected on a seasonally-adjusted annual basis. Analysts expected a reading of 675,000 sales based on April’s year-over-year reading of 680,000 new home sales. May’s increase in new home sales was the largest since  February 2022.

New home sales increased for the third consecutive month. The supply of new homes for sale fell 11.80 percent between April and May to a 7-month supply of new homes available. Sales were strongest in the Northeast and West.

Pending home sales fell by -2.70 percent in May.

Mortgage Rates, Jobless Claims

Freddie Mac reported higher average mortgage rates last week. The average rate for 30-year fixed-rate mortgages rose by four basis points to 6.71 percent; the average rate for 15-year fixed-rate mortgages rose by three basis points to 6.06 percent.

Federal Reserve Chair Jerome Powell spoke at a banking conference in Spain. He discussed the U.S. economy and how the Fed addressed the financial downturn after the Great Recession and discussed current economic trends including the impact of higher mortgage rates on the housing sector and low unemployment.

Chair Powell also outlined the Fed’s goal of reducing inflation to 2.00 percent a year; it presently runs near 4.00 percent. Mr. Powell cited headwinds to lowering inflation including tighter credit requirements for individuals and businesses. Mr. Powell cautioned that further tightening may result from bank stresses that occurred in March.

June’s consumer sentiment index reading was nearly unchanged with an index reading of 64 for June as compared to May’s reading of 63.99. Index readings over 50 indicate that most consumers are confident about current economic conditions.

What’s Ahead

This week’s scheduled economic reports include readings on construction spending, public and private sector employment, and minutes of June’s Federal Open Market Committee meeting. Weekly reports on mortgage rates and jobless claims will also be released. 

Filed Under: Financial Reports Tagged With: Case Shiller, Jobless Claims, Mortgage Rates

What to Look For During Your Home Inspection

June 30, 2023 by Coleen TeBockhorst

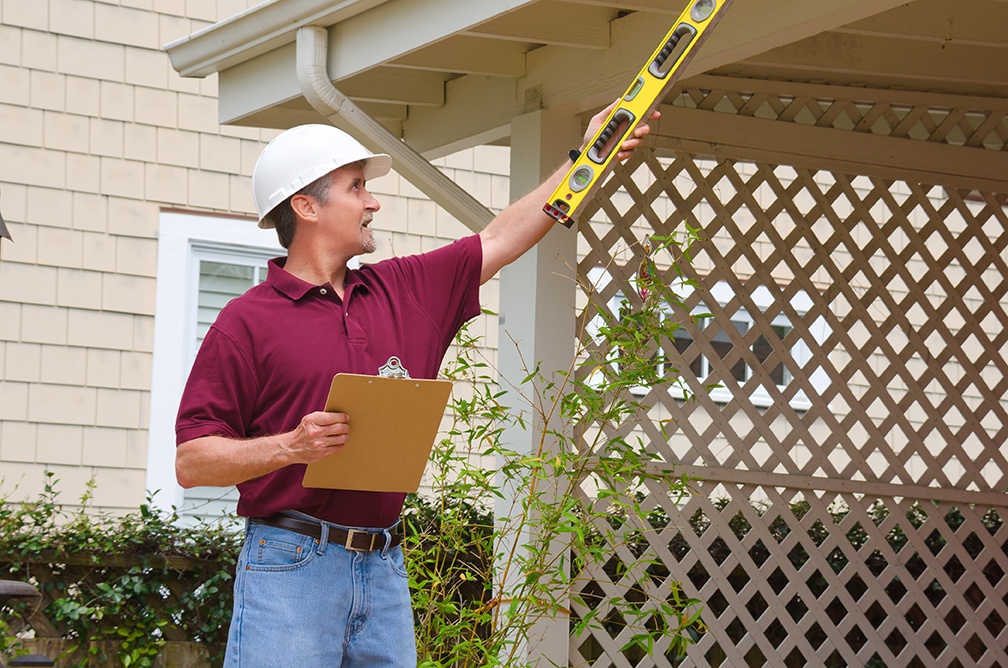
What To Look For During Your Home InspectionBuying a new home is an exciting and significant milestone in anyone’s life. However, it’s essential to approach the homebuying process with caution and thoroughness to ensure that you’re making a sound investment. One crucial step in the homebuying journey is the home inspection. A home inspection is a comprehensive evaluation of a property’s condition, aiming to uncover any potential issues or concerns that could affect its value or safety. Below are some tips to remember when navigating a home inspection.
Roof and Exterior:

The roof is your home’s first line of defense against the elements, so it’s crucial to examine it closely. Look for missing or damaged shingles, signs of leakage, and the overall condition of the roof.

Structural Integrity:

A solid foundation and sound structure are vital for the long-term stability and safety of your home. Inspect the foundation for cracks, unevenness, or signs of settling. Look out for any sagging or uneven floors, as they could indicate structural issues.

Plumbing and Electrical Systems:

Faulty plumbing or electrical systems can lead to significant problems and costly repairs. Test the faucets, showers, and toilets to ensure proper water flow and drainage. Check for leaks under sinks and around toilets. In terms of electrical systems, inspect the circuit breaker panel and look for any exposed wiring, outdated systems, or potential fire hazards.

HVAC Systems:

Heating, ventilation, and air conditioning (HVAC) systems are critical for maintaining a comfortable living environment. Have the HVAC systems thoroughly inspected to determine their condition and efficiency.

Insulation and Energy Efficiency:

Good insulation and energy-efficient features can greatly impact your home’s comfort and utility costs. Check the insulation in the attic, walls, and crawl spaces to ensure they meet the recommended standards. Inquire about the home’s energy efficiency features, such as double-pane windows, energy-efficient appliances, or renewable energy installations.

Pest and Mold Inspection:

Pests and mold can pose health risks and cause extensive damage to a home. Look for signs of pests such as droppings, chewed wood, or insect nests. Ask the inspector about any past or present pest infestations and the steps taken to address them.

A home inspection is a crucial step in the homebuying process that helps you make an informed decision about your investment. By paying close attention to the areas mentioned above, you can identify potential issues and negotiate repairs or adjustments with the seller. A thorough home inspection can provide peace of mind and ensure that you’re buying a home that meets your expectations in terms of safety, functionality, and value.

Filed Under: Homebuyer Tips Tagged With: Home Inspection, Real Estate

S&P Case-Shiller Housing Market Indices: Short Supply of Homes for Sale Pushes Prices Up

June 29, 2023 by Coleen TeBockhorst

S&P Case-Shiller Housing Market Indices: Short Supply of Homes for Sale Pushes Prices UpApril readings for S&P Case-Shiller’s Housing Market Indices showed gains in home prices throughout the U.S. Rising prices were caused by shortages of previously-owned homes for sale and increasing buyer demand as the average 30-year mortgage rate exceeded six percent.  The southeastern region lost its top spot on S&P Case-Shiller’s 20-City Home Price Index as Chicago, Illinois, Atlanta, Georgia, and Tampa, Florida held the top three year-over-year home price growth rates for April.
Chicago, Illinois Breaks Southeast’s Lead on April Home Price Growth

The top three cities with the highest home price growth rates as reported in April’s   S&P Case-Shiller’s 20-City Home Price Index were Chicago, Illinois with a  year-over-year home price gain of 4.10 percent;  Atlanta, Georgia posted a year-over-year home price growth of 3.50 percent.  Tampa, Florida placed third in the 20-City Index with an average home price gain of 2.40 percent. All year-over-year readings for April home prices were seasonally adjusted.

Average home prices lagged in the West as the combined impact of high home prices and mortgage rates created affordability issues for would-be home buyers. Seattle, Washington saw average home prices drop by -12.40 percent year-over-year; San Francisco, California reported that year-over-year home prices declined by 11.10 percent in April. Home prices in Las Vegas, Nevada fell by 6.60 percent year-over-year.

Mortgage rates nearing 7 percent did not appear to impact home buyers to a great extent, but higher rates do increase the cost of home loans and monthly payments; current mortgage rates and rising home prices do not promote affordable opportunities for first-time and moderate-income home buyers.

FHFA House Price Index

In related news, the Federal Housing Finance Agency posted 0.50 percent month-to-month-home price growth in its  House Price Index for April. This index reports on home prices for homes sold by the Government Sponsored Enterprises Fannie Mae and Freddie Mac. These homes were acquired through foreclosure and were subject to original loan limits established by FHFA for mortgages acquired or guaranteed by Fannie Mae and Freddie Mac The GSEs’ loan limits cause a more moderate range of home price growth reported in  FHFA’s House Price Index as compared to data reported in the S&P Case-Shiller Home Price Indices.

Filed Under: Financial Reports Tagged With: Case Shiller, Financial Report, Housing Market

Renovating a Bathroom: DIY vs Hiring a Professional

June 28, 2023 by Coleen TeBockhorst

Renovating a Bathroom: DIY vs Hiring a ProfessionalThe bathroom is one of the most important and frequently used spaces in a home. Over time, it may start to show signs of wear and tear or become outdated. If you’re considering renovating your bathroom, one of the first decisions you’ll face is whether to tackle the project yourself or hire a professional. Both options have their pros and cons, and it’s essential to weigh them carefully before deciding.
DIY Renovation:

One of the most significant advantages of a DIY bathroom renovation is the potential cost savings. By doing the work yourself, you eliminate the labor costs associated with hiring a professional. You have control over the materials and can find budget-friendly options to stay within your desired price range.

Taking on a DIY bathroom renovation also gives you complete control over the project. You can choose the design, materials, and timeline that suit your preferences and schedule. This level of flexibility allows you to customize your bathroom to your exact specifications.

Completing a DIY bathroom renovation can be a rewarding experience. Seeing the transformation unfold before your eyes and knowing that you accomplished it on your own can provide a great sense of pride and satisfaction. It can also be a learning opportunity, as you’ll gain new skills and knowledge throughout the process.

Hiring a Professional:

Professional bathroom renovators bring a wealth of knowledge and experience to the table. They are well-versed in all aspects of bathroom renovations, from design to construction. Their expertise ensures that the project is executed efficiently and to a high standard, resulting in a beautiful and functional bathroom.

Hiring a professional allows you to save time and effort. They have a team of skilled workers who can complete the renovation quickly and efficiently. Professionals also have access to specialized tools and equipment that can streamline the process and deliver excellent results. Professional bathroom renovators take pride in their work and strive to deliver exceptional quality.

The decision between a DIY bathroom renovation and hiring a professional depends on your skills, budget, and personal preferences. DIY projects can be cost-effective and rewarding, but they require time, effort, and a certain level of expertise. Hiring a professional ensures expertise, efficiency, and high-quality results but comes with a higher cost and limited control. Whichever option you choose, thorough planning, research, and realistic expectations are essential for a successful bathroom renovation.

Filed Under: Home Values Tagged With: DIY, Real Estate, Renovation

Most Common Questions First-Time Home-Buyers Ask

June 27, 2023 by Coleen TeBockhorst

Most Common Questions First-Time Home-Buyers AskBuying your first home is an exciting milestone in life, but it can also be overwhelming and filled with questions. As a first-time home buyer, you want to make informed decisions and ensure a smooth process. Below we will address some of the common questions that first-time home buyers often ask.
1. What Exactly Is a Mortgage? A mortgage is an agreement between you and a lender that allows you to borrow money to purchase or refinance a home and gives the lender the right to take your property if you fail to repay the money you’ve borrowed.

2. What is the Difference between Pre-Qualification and Pre-Approval? A Pre-Qualification is informal and can be done over the phone or internet with no obligation or paperwork to complete and will only be able to tell you roughly what you can borrow. A Pre-Approval is a formal commitment to lend, and the lender collects all required documents to verify your income, assets & credit and will give you a definite idea of what you can afford.

3. What Steps Do I Need to Take to Secure a Loan? The first step is to complete a Loan Application and provide documentation to verify the application information.

You will need to provide:

  • Pay Stubs
  • W2 Forms or Tax Returns
  • Recent Bank Statements
  • Any other documents requested by the underwriter

4.  How Can I Find Out What My Credit Report Score Is? There are several ways to obtain a copy of your credit report. You can request a free copy of your credit report from each of the three major credit reporting agencies.

5. What Are My Responsibilities During the Lending Process? The key thing to remember is to keep your financial circumstances steady during the loan process.

Here are some simple guidance tips:

  • Do not change jobs, become self-employed or quit your job.       
  • Do not acquire more debt (This includes cars, boats, jewelry, household items or furniture etc.)
  • Do not charge large amounts to your credit cards and keep all payments current.
  • Do not spend money you have set aside for closing.
  • Do not apply for loans.
  • Do not change bank accounts or make large or unusual deposits into your account.
  • Do not agree to co-sign or co-borrow with anyone during the process of your loan.

6. What Does it Mean to “Lock in a Rate?” Interest rates fluctuate  day to day, when you lock the loan it will guarantee that you will receive that rate for the duration of the lock.

7. What does Loan-To-Value mean? Loan-to-value is the amount of money you borrow compared to the purchase price conveyed as a percentage.

8. What Is Included in the Monthly Mortgage Payment? There are five items that are included in a mortgage payment. principal interest, property taxes, homeowners’ insurance, and mortgage insurance

9. What Is Mortgage Insurance and Why do I need It? Mortgage Insurance protects the lender if you fail to pay your mortgage and it is usually required if you put down less than 20%. There are many mortgage insurance options to fit your needs.

10. What Should I Expect on Closing Day? Be sure that you have everything that you need. At closing you will sign a lot of papers, but they will all be explained to you. BE SURE you arrive to the closing on time, and you will be guided from there.

Filed Under: Mortgage Tagged With: First Time Buyer, New Home

What’s Ahead For Mortgage Rates This Week – June 26, 2023

June 26, 2023 by Coleen TeBockhorst

What's Ahead For Mortgage Rates This Week - June 26, 2023Last week’s scheduled economic reports included readings on housing starts, existing home sales, and Federal  Reserve Chair Jerome Powell’s congressional testimony. Weekly readings on mortgage rates and jobless claims were also released.
National Home Builders Association Releases June Housing Market Index

U.S.  home builder confidence rose by five points to an index reading of 55 in June according to the National Association of Home Builders Housing Market Index. The June reading surpassed the expected reading of 51 and May’s housing market index reading of 50. Component readings for the Housing Market Index also rose as builder confidence in current market conditions rose five points and confidence in market conditions for the next six months rose six points.

NAHB said that a shortage of previously-owned homes for sale is driving sales of new homes and rising builder confidence. Many current homeowners refinanced to very low rates available during and immediately after the pandemic and are not inclined to refinance or buy new homes at current higher interest rates.

Mr. Robert Dietz, the chief economist for the NAHB, said: “A  bottom is forming for single-family home building as builder sentiment continues to gradually rise from the beginning of the year.” Mr. Dietz also noted that “with the Federal Reserve nearing the end of its tightening cycle, it’s good news for future market conditions in terms of mortgage rates and the cost of builder and developer loans.”

June’s reading was the sixth consecutive month showing increasing home builder confidence and the 11th month since builder sentiment moved into positive territory.

Mortgage Rates Fall

Freddie Mac reported lower average mortgage rates last week as rates for 30-year fixed-rate mortgages fell by two basis points to 6.67 percent and rates for 15-year fixed-rate mortgages fell by seven basis points to an average rate of 6.03 percent.

Sales of previously-owned homes rose to a seasonally-adjusted annual rate of 4.30 million sales as compared to the expected reading of 4.25 million sales and April’s reading of April’  reading of 4.29 million sales.

What’s Ahead

This week’s scheduled economic reporting includes readings from S&P Case-Shiller Indices, new and pending home sales, and inflation. Weekly readings on mortgage rates and jobless claims will also be released.

Filed Under: Financial Reports Tagged With: Financial Report, Jobless Claims, Mortgage Rates

How to Calculate Mortgage Payments

June 23, 2023 by Coleen TeBockhorst

How to Calculate Mortgage Payments Calculating mortgage payments involves several variables, including the loan amount, the interest rate, and the loan term. Here are the steps to calculate mortgage payments:
Determine the loan amount: This is the amount you will borrow to purchase the property. For example, if you plan to buy a house for $300,000 and you plan to put down a 20% down payment ($60,000), your loan amount will be $240,000.

Determine the interest rate: The interest rate is the cost of borrowing the money. It is expressed as a percentage. For example, if the interest rate is 4%, you will pay 4% of the loan amount in interest each year.

Determine the loan term: This is the length of time over which you will repay the loan. For example, if you have a 30-year mortgage, you will make 360 monthly payments (30 years x 12 months).

You can use the following formula to calculate your monthly mortgage payment:

M = P [ i(1 + i)^n ] / [ (1 + i)^n – 1]

Where:

M = monthly mortgage payment

P = loan amount

i = interest rate (monthly)

n = loan term (number of months)

Using this formula, you can calculate your monthly mortgage payment by plugging in the values for P, I, and N.

Alternatively, you can use a mortgage payment calculator to calculate your mortgage payment  If you choose a mortgage calculator, you will need to know your income, expenses, and debts. This information will help you determine how much you can afford to borrow. You can find a mortgage calculator online or through a mortgage lender’s website. Make sure you use a reliable calculator. Once you have a mortgage calculator, enter your financial information into the calculator. This includes your income, expenses, debts, and the loan term. Use the calculator to adjust the variables such as the interest rate, down payment, and loan term to see how they affect your monthly payment and the total cost of the loan.

The mortgage calculator will provide you with an estimate of how much you can afford to borrow, what your monthly payment would be, and the total cost of the loan. Make sure the results fit within your budget and financial goals. If you’re ready to move forward with a mortgage, it’s a good idea to consult with a mortgage lender to discuss your options and get pre-approved for a loan. They can also provide you with more information on closing costs and other fees associated with the mortgage.

Filed Under: Mortgage Tagged With: Mortgage, Mortgage Payments

The Pros and Cons of buying new VS Pre-Owned

June 22, 2023 by Coleen TeBockhorst

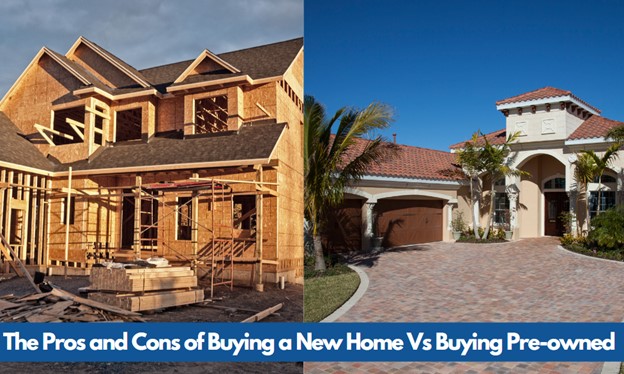
The Pros and Cons of buying new VS Pre-OwnedBuying a home is a significant investment, and one of the most important decisions to make when buying a home is whether to purchase a new or pre-owned property. Here are some pros and cons of each option:

Pros of buying a new home:

Customization: With a new home, you have the ability to customize and personalize the space to your liking, including choosing finishes, colors, and layouts.

Energy Efficiency: New homes often come with energy-efficient features, such as double-pane windows, modern insulation, and energy-saving appliances, which can save you money on utility bills.

Warranty: New homes usually come with a warranty that covers defects and repairs for a certain period of time.

Low Maintenance: Since everything in a new home is brand new, there is less need for repairs and maintenance in the early years.

Cons of buying a new home:

Cost: New homes are often more expensive than pre-owned homes due to the cost of land and construction materials.

Location: New homes are often built in new developments, which may be further away from established neighborhoods, schools, and other amenities.

Lack of Character: New homes may lack the charm and character of older homes, which may have unique architectural details and historic features.

Pros of buying a pre-owned home:

Affordability: Pre-owned homes are often less expensive than new homes, especially if they require some updates or renovations.

Established Neighborhoods: Pre-owned homes are often located in established neighborhoods with mature trees and amenities like parks, schools, and shops.

Character: Pre-owned homes often have unique features, such as original hardwood floors, fireplaces, and architectural details, that give them character and charm.

Cons of buying a pre-owned home:

Repairs and Maintenance: Pre-owned homes may require more repairs and maintenance, especially if they are older and have not been well-maintained.

Lack of Customization: Pre-owned homes may not be as customizable as new homes, and you may have to live with features that you do not like.

Energy Efficiency: Pre-owned homes may not have the same level of energy efficiency as new homes, which can result in higher utility bills.

Ultimately, the decision to buy a new or pre-owned home depends on your priorities, budget, and personal preferences. It is important to consider all factors and work with a reputable real estate agent to find the right home for you.

Filed Under: Homeowner Tips Tagged With: Mortgage, New, Preowned

« Previous Page
Next Page »

Contact Coleen

Coleen Tebockhorst

Coleen TeBockhorst
coleen.tebockhorst@citywidehm.com

Senior Loan Officer

Call me! (612) 701-8512

NMLS #274205

Download My Mortgage eGuide today

CW Home Mortgage logo_White

Guaranteed Rate, Inc. DBA Citywide Home Mortgage

Categories

Our Location

10591 165th St. West
Lakeville MN, 55044

Connect With Me

This site is not authorized by the New York State Department of Financial Services. No mortgage loan applications for properties located in New York will be accepted through this site. Operating in the state of California as Guaranteed Rate, Inc. D/B/A Citywide Home Mortgage. If you are a California resident, please review our Privacy Policy to learn more about the categories and business purpose of personal information we may collect and your right to opt-out from the sale of personal information.

Applicant subject to credit and underwriting approval. Not all applicants will be approved for financing. Receipt of application does not represent an approval for financing or interest rate guarantee. Refinancing your mortgage may increase costs over the term of your loan. Restrictions may apply. All information provided in this publication is for informational and educational purposes only, and in no way is any of the content contained herein to be construed as financial, investment, or legal advice or instruction. Citywide Home Mortgage does not guarantee the quality, accuracy, completeness or timelines of the information in this publication. While efforts are made to verify the information provided, the information should not be assumed to be error-free. Some information in the publication may have been provided by third parties and has not necessarily been verified by Citywide Home Mortgage. Citywide Home Mortgage, its affiliates and subsidiaries do not assume any liability for the information contained herein, be it direct, indirect, consequential, special, or exemplary, or other damages whatsoever and howsoever caused, arising out of or in connection with the use of this publication or in reliance on the information, including any personal or pecuniary loss, whether the action is in contract, tort (including negligence) or other tortious action.

Coleen TeBockhorst NMLS ID: 274205 Copyright © 1998-2025 Guaranteed Rate, Inc. D/B/A Citywide Home Mortgage. All rights reserved.

For licensing information, go to: www.nmlsconsumeraccess.org.

NMLS License #2611 – 3940 N Ravenswood Chicago, IL 60613. (866) 508-5515. Equal Housing Lender.

Licensing | Privacy | Terms of Use

Copyright © 2026 · Powered by MySMARTblog

Copyright © 2026 · Genesis Sample Theme on Genesis Framework · WordPress · Log in