CTeBockhorst's Blog

The Mortgage and Real Estate Scoop

  • Home
  • About
  • Blog
  • Resources
    • Calculators
    • Download My eGuide Today!
    • First Time Buyer Tips
    • First Time Seller Tips
    • Loan Checklist
    • Loan Process
    • Loan Programs
    • Home Appraisal
    • Home Inspection
    • What to Expect at a Loan Closing: A Step-by-Step Guide
  • Apply
  • Reviews
    • Read My Reviews
    • Zillow Reviews
    • Leave a Review
  • Contact

What You Need To Know About Your Home Appraisal And Your Mortgage

May 17, 2023 by Coleen TeBockhorst

What You Need To Know About Your Home Appraisal And Your MortgageWhen buying a home, there are certain steps a buyer should go through before the home sale is official. First the buyer makes the offer, then the offer is accepted.

Next the buyer schedules the inspection and home appraisal. Finally, everyone is ready for closing.

It’s easy to overlook the impact of some of these steps, but when it comes to a mortgage, the home appraisal is actually quite important. Banks want to see that they are lending money for an investment that is worthwhile, so that appraisal is a crucial step to getting financing. Here is what buyers need to know about how the appraisal could affect their mortgages.

Understanding The Home Appraisal Process

The home appraisal gives a home valuation expert the chance to evaluate the home a buyer’s considering to determine its market value. Home appraisers are highly trained, state-licensed professionals that know how to evaluate homes and assign value to them.

The appraiser will use various approaches to determine the final appraised value. The appraisal typically happens after an offer on the home was approved but before the lender loans the money.

The Appraisal And Mortgage Approval

The appraisal is one factor that a mortgage lender considers when deciding whether or not to approve a final loan request. Even if a borrower had preapproval, a low appraisal could cause the mortgage to fall through.

Why is this? A lender only wants to lend enough to cover what the home’s actual value, and if the appraisal comes in lower than what the borrower is asking for, the lender can deny the loan.

If the lender does not deny the loan completely, they may refuse to lend more than the home’s value. In order to buy the home at the agreed price, the buyer may need to come up with the difference in cash at closing.

What Can Buyers Do If The Appraisal Is Low?

If an appraisal comes in low on the home someone wishes to buy, the buyer shouldn’t panic. It is possible to get a new appraisal at a higher value.

First, consider the condition of the home. Did the seller let some things fall into disrepair? If the seller fixes those items, a new appraisal may be higher.

Does the home look rundown or cluttered? This shouldn’t affect the appraisal, but it can sometimes cause the appraiser to trend lower. Sometimes, simply asking for a second opinion might get a slightly different appraised value.  That said, if the appraisal is low, make sure to evaluate the purchase price. Is it in line with current market conditions and the overall condition of the home?

If the answer to that question is no, then the offer may be too much for the home. The appraisal, in this case, gives the buyer the opportunity to reevaluate the purchase decision.

When it comes to mortgage approval, the appraisal is one of the critical steps in the process. If a buyer has shopped wisely, the home should pass with flying colors, and soon the home sale process will be over.  As always, your trusted mortgage professional is the best resource for appraisal information in your local market.

Filed Under: Mortgage Tagged With: Appraisal, Mortgage, Value

Buying A Home With Cash Versus Low Interest Rate Mortgages

May 16, 2023 by Coleen TeBockhorst

Buying A Home With Cash Versus Low Interest Rate MortgagesWhen deciding whether to buy a home with cash or to obtain a low-interest rate mortgage, there are several factors to consider. A cash offer can be very competitive in a real estate market, as it can give the buyer a significant advantage over buyers who need to obtain financing through a mortgage.
Here are additional advantages and disadvantages of both.

Advantages of buying a home with cash:

  • You own the property outright, which means no mortgage payments are necessary.
  • You may be able to negotiate a lower purchase price if you’re able to pay in cash.
  • You avoid interest charges and fees associated with a mortgage.

Disadvantages of buying a home with cash:

  • You may tie up a significant amount of your liquid assets in the property.
  • If you need cash for emergencies or investments, it may be difficult to access it if it’s all tied up in your home.
  • You may miss out on the opportunity to leverage your credit to earn a higher rate of return on your investments.

Advantages of obtaining a low-interest rate mortgage:

  • You can preserve your liquid assets for other investments or emergencies.
  • You may be able to earn a higher rate of return on your investments than the interest rate on your mortgage.
  • You can take advantage of tax benefits associated with mortgage interest deductions.

Disadvantages of obtaining a low-interest rate mortgage:

  • You will have to make regular mortgage payments, which may be a strain on your budget.
  • You may end up paying more with the interest charges over the life of the loan than if you had bought the home with cash.
  • You may be required to put down a larger down payment or pay mortgage insurance premiums.

The decision to buy a home with cash or obtain a low-interest rate mortgage depends on your personal financial situation and goals. If you have the cash available and want to own your home outright, buying with cash may be the right choice for you. However, if you prefer to preserve your liquid assets and have the ability to earn a higher rate of return on your investments, a low-interest rate mortgage may be the better option. It’s important to note, however, that a cash offer may not always be the most competitive offer in every situation. In some cases, a seller may be more interested in accepting a higher offer that is contingent on financing, rather than a lower cash offer. It depends on the specific circumstances of the sale and the preferences of the seller.

Filed Under: Mortgage Tagged With: Cash or Finance, Interest Rates, Mortgage

What’s Ahead For Mortgage Rates This Week – May 15, 2023

May 15, 2023 by Coleen TeBockhorst

What's Ahead For Mortgage Rates This Week - May 15, 2023Last week’s scheduled economic reporting included readings on inflation, consumer sentiment, and weekly readings on mortgage rates and jobless claims.
Inflation Rate Rises in April, Slower Pace Expected in Coming Months

The  U.S. Labor Department reported the month-to-month pace of inflation rose by 0.40 percent in April and matched analysts’ expectations. April’s reading surpassed the March reading of 0.10 percent month-to-month inflationary growth. Inflation rose by 4.90 percent year-over-year in April. Analysts expect inflationary growth to continue, but at a slower pace through 2023.

Core inflation, which excludes volatile food and fuel sectors, rose at a month-to-month pace of 0.40 percent in April, which matched expectations and the March reading. Year-over-year core inflation rose by 4.90 percent in April as compared to the expected reading of 5.00 percent and the March reading of 5.00 percent.

Mortgage Rates Fall as Jobless Claims Rise

Freddie Mac reported lower average mortgage rates last week as rates for 30-year fixed-rate mortgages fell by four basis points to 6.35 percent. Rates for 15-year fixed-rate mortgages averaged one basis point lower at 5.75 percent. First-time jobless claims rose with 264,000 claims filed as compared to the expected reading of 245,000 claims and the prior week’s reading of 242,000 initial jobless claims filed.

As inflation slows, rapidly rising rental rates and home prices are also expected to increase at a slower pace. As homeownership becomes more affordable, fewer families will rely on rental homes. Less demand for rentals should help with easing very high rental rates seen in many metro areas. In general, more affordable housing choices could help ease housing challenges in areas with few affordable housing options.

The preliminary consumer sentiment survey for May reflects less consumer enthusiasm for current economic conditions. The initial index reading for May is 57.7, which fell short of the expected reading of 63.0 and April’s index reading of 63.5. May’s reading was the lowest since November 2022.

What’s Ahead

This week’s scheduled economic reporting includes readings on sales of previously-owned homes, housing market conditions, housing starts, and building permits issued. Weekly readings on mortgage rates and jobless claims will also be released.

Filed Under: Financial Reports Tagged With: Case Shiller, Financial Report, Mortgage Rates

Should You Help Your Kids Pay for Their Mortgage?

May 12, 2023 by Coleen TeBockhorst

Should You Help Your Kids Pay for Their Mortgage?Whether or not to help your kids pay for their mortgage is a personal decision that depends on your financial situation, your relationship with your children, and your beliefs about financial independence.
It’s important to evaluate your own financial situation before deciding whether to help your kids pay for their mortgage. Make sure that you can afford to provide financial assistance without jeopardizing your own financial security. Your relationship with your children can also be a factor in your decision. If you have a close relationship with your children and want to help them achieve their financial goals, then providing financial assistance may be a good option.

Some parents believe that their children should be financially independent and not rely on them for financial support. If you hold this belief, you may not want to provide financial assistance to your children. If you do decide to help your kids pay for their mortgage, it’s important to set clear terms and boundaries. Will you provide a loan that needs to be repaid or a gift? How much will you provide? Will you be a co-signer on the mortgage?

When Parents Might Want to Help with a Child’s Mortgage

Below are a few situations where parents might want to consider helping their child with their mortgage:

  • First-time homebuyers: If your child is a first-time homebuyer, they may not have enough savings or credit history to qualify for a mortgage on their own. In this case, you might want to consider providing a loan or gift to help them with their down payment or closing costs.
  • Financial difficulties: If your child is experiencing financial difficulties, such as a job loss or unexpected expenses, they may struggle to make their mortgage payments. Providing financial assistance in these situations can help them avoid foreclosure and maintain their financial stability.
  • Inheritance: Some parents choose to leave an inheritance to their children that can be used towards a down payment on a home. This can be a way to help their children achieve financial independence and build wealth.
  • Family home: If your child wants to buy the family home, you may want to consider providing financial assistance to help them keep the property in the family.

Tax Repercussions

There may be tax repercussions when parents help their children with their mortgage. Here are some things to consider:

Gift tax: If you give your child more than the annual gift tax exclusion amount, you may be subject to gift tax.

Income tax: If you lend money to your child to help with their mortgage and charge them interest, you will need to report the interest income on your tax return. Your child may also be able to deduct the mortgage interest on their tax return.

Capital gains tax: If you gift your child a property that will appreciate in value, they may be subject to capital gains tax when they sell the property. However, if they inherit the property from you, they will receive a step-up in basis, which means they will only pay capital gains tax on the appreciation that occurs after they inherit the property.

The decision of whether to help your kids pay for their mortgage is a personal one that should be made after careful consideration of all the factors involved.

In any of these situations, it’s important to consider your own financial situation and to fully understand the tax implications of helping your child with their mortgage and set clear terms and boundaries for the financial assistance you provide.

Filed Under: Mortgage Tagged With: Helping Your Children, Mortgage, Taxes

Should I Airbnb My Home?

May 11, 2023 by Coleen TeBockhorst

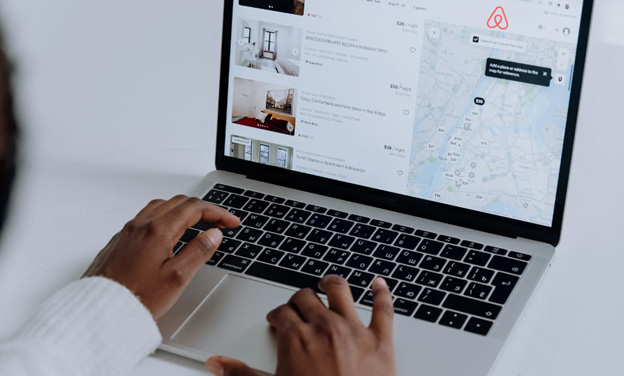
Should I Airbnb My HouseOne of the main reasons people Airbnb their homes is to earn extra income. By renting out their homes to guests, hosts can earn money that can be used to pay bills, save for a vacation, or invest in their future. The decision to Airbnb your home ultimately depends on your personal circumstances and preferences.
Here are some factors to consider that can help you make an informed decision:

Legal Requirements: Before you decide to list your home on Airbnb, make sure you are legally allowed to do so in your area. Check your local regulations, zoning laws, and HOA rules to ensure that short-term rentals are permitted. Failure to comply with these regulations could result in legal penalties and fines.

Financial Considerations: Renting out your home on Airbnb can be a great way to earn extra income, but it’s important to consider the financial costs and benefits. Consider the amount of time and money you will need to spend to get your home ready for guests, such as cleaning fees and repairs. Also, consider the opportunity cost of not using your home during the rental period.

Property Management: If you’re planning to rent out your home while you’re away, it’s important to have someone who can manage the property and handle any issues that arise with guests. This may require hiring a property manager or cleaning service, which will add to your costs.

Increased Wear and Tear: Renting out your home on Airbnb can result in increased wear and tear on your property, which may require more frequent repairs and maintenance. This can be especially true if you have multiple guests staying in your home on a regular basis.

Safety and Security: Airbnb offers various safety features and guidelines to protect hosts and guests, but there are still risks associated with hosting strangers in your home. Make sure you have adequate insurance coverage and take necessary safety precautions, such as locking up valuables and installing smoke detectors and carbon monoxide detectors.

If you feel comfortable with the above considerations and believe that renting out your home on Airbnb is a good fit for you, then it could be a worthwhile decision. However, if you have any reservations or concerns, it may be best to explore other options for earning extra income.

Filed Under: Mortgage Tagged With: Airbnb, Mortgage, Real Estate Investments

What is Cash to Close?

May 10, 2023 by Coleen TeBockhorst

What is Cash To Close“Cash to Close” refers to the total amount of money that a homebuyer needs to bring to the closing table to complete the purchase of a property. It includes the down payment, closing costs, and other fees associated with the home purchase.
How is it Calculated?

The cash to close amount is calculated by subtracting any applicable credits, such as earnest money or seller contributions, from the total amount of funds needed to complete the transaction. The resulting figure represents the final amount of cash that the buyer needs to bring to the closing.

It’s important for homebuyers to carefully review their “Cash to Close” statement before closing to ensure that they have enough funds available to cover the required amount. The statement will typically be provided by the lender or title company several days before the closing date.

The Difference Between Cash to Close and Closing Costs

Cash to close and closing costs are both important concepts in the home buying process, but they refer to different things.

Cash to close refers to the total amount of cash that a homebuyer needs to bring to the closing table to complete the purchase of a property. This includes the down payment, closing costs, prepaid expenses (such as property taxes and homeowners insurance), and any other fees associated with the home purchase.

Closing costs are the fees and expenses associated with obtaining a mortgage loan and closing the real estate transaction. They can include loan origination fees, appraisal fees, title search and insurance fees, attorney fees, and other charges. Closing costs are typically paid at the closing table, but they can sometimes be included in the mortgage loan amount.

Do I Need Actual Cash to Close?

While the term “Cash to Close” may suggest that you need to bring actual physical cash to the closing table, in reality, you typically do not need to bring cash. Most real estate transactions are settled using wire transfers, certified or cashier’s checks, or electronic transfers, rather than physical cash.

When you receive the “Cash to Close” statement, it will provide you with the total amount of funds needed to complete the transaction. You will then typically work with your lender and/or closing agent to arrange for the transfer of these funds to the appropriate parties.

It’s important to note that the exact payment methods and requirements may vary depending on the specific transaction and location. You should work closely with your lender and/or closing agent to ensure that you understand the payment process and have the necessary funds available in the appropriate form.

Filed Under: Mortgage Tagged With: Cash to Close, Closing Costs, Mortgage

What Is A Mechanic’s Lien?

May 9, 2023 by Coleen TeBockhorst

What is A Mechanics LienA mechanic’s lien is a legal claim placed on a property by a contractor, subcontractor, or supplier who has provided labor, materials, or equipment to improve the property. The lien serves as security for the payment of the debt owed to the party who provided the services or materials.
Mechanic’s liens are typically used in the construction industry, where contractors and subcontractors may perform work on a property and then have difficulty obtaining payment from the property owner. The lien provides the contractor with a legal means to collect payment for their work by placing a hold on the property until the debt is satisfied.

How a Mechanic Lien is Placed

To initiate a mechanic’s lien, the contractor or supplier must follow a specific set of procedures, which can vary depending on the jurisdiction. Generally, these procedures involve filing a notice of claim with the appropriate government office, notifying the property owner of the claim, and giving the owner an opportunity to dispute the claim.

If the claim is not disputed, the lien will remain on the property until the debt is paid. If the debt is not paid, the lien can be enforced through legal means, such as a foreclosure sale.

Reasons a Mechanic Lien Would be Placed

There are several reasons why a mechanic’s lien may be placed on a property:

  • Non-payment: The most common reason for placing a mechanic’s lien is non-payment. A contractor, subcontractor, or supplier may place a lien on the property if they have not been paid for their work, materials, or services.
  • Breach of contract: If a property owner breaches a contract by failing to pay for work that has been completed, a contractor or supplier may place a lien on the property.
  • Unpaid taxes or fees: Mechanic’s liens may also be placed on a property if the property owner has not paid property taxes, assessments, or other fees associated with the property.
  • Fraudulent or deceptive practices: In some cases, a mechanic’s lien may be placed on a property if the property owner engaged in fraudulent or deceptive practices, such as misrepresenting their financial position or misrepresenting the scope of the work that was required.
  • Dispute over work performed: Occasionally, a dispute may arise between a property owner and a contractor or supplier over the work that was performed. In such cases, a mechanic’s lien may be placed on the property as a way to resolve the dispute and secure payment for the work that was completed.

It is important to note that the laws surrounding mechanic’s liens can vary from state to state, and the specific reasons for placing a lien may also differ depending on the jurisdiction.

Mechanics’ liens can be complicated, and the laws surrounding them can vary from state to state. Therefore, it is recommended that contractors and property owners consult with an attorney who is familiar with the relevant laws in their jurisdiction.

Filed Under: Mortgage Tagged With: Contractor, Debt, Mortgage

What’s Ahead For Mortgage Rates This Week – May 8, 2023

May 8, 2023 by Coleen TeBockhorst

What's Ahead For Mortgage Rates This Week - May 8, 2023Last week’s economic news included reporting on construction spending, the Federal Reserve’s decision to raise its benchmark interest rate, and weekly readings on mortgage rates and jobless claims.
Construction Spending Increases in March

The Commerce Department reported that month-to-month construction spending rose by 0.30 percent and year-over-year construction spending increased by $1.83 trillion. Residential construction fell by -0.20 percent in March, which was the tenth consecutive monthly decline in residential construction spending. Non-residential construction spending rose by 0.70 percent in March for the ninth gain in the past 10 months.

Fed Raises Key Interest Rate Range

Federal Reserve policymakers raised the Fed’s key interest rate range by a quarter point to 5.00-5.25 percent at its Federal Open Market Committee meeting held on Tuesday and Wednesday. This was the tenth consecutive rate hike as the Fed continues efforts to control inflation.

Analysts noticed a subtle change in the tone of the Fed’s post-meeting statement and suggested that the less aggressive tone used in the post-meeting statement signaled a softer approach to raising the Fed’s benchmark rate. While some Fed policymakers recently suggested the possibility of a recession, Fed Chair Jerome Powell disagreed: “This is not my own most likely case.” Chair Powell also said that he expected economic growth in 2023 but at a slower pace.

Mortgage Rates Mixed, Jobless Claims Rise

Freddie Mac reported mixed movement of mortgage rates last week as the average rate for 30-year fixed-rate mortgages fell by four basis points to 6.39 percent. The average rate for 15-year fixed-rate mortgages rose by five basis points to 5.76  percent.

Initial jobless claims rose to 242,000 claims filed last week as compared to the prior week’s reading of  229,000 first-time claims filed. Continuing jobless claims fell with 1.81 million claims filed as compared to the prior week’s reading of 1.84 million claims filed.

What’s Ahead

This week’s scheduled economic news includes readings include readings on inflation and consumer sentiment. Weekly readings on mortgage rates and jobless claims will also be published.

Filed Under: Financial Reports Tagged With: Case Shiller, Financial Report, Mortgage Rates

5 Important Questions to Ask When Buying New Construction

May 5, 2023 by Coleen TeBockhorst

Questions to Ask When Buying New ConstructionBuying a new home is exciting. Buying a brand new home can be even more so with the realization of being the first owner and possibly being able to choose your own layout and finishes. The prospect of owning new construction is definitely exciting, but it doesn’t come without its own set of questions.
If you’re in the market for a new home, and considering new construction, make note of the questions below when you begin your property search.

What Are The Long Term Plans For The Community?

Unless you’re looking at custom homes on acreage, it’s likely new construction in your area will be located in a new development or in a master planned community. With this in mind, feel free to ask about the plans for the community.

If it’s a large area, find out if any subdivisions are planned. If there are only a few houses built so far, it’s likely to mean lots of construction in the months to come – which means a lot of noise and construction traffic.

Also ask about the builder. If they’re well known and respected, it’s unlikely they’ll lose funding and the community will then continue on as planned.

What Are The Homeowners Association’s Rules And Regulations?

Many new developments and master planned communities come with a set of rules and regulations set by a homeowners association. If you’ve never lived in a community with an HOA, it’s important to find out the rules before investing in it.

The bylaws and the CC&Rs will let you know what is and isn’t allowed in the community (especially when it comes to the exterior of your home). You’ll also want to find out when the HOA fee begins – in some communities, it can start before the home is even finished.

Are There Any Buyer Or Financial Incentives?

If the community or development is still in the early stages, there might be incentives (like a buyer discount, builder upgrades or other financial incentives or freebies) for buyers.

Sometimes these offers come with a catch – where something is expected from the buyer in return for the incentive – but it’s important to ask about any offers that may be available, especially if the community is still up and coming.

Are Warranties Provided?

New homes often come with different warranties. Ask if a workmanship and structural warranty come with the home.

A workmanship warranty (or builder’s warranty) is a warranty for newly constructed homes that offer limited coverage on workmanship and components of the home like windows, siding, roofs, doors, plumbing, electrical and HVAC. Traditionally, a workmanship warranty will cover a one or two year period; another likely warranty is a structural warranty, which covers the structure of a home.

If a warranty is provided, make sure you know exactly what is and isn’t covered and how much you’re responsible for in case of any issues.

Can you connect me with some current homeowners?

Just as you would check reviews before buying an item online or booking a service, the same can be said for a home builder. Just because the product is a shiny new home doesn’t mean you shouldn’t do your due diligence and check references before making a large investment.

While it’s likely that the builder will provide glowing reviews, checking reference and review websites and even knocking on the doors of current homeowners will provide additional information and give you a wider understanding of the builder and its practices. Talking to current homeowners will provide information about the actual community.

New construction is exciting, but you want to make sure you have all pertinent information before you go through with a home purchase. Your real estate professional will be able to help navigate the waters of new construction. 

Filed Under: Home Buyer Tips Tagged With: Home Buyer, New Construction, Questions to ask

How the Purchase and Refinance Mortgage Process Works

May 4, 2023 by Coleen TeBockhorst

How the Purchase and Refinance Mortgage Process WorksThe purchase and refinance mortgage processes are similar in many ways, but there are also some important differences. Here is a general overview of how each process typically works:

Purchase Mortgage Process

Determine your budget: Before you start shopping for a home, you need to figure out how much you can afford to spend. You can do this by calculating your monthly income, expenses, and debt, and getting pre-approved for a mortgage.

Find a property: Once you know your budget, you can start looking for homes that fit your criteria, whether that’s size, location, or other factors.

Make an offer: When you find a property you like, you can make an offer to buy it. This offer will include the price you’re willing to pay and any contingencies, such as inspections or financing.

Get a mortgage: If your offer is accepted, you’ll need to apply for a mortgage loan to pay for the property. You’ll need to provide documentation about your income, assets, and credit history.

Close the loan: Once your mortgage is approved, you’ll need to attend a closing to finalize the sale. This involves signing a lot of paperwork and paying closing costs, such as appraisal fees and title insurance.

Refinance Mortgage Process

Determine your goals: Before you start the refinance process, you need to determine why you want to refinance. Some common reasons include lowering your monthly payments, shortening your loan term, or cashing out equity.

Gather documentation: To refinance, you’ll need to provide documentation about your income, assets, and credit history, just like you did when you applied for your original mortgage.

Choose a lender: Once you have your documentation in order, you can start shopping around for a lender who offers the type of refinance you want, such as a rate-and-term refinance or a cash-out refinance.

Apply for the loan: After you choose a lender, you’ll need to submit a loan application and provide documentation to support your refinance goals.

Close the loan: Once your refinance is approved, you’ll need to attend a closing to finalize the loan. This involves signing paperwork and paying closing costs, such as appraisal fees and title insurance.

The purchase and refinance mortgage processes involve similar steps, but the specifics can vary depending on your situation and the type of loan you’re applying for. It’s important to work with a trusted lender who can guide you through the process and help you make informed decisions about your mortgage.

What are the Differences Between Purchasing and Refinancing a Home

While purchasing a home and refinancing a home both involve obtaining a mortgage, there are several key differences between the two processes. The primary goal of purchasing a home is to buy a property to live in or as an investment. The primary goal of refinancing a home is to replace an existing mortgage with a new one that offers more favorable terms.

The purchase process involves finding a property, making an offer, and going through the home buying process. Refinancing involves working with an existing mortgage lender or a new lender to replace an existing mortgage with a new one.

The timing of a home purchase is largely determined by the real estate market and the availability of properties that meet the buyer’s criteria. The timing of a refinance is largely determined by the borrower’s financial goals and the current interest rate environment.

Ultimately, the best decision for you will depend on your individual financial situation and goals. It is recommended to reach out to a real estate agent or mortgage originator who can provide personalized advice and guidance based on your specific needs and circumstances.

Filed Under: Mortgage Tagged With: Budgeting, Mortgage, Refinance

« Previous Page
Next Page »

Contact Coleen

Coleen Tebockhorst

Coleen TeBockhorst
coleen.tebockhorst@citywidehm.com

Senior Loan Officer

Call me! (612) 701-8512

NMLS #274205

Download My Mortgage eGuide today

CW Home Mortgage logo_White

Guaranteed Rate, Inc. DBA Citywide Home Mortgage

Categories

Our Location

10591 165th St. West
Lakeville MN, 55044

Connect With Me

This site is not authorized by the New York State Department of Financial Services. No mortgage loan applications for properties located in New York will be accepted through this site. Operating in the state of California as Guaranteed Rate, Inc. D/B/A Citywide Home Mortgage. If you are a California resident, please review our Privacy Policy to learn more about the categories and business purpose of personal information we may collect and your right to opt-out from the sale of personal information.

Applicant subject to credit and underwriting approval. Not all applicants will be approved for financing. Receipt of application does not represent an approval for financing or interest rate guarantee. Refinancing your mortgage may increase costs over the term of your loan. Restrictions may apply. All information provided in this publication is for informational and educational purposes only, and in no way is any of the content contained herein to be construed as financial, investment, or legal advice or instruction. Citywide Home Mortgage does not guarantee the quality, accuracy, completeness or timelines of the information in this publication. While efforts are made to verify the information provided, the information should not be assumed to be error-free. Some information in the publication may have been provided by third parties and has not necessarily been verified by Citywide Home Mortgage. Citywide Home Mortgage, its affiliates and subsidiaries do not assume any liability for the information contained herein, be it direct, indirect, consequential, special, or exemplary, or other damages whatsoever and howsoever caused, arising out of or in connection with the use of this publication or in reliance on the information, including any personal or pecuniary loss, whether the action is in contract, tort (including negligence) or other tortious action.

Coleen TeBockhorst NMLS ID: 274205 Copyright © 1998-2025 Guaranteed Rate, Inc. D/B/A Citywide Home Mortgage. All rights reserved.

For licensing information, go to: www.nmlsconsumeraccess.org.

NMLS License #2611 – 3940 N Ravenswood Chicago, IL 60613. (866) 508-5515. Equal Housing Lender.

Licensing | Privacy | Terms of Use

Copyright © 2026 · Powered by MySMARTblog

Copyright © 2026 · Genesis Sample Theme on Genesis Framework · WordPress · Log in