CTeBockhorst's Blog

The Mortgage and Real Estate Scoop

  • Home
  • About
  • Blog
  • Resources
    • Calculators
    • Download My eGuide Today!
    • First Time Buyer Tips
    • First Time Seller Tips
    • Loan Checklist
    • Loan Process
    • Loan Programs
    • Home Appraisal
    • Home Inspection
    • What to Expect at a Loan Closing: A Step-by-Step Guide
  • Apply
  • Reviews
    • Read My Reviews
    • Zillow Reviews
    • Leave a Review
  • Contact

What’s Ahead For Mortgage Rates This Week – November 18th, 2024

November 18, 2024 by Coleen TeBockhorst

With the release of the latest CPI and PPI data, inflation has increased month-to-month for the first time since March, marking the first rise in over seven months. The Federal Reserve has reiterated its goal of reducing inflation to a 2% target within a year. While this development doesn’t necessarily indicate an imminent interest rate hike, it suggests that current rates may remain unchanged for an extended period. Earlier optimism about a potential rate cut by the end of the year has significantly diminished in light of recent inflation figures and economic data. However, Retail Sales data presents a more positive outlook, showing continued economic growth ahead of the holiday shopping season.

Consumer Price Index

The consumer price index climbed 0.2% for the fourth month in a row, the government said Wednesday, matching the Wall Street forecast. The yearly rate of inflation crept up to 2.6% from 2.4%, marking the first upturn in seven months.

Producer Price Index

The PPI data met expectations overall but revealed that U.S. wholesale prices rose slightly faster in October. This suggests the Federal Reserve’s efforts to bring inflation back to low pre-pandemic levels may take longer than anticipated. Federal Reserve officials have described the recent uptick in inflation as a ‘bump,’ which could hinder the central bank from reducing high interest rates as quickly as Wall Street had hoped just a few months ago.

Retail Sales

Sales at retailers rose solidly in October and suggested the economy still has plenty of momentum heading into the holiday shopping season. Sales increased 0.4% last month, the government said Friday, and receipts in September were twice as strong as previously reported.

Primary Mortgage Market Survey Index

• 15-Yr FRM rates saw a decrease of -0.01% with the current rate at 5.99%
• 30-Yr FRM rates saw a decrease of -0.01% with the current rate at 6.78%

MND Rate Index

• 30-Yr FHA rates saw a 0.09% increase for this week. Current rates at 6.39%
• 30-Yr VA rates saw a 0.07% increase for this week. Current rates at 6.39%

Jobless Claims

Initial Claims were reported to be 217,000 compared to the expected claims of 220,000. The prior week landed at 221,000.

What’s Ahead

Preliminary S&P Global US Manufacturing PMI will be early on the release schedule marking the first large end-of-the-year preliminary report. Following that immediately is the University of Michigan Consumer Sentiment Report.
Filed Under: Financial Reports Tagged With: Financial Report, Jobless Claims, Mortgage Rates

Understanding the Difference Between Mortgage Brokers and Mortgage Lenders

November 15, 2024 by Coleen TeBockhorst

When you’re ready to buy a home, one of the first steps is securing a mortgage. While many people simply turn to their current bank for a loan, there are other options to consider that might provide better rates and terms for your situation. 
This is where understanding the difference between a mortgage broker and a mortgage lender can help. Both play essential roles in the home loan process, but they function in very different ways. Let’s break it down so you can determine which path might work best for you when seeking mortgage financing.

What is a Mortgage Lender?

A mortgage lender is a financial institution — like a bank, credit union, or online lender — that provides loans directly to borrowers. Lenders are the ones who have the capital to lend, and they are responsible for underwriting the mortgage, setting loan terms, and making the final decision about who is approved for a loan.

The key characteristics of a mortgage lender include:

  • Direct Loaning: The lender is the one who provides the funds for your mortgage. If you apply with a specific bank or credit union, they will assess your financial situation and decide whether you meet their loan requirements.
  • In-House Terms: Lenders typically offer a range of loan products but are limited to the types of loans they offer based on their guidelines. While they may offer several different loan options (such as FHA, VA, or conventional loans), you are limited to the loans they offer within their portfolio.
  • Interest Rates and Fees: Lenders set the interest rates and other fees associated with the loan. These rates can vary depending on your credit score, loan type, and the lender’s pricing.
  • Efficiency: Working with a lender can be more streamlined if you already have an existing relationship with them (for example, if you have a checking or savings account with the bank). In such cases, the process can be faster and more convenient since your financial information is already on file.

However, the main limitation of working directly with a lender is that you may not have access to a wide range of loan products. You might miss out on more favorable rates or terms that could be available elsewhere.

What is a Mortgage Broker?

A mortgage broker, on the other hand, does not lend money directly to you. Instead, they act as an intermediary between you and multiple lenders. Think of them as personal shoppers for mortgages. Their role is to find the best loan option for your financial situation by shopping around with different banks, credit unions, and other financial institutions.

Key characteristics of a mortgage broker include:

  • Access to Multiple Lenders: Unlike lenders, brokers are not tied to any specific financial institution. This means they can shop around and work with multiple lenders to find the best loan options for you, which could potentially lead to better rates, terms, and overall savings.
  • Expert Guidance: Brokers have experience navigating the complexities of the mortgage market and can help you make sense of your options. They can provide advice on which lenders might be the best fit for your situation and even suggest ways to improve your financial profile to help you qualify for a better loan.
  • Convenience: A broker does the legwork of gathering your financial information, comparing loan options, and submitting applications to multiple lenders on your behalf. This can save you a lot of time and effort, especially if you’re unsure of which lenders to approach.
  • Tailored Service: Brokers may also have access to niche loan products or lenders that you wouldn’t typically find on your own. If you have unique financial circumstances or need a more specialized loan, a broker might be able to find a more customized solution.

However, one thing to be aware of is that brokers may be compensated in different ways. Some may charge you a fee directly, while others are compensated by the lenders. This means it’s important to clarify how a broker is paid upfront to avoid any surprises.

The Pros and Cons of Brokers and Lenders

Ultimately, the decision between working with a mortgage lender or a broker comes down to your specific needs and preferences. If you prefer working directly with one institution and want a more streamlined process, a lender might be a good choice. But if you’re looking for more loan options, personalized advice, and assistance shopping around, a mortgage broker might offer better value.

Which One is Right for You?

Both mortgage brokers and lenders have their benefits depending on your unique situation. If you’re someone who values convenience and has an established relationship with a bank or credit union, working directly with a lender might be a more straightforward route. On the other hand, if you want more variety in loan products and value having an expert help you navigate the process, a mortgage broker could be a great fit.

Both professionals are focused on helping you secure the best financing for your home. The right choice depends on your preferences for customer service, loan flexibility, and whether you’re willing to work with one institution or multiple lenders.

Filed Under: Home Buyer Tips Tagged With: Home Buying, Mortgage Broker, Mortgage Lender

How Women Can Navigate the Path to Ownership with Confidence

November 14, 2024 by Coleen TeBockhorst

In recent years, single women have emerged as a powerful force in the real estate market, breaking barriers and taking control of their financial futures. According to recent data, single women now own more homes than single men, with nearly 20 million women homeowners in the U.S., representing a growing trend of resilience and empowerment. This surge in homeownership among women has come even in the face of economic challenges, including the financial fallout of the pandemic.
Whether you’re already envisioning your dream home or just starting your search, navigating the homeownership journey as a single woman comes with unique considerations. 

1. Assess Your Financial Health

The first step toward homeownership is a thorough assessment of your financial situation. Start by reviewing your credit score, savings for a down payment, and monthly budget. This will give you a clear picture of what you can comfortably afford. Understanding your finances also empowers you to make realistic homeownership goals that align with your current and future needs.

2. Explore Your Financing Options

The mortgage market can feel overwhelming, especially if you’re a first-time homebuyer. Fortunately, there are several programs available that can help make homeownership more accessible. These include:

  • FHA Loans: Known for lower down payment requirements and more flexible credit standards, making them ideal for solo buyers.
  • Conventional Loans: Best for those with strong credit and a larger down payment.
  • Down Payment Assistance Programs: Many states and local governments offer grants or loans that can help reduce your upfront costs.
  • First-Time Homebuyer Programs: These programs provide reduced interest rates, lower fees, or other forms of financial assistance for those purchasing their first home.

By exploring these options, you can find the program that best fits your financial situation, making the homeownership dream a reality.

3. Define Your Homebuying Vision

Homeownership is a personal decision, and your priorities might look different from those of other buyers. As a single woman, you’re in a unique position to design your homebuying journey around your specific needs, lifestyle, and goals.

Do you want a peaceful retreat in the suburbs, where you can unwind after a busy day? Or does the convenience and excitement of urban living, with proximity to work and social activities, better align with your goals?

By clearly defining your “must-haves” early in the process, you can focus your search on homes that reflect your vision for the future, making it easier to narrow down options and stay on track.

4. Build Your Support Network

Navigating the homebuying process on your own can feel overwhelming, but you don’t have to do it alone. Surround yourself with a reliable team of professionals who can guide and support you throughout your journey:

  • A real estate agent who understands your goals and the local market.
  • A loan officer who can help you evaluate financing options and walk you through the mortgage process.
  • Friends and family who can offer emotional support, share advice, and encourage you along the way.

This team of professionals, combined with the support of your loved ones, will provide the expertise and encouragement you need to make confident decisions throughout the home-buying process.

5. Stay Patient and Stay Informed

The real estate market is constantly evolving, with interest rates, inventory levels, and home prices fluctuating regularly. Staying informed about current market trends will help you make well-timed decisions and avoid the temptation to rush into a purchase.

Patience is key. Don’t feel pressured to settle for a property that doesn’t meet your needs, financial goals, or vision for the future. Trust that the right opportunity will come along if you remain proactive and informed.

Empowerment Through Homeownership

The rise of single women homeowners is a powerful reminder of the increasing financial independence and strength of women across the country. Homeownership represents more than just owning property; it’s about securing a stable future, building equity, and creating a space that truly reflects your unique lifestyle and aspirations.

With careful planning, the right support, and a clear vision, more women are leaping into homeownership, setting themselves up for long-term success. If you’re ready to begin your journey, know that the tools and resources are available to help you achieve your dream of homeownership.

Filed Under: Mortagage Tips Tagged With: Home Buying Journey, Women Homeowners, Women In Real Estate

Understanding the Components of Your Monthly Mortgage Payment

November 13, 2024 by Coleen TeBockhorst

If you’re new to homeownership, you might be wondering exactly what makes up the mortgage payment you’re sending each month. Beyond just the loan amount itself, there are several different components that all factor into your monthly mortgage payment. Understanding these components not only helps you see where your money is going but can also assist you in optimizing your mortgage and possibly securing a better rate.
1. Principal

The principal is the amount of money you originally borrowed to purchase the home. It represents the bulk of your loan balance and is paid down over the term of your mortgage. For example, if you buy a home for $200,000 and make a 20% down payment ($40,000), the remaining loan amount of $160,000 is your principal.

With each mortgage payment, a portion goes toward paying down the principal balance. As you continue to make payments, the principal balance decreases, which ultimately builds your home equity. The larger the down payment you make, the less you’ll owe in principal.

2. Interest

The interest portion of your mortgage payment is what the lender charges for the loan. Think of interest as the cost of borrowing money. This amount is calculated based on the interest rate, which is typically expressed as an annual percentage rate (APR). Your interest rate is determined by several factors including your credit score, the size of your down payment, and your loan type.

Interest is usually paid off at a higher rate in the early years of your mortgage and gradually decreases over time. In the early stages, more of your monthly payment goes toward interest, and less goes toward reducing the principal. Over time, as the balance of your loan decreases, the amount going toward interest also decreases.

3. Property Taxes

Property taxes are typically one of the largest components of your monthly mortgage payment. These taxes are levied by your local government (city, county, or municipality) and are based on the value of your property. The revenue from property taxes is used to fund local services like schools, emergency services, and infrastructure.

Lenders generally include property taxes in your monthly mortgage payment by setting up an escrow account. This means that a portion of your monthly payment goes into an escrow account, and the lender will pay your property taxes directly when they are due. Keep in mind that property tax rates can fluctuate from year to year, so your mortgage payment may adjust accordingly.

4. Homeowner’s Insurance

Homeowner’s insurance is designed to protect you and your property in case of damage or loss from events like fire, theft, or vandalism. Most mortgage lenders require that you have homeowner’s insurance before they approve the loan, as it helps ensure the value of the property is protected.

Much like property taxes, homeowners insurance premiums are often included in your monthly mortgage payment. Your lender will then pay the insurance premiums on your behalf, through the escrow account. If you live in an area prone to natural disasters (such as floods, earthquakes, or hurricanes), you may be required to have additional insurance coverage, which can increase your monthly payment.

5. Private Mortgage Insurance (PMI)

If you put down less than 20% when purchasing your home, you may be required to pay Private Mortgage Insurance (PMI). PMI protects the lender in case you default on your loan. While it benefits the lender, it can add an additional cost to your monthly mortgage payment.

PMI is typically calculated as a percentage of the loan amount and is included in your monthly payment. However, it’s possible to have PMI removed once you have built up enough equity in your home (usually after you’ve paid down your loan balance to 80% of the home’s original value). Depending on the type of loan, there are different ways PMI may be structured — it could be a monthly premium, a one-time upfront premium, or a combination of both.

6. Homeowner’s Association (HOA) Fees

If you live in a community with a Homeowner’s Association (HOA) — such as a condominium, townhouse, or gated community — you might be required to pay HOA fees. These fees go toward maintaining common areas, landscaping, and providing amenities like pools or gyms.

HOA fees can be a fixed monthly fee or an annual fee, and they can vary greatly depending on the community. In some cases, your lender may include these fees as part of your monthly mortgage payment, in which case they are also paid through your escrow account. It’s important to understand your HOA fees upfront, as they can significantly impact your monthly housing costs.

Putting It All Together: Understanding Your Monthly Mortgage Payment

Now that you know the key components that make up your mortgage payment, you can see that it’s not just about the amount you borrowed. Here’s a recap of what you’re likely paying for each month:

  • Principal: The amount you borrowed for the home, which is gradually paid down over time.
  • Interest: The cost of borrowing the money, decreases as you pay down the loan.
  • Property Taxes: Local taxes that help fund community services.
  • Homeowner’s Insurance: Insurance to protect your property from damage or loss.
  • Private Mortgage Insurance (PMI): Required if you put down less than 20%, protecting the lender in case of default.
  • Homeowner’s Association Fees (HOA): Fees for maintaining shared community spaces and amenities.

Understanding these components can help you get a better idea of how much home you can afford and where you can make adjustments to improve your overall mortgage terms. For example, paying down your loan faster can reduce your principal and lower the amount you pay in interest. Additionally, making a larger down payment can help you avoid paying PMI, which will lower your monthly costs.

If you’re in the process of buying a home or refinancing your mortgage, understanding these components is an important step in making informed financial decisions. Knowing where your money is going can help you assess your options and set you up for long-term success.


Filed Under: Mortgage Tagged With: Home Buyers, Mortgage Payment, Mortgage Tips

What’s Ahead For Mortgage Rates This Week – November 12th, 2024

November 12, 2024 by Coleen TeBockhorst

Big inflation reports for the coming week with both CPI and PPI on the schedule. We should expect the data to remain within expectations given the latest reports from both the PCE Index and GDP estimates. The Federal Reserve has still remained hawkish and the last rate decision the expectation is the current rates should maintain. However with the inflation being very close to the Federal Reserve’s target inflation rate and the expected “soft landing” on the horizon. The outlook is optimistic for another round of rate cuts in future.
Federal Reserve Rate Decision

In the face of slowing inflation and strong consumer spending, the Federal Reserve announced that it will keep the interest rate steady, holding the benchmark borrowing rate to a range of 5.2%5 to 5.5%.

Consumer Credit

The numbers: The amount of borrowing by U.S. consumers in September rose a scant 1.4%, but the increase was tied mostly to student loans as Americans scale back on the use of credit cards. Consumer credit increased by $6.0 billion in September, Federal Reserve data showed. Economists had expected a $13 billion increase, according to a Wall Street Journal forecast.

Primary Mortgage Market Survey Index

?15-Yr FRM rates seeing a week-to-week change of 0.01% with the current rate at 6.00%.
?30-Yr FRM rates seeing a week-to-week change of 0.07% with the current rate at 6.79%

MND Rate Index

?30-Yr FHA rates week to week seeing a -0.32% change for this week. Current rates at 6.30%
?30-Yr VA  rates week to week seeing a -0.32% change for this week. Current rates at 6.32%

Jobless Claims

Initial Claims were reported to be 221,000 compared to the expected claims of 220,000. The prior week was 218,000.

What’s Ahead

Consumer Price Index and Producer Price Index inflation ahead. There are no other influential reports on the schedule.

Filed Under: Financial Reports Tagged With: Financial Report, Jobless Claims, Mortgage Rates

Supporting Veterans on Their Path to Homeownership And Honoring Our Heroes

November 11, 2024 by Coleen TeBockhorst

As we take time to honor Veterans Day, we extend our deepest respect and gratitude to the brave men and women who have served our country in uniform. Veterans Day is more than a day of remembrance; it is a chance to reflect on the sacrifices made by those who have protected the freedoms we cherish and to recognize the resilience, dedication, and strength they embody.
For us in the mortgage industry, this day holds special meaning. Many veterans and their families have sacrificed so much to ensure the security of others. It is our privilege and duty to provide support that makes a difference in their lives—whether through tailored loan options like VA loans, guidance on homeownership, or simply listening and understanding their unique needs.

On this Veterans Day, we reaffirm our commitment to serving those who have served us. We encourage everyone to join us in expressing appreciation for our nation’s veterans—not just today but every day. Let us stand together in gratitude and continue to support their journey to achieving the American dream of homeownership.

Thank you, veterans, for your service, courage, and the legacy you continue to inspire.

Filed Under: Holidays Tagged With: Honoring Heroes, Support Our Veterans, Veterans Day

How Mortgages Compare To Other Loans

November 8, 2024 by Coleen TeBockhorst

Planning to buy a home, finance a car, or cover unexpected expenses? Many loan options exist to help you achieve your financial goals, but choosing the right one can be challenging. Here’s a breakdown of the most popular types of loans, their unique characteristics, and what you need to know to make the best choice for your financial future.
Different Types of Loans

There are several types of loans, each designed to meet different needs:

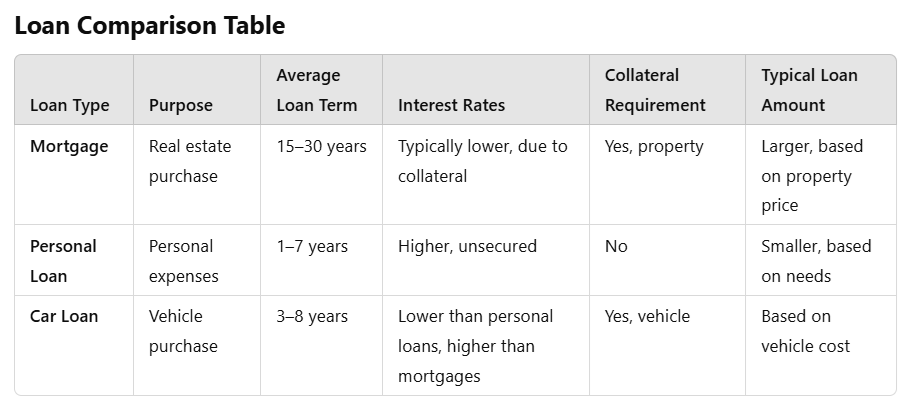
  • Mortgages: Secured loans used for purchasing real estate. Mortgages typically come with lower interest rates and extended terms (15–30 years) because they use the property itself as collateral.
  • Personal Loans: Unsecured loans commonly used for expenses like debt consolidation, home improvements, or travel. Personal loans usually carry higher interest rates and shorter terms (1–7 years) because they don’t require collateral.
  • Car Loans: Secured loans for purchasing vehicles. Like mortgages, car loans use the vehicle as collateral, often resulting in lower interest rates than unsecured loans, with terms of 3–8 years.


What Makes Mortgages Unique?

A mortgage is specifically designed for real estate purchases and typically has a longer term (15–30 years) than other loans. Unlike personal or car loans, a mortgage uses the property being purchased as collateral. This results in lower interest rates but involves a more detailed application process and a larger financial commitment. Mortgages are the go-to option for anyone looking to own property.

Types of Mortgages

There are several mortgage options available, each with different benefits:

  1. Fixed-Rate Mortgages (FRMs):
    • Interest rate remains the same throughout the loan term, offering stable monthly payments.
    • Ideal for long-term homeowners.
  2. Adjustable-Rate Mortgages (ARMs):
    • Interest rate starts lower but fluctuates based on market conditions.
    • Suitable for short-term homeowners or those planning to refinance.
  3. Conventional vs. Government-Backed Mortgages:
    • Conventional Loans: Not government-backed, follow Fannie Mae and Freddie Mac guidelines, and require good credit.
    • Government-Backed Loans: (FHA, VA, USDA) Easier to qualify for, often with lower credit requirements, making them accessible to first-time buyers or veterans.

How Personal Loans Differ from Mortgages

Personal loans are versatile and can be used for almost any purpose. Unlike mortgages, they’re unsecured, meaning no property or assets are required as collateral. While they’re easy to get, they’re less suited for major purchases like real estate due to shorter terms and higher interest rates. Personal loans are often used for debt consolidation, home improvements, or covering unexpected expenses.

Key Features of Personal Loans

  • Unsecured: No collateral required, increasing accessibility but often resulting in higher interest rates.
  • Flexible Use: Can be used for almost any expense, from medical bills to vacations.
  • Quick Approval: Typically faster to approve than mortgages, with some lenders offering same-day approval.
  • Fixed Interest Rates: Most personal loans have fixed interest rates and predictable payments.
  • Flexible Loan Terms: Allows borrowers to choose a repayment schedule that fits their financial goals.

How Car Loans Differ from Mortgages

Car loans share one similarity with mortgages: collateral. However, they’re specifically for vehicles, with lower loan amounts and shorter terms. Car loans use the vehicle itself as security, typically resulting in lower interest rates than unsecured loans but higher rates than mortgages.

Key Features of Car Loans

  • Depreciation: Vehicles lose value over time, so it’s important to consider a car’s depreciation rate before taking out a loan.
  • Secured Loan: The vehicle serves as collateral, which generally lowers the interest rate.
  • Interest Rates: Rates depend on credit score, down payment, loan term, and the vehicle’s age and type.

Understanding Loan Types

Choosing the right loan starts with understanding how each loan type works, including its purpose, terms, and impact on your finances. When considering a loan, factor in how much interest you’ll pay, how it will affect your credit score, and how it aligns with your long-term financial goals.

To ensure a smart financial decision, consider consulting a loan officer who can help navigate your options and align your choice with your financial goals. Whether it’s your first mortgage or an unsecured personal loan, make sure you understand the terms and requirements before signing.

Filed Under: Mortagage Tips Tagged With: Loan Options, Mortgage, Mortgage Vs Personal Loan

What Are Your Options When Funding Your Down Payment?

November 7, 2024 by Coleen TeBockhorst

Buying a home is a big milestone, and for many, saving for a down payment can feel like a major hurdle. Fortunately, there are several ways to make that down payment happen. Whether through savings, family gifts, 401(k) funds, or even second mortgages, understanding your options is key to making the best financial choice. Let’s break down each of these options so you can explore what works best for you.
1. Family Gifts for a Down Payment

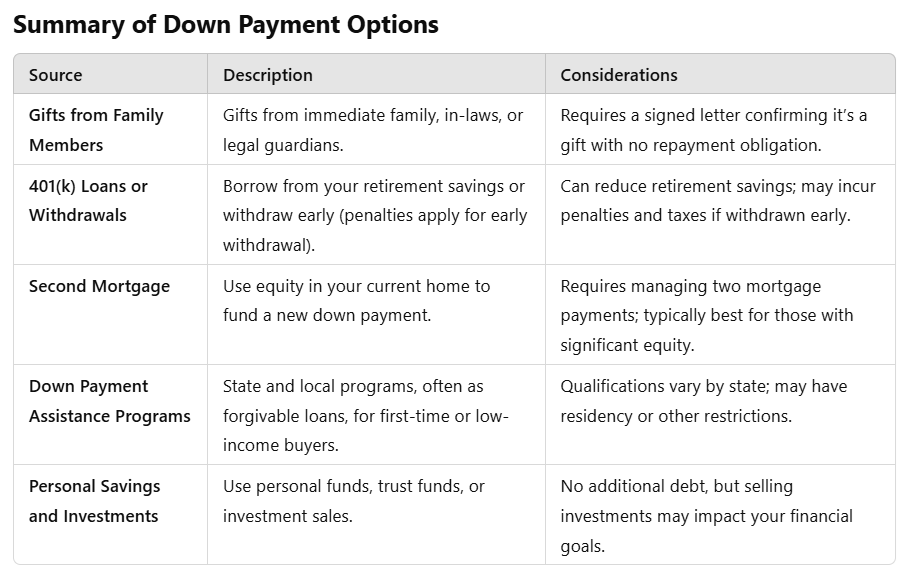
For many homebuyers, especially first-time buyers, gifted money from family members is a valuable resource. However, lenders have specific guidelines about gift funds, so it’s essential to understand how these gifts work in the context of a mortgage.

  • Who Can Gift Money?
    • Immediate family members: Parents, siblings, and grandparents.
    • Relatives by marriage: In-laws can sometimes help out as well.
    • Legal guardians or close friends: With proper documentation, these individuals may also gift funds for your down payment.
  • Documentation Requirements:
    Lenders typically require a signed letter from the person giving the gift, confirming that the money is a gift and does not need to be repaid. Some loan programs also have restrictions on who can provide the gift, so be sure to check with your lender.

2. Using Your 401(k) for a Down Payment

Using retirement funds, like your 401(k), is another option to access funds for a down payment, but it’s essential to weigh the pros and cons.

  • 401(k) Loan: You can borrow up to 50% of your vested balance (up to $50,000). The advantage is that you’re borrowing from yourself and paying yourself back with interest.
  • 401(k) Early Withdrawal: If you withdraw money before 59½, you’ll face a 10% penalty and owe income taxes on the withdrawn amount. This method provides fast access to cash but can significantly impact your retirement savings.

Tip: Make sure to discuss with a financial advisor before taking from your 401(k), as it can affect your retirement timeline.

3. Taking a Second Mortgage

If you already own a home with significant equity, a second mortgage can provide funds for a down payment on a new property.

  • Home Equity Loan or Line of Credit: You can use equity from your current home as a down payment on your new property. This option requires careful planning since you’ll manage payments on two mortgages.

Note: This option is less common for first-time buyers but can be effective if you’re purchasing an investment property or moving up to a larger home.

4. Down Payment Assistance Programs

First-time homebuyers and those with limited savings may qualify for down payment assistance programs. Often available through state and local governments, these programs can help cover part or all of your down payment.

  • Forgivable Second Mortgage: This is a form of assistance that resembles a second mortgage, but it may be forgiven after a set number of years if you meet certain conditions, such as living in the home for a specified period.
  • Targeted Demographics:
    • First-time homebuyers
    • Low- to moderate-income families
    • Buyers in designated revitalization areas

Each state or locality has different requirements, so check with your local housing authority to learn more about available options.

5. Other Sources for a Down Payment

If you have other assets, there are additional ways to fund your down payment. Here are some alternative sources:

  • Personal Savings: A common choice that involves no loans or additional paperwork.
  • Trust Funds: If you have access to a trust fund, this can be a great way to cover your down payment without repayment requirements.
  • Sale of Investments: If you hold investments like stocks or bonds, selling them can provide funds. Remember to account for any capital gains taxes and consider the impact on your long-term financial goals.


6. Loan Program Differences and Allowable Down Payment Sources

Different loan programs have specific rules about down payment sources, so it’s essential to know which options align with the program you’re using.

  • Conventional Loans:
    • Typically allow personal savings, gifts from immediate family members, and proceeds from investments.
    • Some conventional loans allow second mortgages but with restrictions.
  • FHA Loans:
    • More flexible, allowing gifts from family, friends, employers, and even charitable organizations.
    • Second mortgages may also be acceptable, particularly with down payment assistance programs.
  • VA Loans:
    • Often require no down payment, making them a great option for veterans. If a down payment is required, gifts from family members are allowed.
  • USDA Loans:
    • Typically require no down payment but allow personal savings and gift funds as acceptable sources if one is needed.

Choosing the Best Down Payment Strategy

Selecting the best method for funding your down payment depends on your financial goals, risk tolerance, and current assets. If you’re uncertain about the best approach, consulting with a mortgage professional can provide insights tailored to your unique situation. We are here to help you explore all available options and make informed decisions.

Filed Under: Home Mortgages Tagged With: 401K Withdrawl, Down Payment Options, Second Mortgage

Understanding an Appraisal Contingency in Your Home Purchase

November 6, 2024 by Coleen TeBockhorst

When buying a home, you have the option to include contingencies in your purchase contract. These protect you by setting certain conditions that must be met for the contract to remain valid. If any contingency isn’t satisfied, you can back out of the sale without penalty. Three main types of contingencies help protect buyers: appraisal, financing, and home inspection contingencies. Here’s how each can impact your home buying experience.

The Appraisal Contingency

An appraisal contingency allows you to step back from the sale if the property appraises for less than the agreed purchase price. Since lenders typically only loan up to the appraised value of the home, this contingency is essential to avoid overpaying. If the home appraisal is lower than expected, you can either renegotiate the price with the seller, make up the difference with a larger down payment, or back out of the sale without losing your deposit.

In competitive markets, leaving out this contingency can make you a more attractive buyer, but it’s a trade-off that could leave you paying above market value.

The Financing Contingency

If you’re relying on a mortgage, a financing contingency protects you if you’re unable to secure full loan approval. While pre-approval offers an estimate of what you can afford, the official loan approval depends on final underwriting. With this contingency in place, if your loan falls through, you can back out of the deal and recover your deposit.

The Home Inspection Contingency

This contingency gives you peace of mind by allowing you to have the home inspected for structural issues, hidden damage, or safety concerns. If any serious issues arise, you can negotiate repairs with the seller or even back out of the purchase. A professional home inspector can spot things the average buyer may miss, so this contingency is highly recommended for most homebuyers.

What Happens If the Appraisal is Too Low?

If the property’s appraised value is below the agreed price, you have three main options:

  1. Increase your down payment to cover the difference.
  2. Negotiate a lower purchase price with the seller.
  3. Use the appraisal contingency to walk away from the deal and get your deposit back.

An appraisal contingency can give you leverage in price negotiations, especially if the seller wants to avoid losing the sale. However, in a competitive market, waiving this contingency can make your offer more appealing, as it signals to the seller your commitment to the purchase regardless of appraisal.

Each contingency serves as a financial safeguard, providing flexibility and protection at different stages of the buying process. Including these contingencies in your offer ensures you’re not cornered into a deal that could end up costing you more than anticipated.

Filed Under: Mortgage Tips Tagged With: Appraisal Contingency, Home Buying 101, Mortgage Tips

Understanding “Cash to Close” in Your Home Buying Journey

November 5, 2024 by Coleen TeBockhorst

If you’ve received your Closing Disclosure from your lender, congratulations! You’re almost at the finish line of your home buying journey, ready to celebrate with keys in hand. The Closing Disclosure, or CD, is provided at least three business days before your closing appointment and details your loan terms, projected monthly payments, and the much-discussed “cash to close.” But what exactly is “cash to close,” and how is it calculated?

What is “Cash to Close”?

“Cash to close” is the total amount you’ll need to bring to your closing appointment to finalize your home purchase. It includes your down payment and closing costs, which are necessary to officially transfer ownership of the property to you. Each fee has a specific purpose, ensuring the legal and financial security of both you and the lender.

Breaking Down Closing Costs

Closing costs are part of the cash to close and cover a range of legal, administrative, and logistical fees associated with your mortgage. Here’s a look at some common components:

  • Appraisal Fees: Typically paid by the buyer, this fee covers the cost of determining the fair market value of the home.
  • Attorney Fees: These include charges for preparing closing documents and conducting a title search.
  • Title Insurance: Provides protection if a third party claims ownership of the property.
  • Application & Origination Fees: Cover lender costs for processing and underwriting your loan.
  • Mortgage Insurance: Required for certain loans, this protects the lender if you default.
  • Funding Fees: Charged for specific loan types like FHA, USDA, or VA loans.
  • Pest Inspection Fees: Usually for termite inspections, particularly in certain areas or on specific property types.

Each of these fees will be listed individually on your CD and contribute to your total cash to close amount. Some lenders may allow you to roll certain costs into your loan, but this varies and depends on factors like loan type and lender policies.

Earnest Money Deposit (EMD) and Down Payment

If you made an earnest money deposit when you agreed to purchase the home, this amount is held in escrow and typically applied toward your closing costs. The down payment, a major part of the cash to close, is based on your loan type and the amount you agreed to put down, which can range from as little as 0% to as much as 20% or more of the purchase price. Your lender will review and confirm these details well before closing.

Payment Options for Closing Costs

Lenders usually require a certified payment method. Here are a few options to consider:

  • Cashier’s Check: The most common form, which you can get from your bank. You’ll need the exact amount and payee information.
  • Certified Check: Another bank-issued option, ensuring funds are available and verified.
  • Wire Transfer: Convenient but requires advanced planning. Wire transfers can take a few days and should be carefully verified to avoid fraud.

Note: Cash, personal checks, and credit/debit cards aren’t accepted due to the high amounts and to ensure clear documentation of funds.

Verify all details on your Closing Disclosure and double-check your payment method with your lender. By staying informed and preparing early, you can ensure a seamless transition to homeownership.

Understanding “cash to close” can alleviate some of the uncertainty around finalizing your mortgage and help you walk confidently into your new home!

Filed Under: Home Mortgages Tagged With: Closing Costs, Home Loan Basics, Mortgage

« Previous Page
Next Page »

Contact Coleen

Coleen Tebockhorst

Coleen TeBockhorst
coleen.tebockhorst@citywidehm.com

Senior Loan Officer

Call me! (612) 701-8512

NMLS #274205

Download My Mortgage eGuide today

CW Home Mortgage logo_White

Guaranteed Rate, Inc. DBA Citywide Home Mortgage

Categories

Our Location

10591 165th St. West
Lakeville MN, 55044

Connect With Me

This site is not authorized by the New York State Department of Financial Services. No mortgage loan applications for properties located in New York will be accepted through this site. Operating in the state of California as Guaranteed Rate, Inc. D/B/A Citywide Home Mortgage. If you are a California resident, please review our Privacy Policy to learn more about the categories and business purpose of personal information we may collect and your right to opt-out from the sale of personal information.

Applicant subject to credit and underwriting approval. Not all applicants will be approved for financing. Receipt of application does not represent an approval for financing or interest rate guarantee. Refinancing your mortgage may increase costs over the term of your loan. Restrictions may apply. All information provided in this publication is for informational and educational purposes only, and in no way is any of the content contained herein to be construed as financial, investment, or legal advice or instruction. Citywide Home Mortgage does not guarantee the quality, accuracy, completeness or timelines of the information in this publication. While efforts are made to verify the information provided, the information should not be assumed to be error-free. Some information in the publication may have been provided by third parties and has not necessarily been verified by Citywide Home Mortgage. Citywide Home Mortgage, its affiliates and subsidiaries do not assume any liability for the information contained herein, be it direct, indirect, consequential, special, or exemplary, or other damages whatsoever and howsoever caused, arising out of or in connection with the use of this publication or in reliance on the information, including any personal or pecuniary loss, whether the action is in contract, tort (including negligence) or other tortious action.

Coleen TeBockhorst NMLS ID: 274205 Copyright © 1998-2025 Guaranteed Rate, Inc. D/B/A Citywide Home Mortgage. All rights reserved.

For licensing information, go to: www.nmlsconsumeraccess.org.

NMLS License #2611 – 3940 N Ravenswood Chicago, IL 60613. (866) 508-5515. Equal Housing Lender.

Licensing | Privacy | Terms of Use

Copyright © 2026 · Powered by MySMARTblog

Copyright © 2026 · Genesis Sample Theme on Genesis Framework · WordPress · Log in